Moving to Taiwan
12 ways to move to Taiwan in our guide: 2 talent schemes, 1 working holiday visa, 1 nomad / remote-work visa, 3 investor routes, 1 business / startup route, 1 work visa, 1 student visa, 2 spouse visas.
Remote workers: Digital nomad visa, from $20k a year. Smallest investment: Entrepreneur visa, from TWD 1M ≈ $31k. Tax for newcomers: Taiwan: foreign-source income outside regular income tax, counted only for the Income Basic Tax, 20% tax. Checked against official sources on .
Taiwan offers a range of residence routes for foreign professionals, investors, students, and remote workers. The right path depends on your background and plans, and each route has its own requirements and conditions.
Top options in Taiwan · 1
Talent schemes
Employment Gold Card
Income needed: TWD 160k+ a month ≈ $5,010
Talent schemes · 1

Freelance artist permit
First stay: 3 yrs
Working holiday · 1

Working Holiday
Age limit and funds needed: Ages vary by passport · TWD 100k ≈ $3,130
Nomad / Remote work · 1

Digital nomad visa
Income needed: from $20k a year
Investing · 3

Plum Blossom
Investment needed: from TWD 15M ≈ $469k
Investor resident visa
Investment needed: $200k+
Business / Startup · 1

Entrepreneur visa
Investment needed: from TWD 1M ≈ $31k
Work · 1

Professional work permit
Income needed: TWD 48k+ a month ≈ $1,500
Student · 1

Student visa
Spouse visas · 2

For people married to, or in a partnership with, a citizen or permanent resident.
Spouse of a permanent resident
Spouse of a citizen
First stay: 1 yr
Tax
Special regime
Foreign professional special deduction
Tax relief
Details
- On: Employment income above NT$3,000,000 a year
- Limit: TWD 3M/yr ≈ $94k
Eligible foreign special professionals can exclude half of qualifying annual employment income above NT$3 million from taxable income for the first five tax years in which they meet the residence condition, and their overseas income is excluded from basic income.
Taxed on
Employment income above NT$3,000,000 a year; 50% of the excess is excluded from consolidated gross income.
Who it applies to
- Foreign special professional approved for the first time to reside in Taiwan for work, or holder of an Employment Gold Card, engaged in professional work (Act for the Recruitment and Employment of Foreign Professionals, Art. 22, formerly Art. 20).
- No household registration in Taiwan, and residing in Taiwan for 183 full days in the tax year.
- Annual qualifying employment income exceeds NT$3 million.
- Available for the first five tax years starting from the first year the 183-day condition is met; the exemption application is filed with the return.
Exclusions
- Only half of qualifying employment income above NT$3 million is excluded; income up to NT$3 million is taxed normally.
- Overseas income of these professionals is excluded from basic income when the Income Basic Tax is calculated; other residents add overseas income of NT$1 million or more to basic income.
Limits
- TWD 3,000,000 a year (≈ $93,900) · Employment income above this amount; half of the excess is excluded
Days in the country
- At least 183 days in tax year · Resident-day threshold; no household registration in Taiwan
Tax residence
Tax residence follows presence and household registration: 183 days or more in the tax year with no household registration in Taiwan. Taiwan-source income is taxable even for non-residents; foreign-source income enters the basic income tax calculation for qualifying residents.
Visas
Applies to foreign special professionals, including Employment Gold Card holders, who meet the tax conditions.
Other taxes
VAT/business tax, labour and national health insurance contributions apply separately.
Checked against official sources on Change log
Standard rules
Taiwan progressive income tax rates for residents (2025 tax year)
Progressive rates
Details
- Who: Resident = in Taiwan 183 days or more within a taxable year
- Limit: TWD 590k/yr ≈ $19k
Residents staying 183 days or more in a tax year pay progressive tax from 5% to 40% on net consolidated income; stays of 91 to 182 days are taxed at withholding rates on Taiwan-source income.
Taxed on
Net consolidated income: Taiwan-source income and pay for services rendered in Taiwan minus exemptions, deductions and the basic living expense difference.
Who it applies to
- Resident = in Taiwan 183 days or more within a taxable year; aliens in Taiwan over 90 but under 183 days use withholding rates on Taiwan-source income.
Limits
- TWD 590,000 a year (≈ $18,500) · 5% on net taxable income up to NT$590,000
- TWD 1,330,000 a year (≈ $41,600) · 12% up to NT$1,330,000 (progressive difference NT$41,300)
- TWD 2,660,000 a year (≈ $83,200) · 20% up to NT$2,660,000 (difference NT$147,700)
- TWD 4,980,000 a year (≈ $156,000) · 30% up to NT$4,980,000 (difference NT$413,700); 40% above (difference NT$911,700)
- TWD 7,500,000 a year (≈ $235,000) · Income basic tax test: basic income at or above NT$7,500,000 triggers the alternative minimum tax calculation
Days in the country
- At least 183 days in taxable year · Resident for progressive-rate assessment
- More than 90 days in taxable year · Over 90 but under 183 days: withholding on Taiwan-source income
Tax residence
Overseas income is excluded from the basic income of qualifying foreign specialist professionals; for others aggregated overseas income of NT$1,000,000 or more is included in basic income.
Visas
Tax residence follows days of presence, not visa category.
Other taxes
Non-residents with salaries are withheld at 18%; dividends to non-residents at 21%.
Checked against official sources on Change log
Standard rules
Taiwan: foreign-source income outside regular income tax, counted only for the Income Basic Tax
20% tax
Details
- Who: Resident of the R.O.C.: domicile and residence in Taiwan
- Limit: TWD 1M/yr ≈ $31k
Taiwan's regular income tax covers income from sources in the R.O.C.; income from outside Taiwan is excluded from consolidated gross income but is added to 'basic income' when a filing unit's overseas income is NT$1,000,000 or more, and the Income Basic Tax is 20% of basic income above NT$7,500,000, payable only when it exceeds the regular tax.
Taxed on
Regular income tax: R.O.C.-source income plus pay for services performed in the R.O.C. even if paid abroad. Income Basic Tax: net taxable income plus overseas income (aggregate of NT$1,000,000 or more per filing unit) plus other specified items, less NT$7,500,000, times 20%.
Who it applies to
- Resident of the R.O.C.: domicile and residence in Taiwan, or no domicile but residing 183 days or more in the tax year.
- Foreign-source income counts toward basic income when the filing unit's aggregate foreign-source income is NT$1,000,000 or more (below that it may be excluded).
- Tax paid overseas on that income may be credited against the basic tax, limited to the increase in basic tax caused by including that income.
Exclusions
- Foreign specialist professionals with first-time work approval or an Employment Gold Card, in the five-year relief on employment income above NT$3,000,000, have foreign-source income excluded from basic income.
Limits
- TWD 1,000,000 a year (≈ $31,300) · Aggregate overseas income per filing unit from which overseas income is added to basic income
- TWD 7,500,000 a year (≈ $235,000) · Amount deducted from basic income before applying the 20% Income Basic Tax rate
Days in the country
- At least 183 days in taxable year (calendar year) · Resident of the R.O.C. when without domicile
Tax residence
A resident is domiciled and residing in Taiwan, or without domicile residing 183 days or more in the tax year. Non-resident aliens staying 90 days or less are taxed by withholding on R.O.C.-source income.
Visas
Tax treatment depends on the 183-day residence status; the Employment Gold Card carries a separate five-year relief on employment income.
Other taxes
Aliens staying 91 to 182 days file at the withholding rate; VAT and national health insurance apply separately.
Checked against official sources on Change log
Standard rules
Taiwan progressive income tax rates for residents (2026 tax year, return filed May 2027)
Progressive rates
Details
- Who: Resident for the progressive scale: domiciled in Taiwan and residing there
- Limit: TWD 610k/yr ≈ $19k
For tax year 2026 residents pay progressive tax from 5% to 40% on net consolidated income, with brackets raised to NT$610,000, NT$1,380,000, NT$2,770,000 and NT$5,190,000; the personal exemption rises to NT$101,000 and the single standard deduction to NT$136,000. Foreign-source income is outside the regular income tax and is added only to basic income for the 20% Income Basic Tax when a filing unit has NT$1,000,000 or more.
Taxed on
Net consolidated income for calendar year 2026: Taiwan-source income and pay for services rendered in Taiwan, minus exemptions, deductions and the basic living expense difference. Rates: 5% up to NT$610,000; 12% from NT$610,001 to NT$1,380,000 (progressive difference NT$42,700); 20% to NT$2,770,000 (difference NT$153,100); 30% to NT$5,190,000 (difference NT$430,100); 40% above NT$5,190,000 (difference NT$949,100). Top marginal rate shown as ratePercent.
Who it applies to
- Resident for the progressive scale: domiciled in Taiwan and residing there, or without domicile and residing in Taiwan 183 days or more in the taxable year (Income Tax Act Art. 7).
- Brackets, exemptions and deductions were adjusted for the 2026 tax year because the average consumer price index rose 4.13% against the 2024 reference year (above the 3% trigger); they apply to returns filed in May 2027.
- Exemption per person (taxpayer, spouse, dependent) NT$101,000, NT$151,500 for those aged 70 or over; standard deduction NT$136,000 single, NT$272,000 married; special deduction for employment income NT$227,000; disability special deduction NT$227,000.
Exclusions
- Individuals not resident in Taiwan for the progressive scale (stays of 183 days or fewer without domicile) are taxed through withholding on Taiwan-source income at the rates in the 2025 record (18% on salaries, 21% on dividends).
- Foreign-source income is outside the progressive base but may enter the income basic tax; the NT$7,500,000 basic income exemption and 20% basic tax rate are unchanged for 2026 (no CPI adjustment under the Income Basic Tax Act).
Limits
- TWD 610,000 a year (≈ $19,100) · 5% on net consolidated income up to NT$610,000
- TWD 1,380,000 a year (≈ $43,200) · 12% up to NT$1,380,000
- TWD 2,770,000 a year (≈ $86,700) · 20% up to NT$2,770,000
- TWD 5,190,000 a year (≈ $162,000) · 30% up to NT$5,190,000; 40% above
- TWD 7,500,000 a year (≈ $235,000) · Income basic tax: basic income at or below NT$7,500,000 is exempt from the basic tax (unchanged for 2026)
Days in the country
- At least 183 days in taxable year (calendar year) · Resident without domicile: residing in Taiwan 183 days or more in total in the taxable year (Income Tax Act Art. 7(2)).
Tax residence
Tax residence follows domicile and days of presence in the calendar year. Under Art. 8(3) remuneration for services rendered in Taiwan is Taiwan-source; an individual not resident who stays no more than 90 days in the year and is paid by an employer outside Taiwan has no Taiwan-source remuneration.
Visas
Tax residence follows days of presence, not visa category.
Other taxes
Non-resident withholding is unchanged from the 2025 record; the foreign specialist half-exclusion above NT$3,000,000 is in “Foreign professional special deduction”. Tax-year 2025 and 2024 returns use “Taiwan progressive income tax rates for residents”.
Checked against official sources on Change log
Checked against official sources on Change log
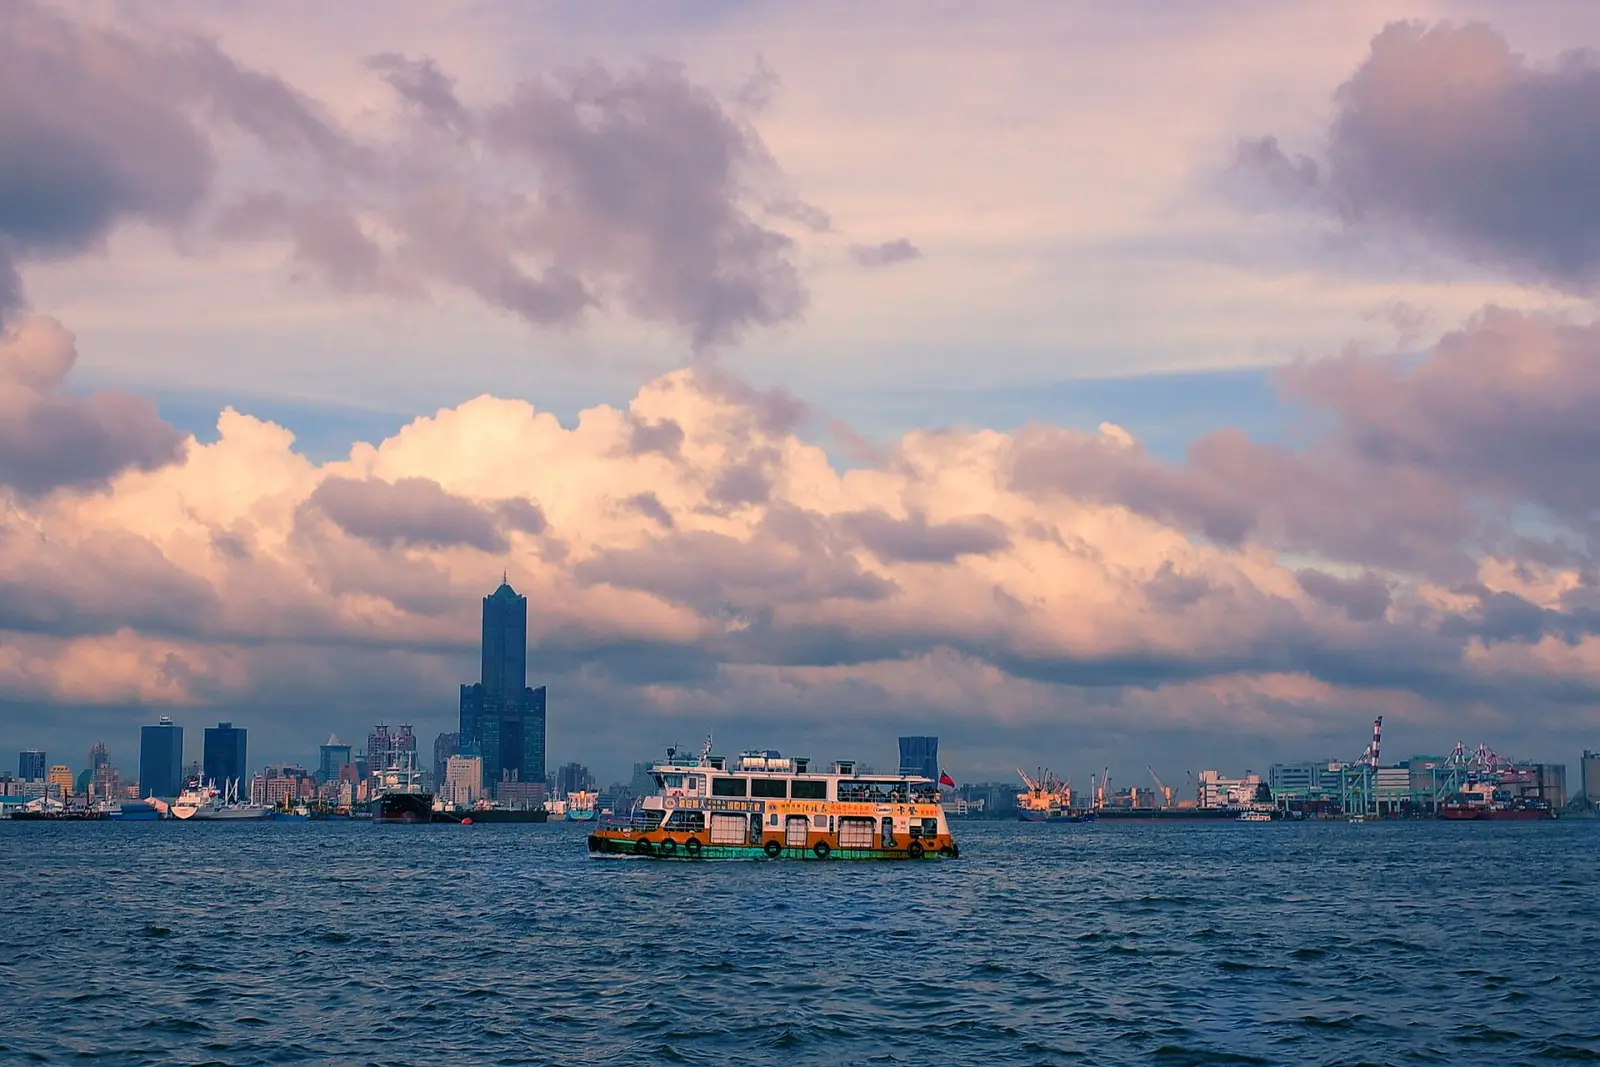
Taiwan in pictures
Shorter stays · 1
Work
Job-seeker visa
Income needed: TWD 48k+ a month ≈ $1,500
Switch to later · 2
Work
Graduate extension
First stay: 2 yrs
Work
Graduate work permit (points)
First stay: 3 yrs
Path to permanent residence · 1
- PR after 5 years · Alien Permanent Resident Certificate (APRC)
Arriving in Taiwan: first steps
- Arrange health insurance that covers your entire intended stay, as required for many routes.
- Register your residential address with the National Immigration Agency after arrival.
- Open a local bank account for daily transactions and salary deposits.
- Apply for an Alien Resident Certificate (ARC) if your route requires it, and carry your passport and visa documents.
- Keep records of your entry and stay dates to monitor tax residency thresholds.
Questions people ask
What special talent visas does Taiwan have?
Taiwan has 2 talent schemes. Employment Gold Card asks for an income of at least TWD 160,000 a month (≈ $5,010) and gives a first stay of 3 years that can be renewed. Freelance artist permit gives a first stay of 3 years that can be renewed.
Does Taiwan have a working holiday visa?
Yes. Taiwan has 1 working holiday visa. Working Holiday gives a first stay of 6 months.
What is the Taiwan digital nomad visa income requirement in 2026?
Taiwan has 1 nomad or remote-work visa. Digital nomad visa asks for an income from $20,000 a year and gives a first stay of 6 months that can be renewed.
How much do you need to invest for residency in Taiwan?
Taiwan has 3 investor routes. Plum Blossom · Bonds asks for an investment of at least TWD 30,000,000 (≈ $939,000). Plum Blossom · Business asks for an investment of at least TWD 15,000,000 (≈ $469,000). Investor resident visa asks for an investment of at least $200,000.
Can I move to Taiwan by starting a business?
Taiwan has 1 business or startup route. Entrepreneur visa asks for an investment from TWD 1,000,000 (≈ $31,300) and gives a first stay of 2 years that can be renewed.
What work visas does Taiwan offer foreigners?
Taiwan has 1 work visa. Professional work permit asks for a salary of at least TWD 47,971 a month (≈ $1,500) and gives a first stay of 3 years that can be renewed.
How do I get a student visa for Taiwan?
Taiwan has 1 student visa. It is Student visa.
Can I join my spouse or partner in Taiwan?
Yes. Taiwan has 2 spouse visas. Spouse of a citizen gives a first stay of 1 year that can be renewed. There is also Spouse of a permanent resident.
Compare with
≈ USD figures are approximate: daily reference rates from ExchangeRate-API, dated 12 Oct 2026, refreshed when the site is updated.
Ask the AI about Taiwan AI
An AI assistant answers from the published records on this page and cites them. It can't assess your personal eligibility. Don't include personal details.