Moving to South Korea
17 ways to move to South Korea in our guide: 1 talent scheme, 1 working holiday visa, 1 nomad / remote-work visa, 4 investor routes, 2 business / startup routes, 3 work visas, 2 student visas, 1 route by nationality or ancestry, 2 spouse visas.
Remote workers: Workcation visa (F-1-D), from ₩52.4M a year ≈ $39k. Smallest investment: D-8-1 Business Investment, ₩100M+ ≈ $75k. Tax for newcomers: Korea: remittance basis for foreign-source income of foreigners with 5 years or less of residence, Remittance basis (5 years). Checked against official sources on .
South Korea offers a wide range of visa routes for different situations, from highly skilled professionals and investors to remote workers and students. The right route depends on your background, purpose of stay, and whether you are already in the country or applying from abroad.
Talent schemes · 1

Top-Tier · science
First stay: 5 yrs
Working holiday · 1

Working Holiday (H-1)
Age limit and funds needed: Ages vary by passport · ₩3M ≈ $2,250
Nomad / Remote work · 1

Workcation visa (F-1-D)
Income needed: from ₩52.4M a year ≈ $39k
Investing · 4

Business / Startup · 2

Startup Korea Special (D-8-4)
First stay: 5 yrs
D-8 Tech Start-up
First stay: 5 yrs
Work · 3

Job Seeker (D-10)
First stay: 1 yr
Special Occupation (E-7)
Income needed: from ₩25.9M a year ≈ $19k
Top-Tier · industry job
Income needed: from ₩149.9M a year ≈ $112k
Student · 2

D-4 language study
First stay: 2 yrs
Student visa (D-2)
First stay: 2 yrs
For your nationality or ancestry · 1

Open only to citizens of certain countries or to people with family roots here. Unlike free movement, each needs an application.
Korean F-4 overseas Korean visa
First stay: 2 yrs
Spouse visas · 2

For people married to, or in a partnership with, a citizen or permanent resident.
Spouse of a citizen
Income needed: from ₩25.2M a year ≈ $19k
Spouse of a permanent resident
First stay: 5 yrs
Tax
Tax obligations depend on your residency status. Residents are taxed on worldwide income, while non-residents are taxed only on Korean-source income. Special regimes exist for foreign employees, including an optional flat rate on employment income for a limited period, and reductions for qualifying foreign engineers and R&D degree holders.
Special regime
Optional flat tax rate for foreign employees
19% tax
Details
- Who: Foreign national employee or director with Korean employment income
Foreign employees who first start work in Korea on or before 31 December 2026 can elect a 19% flat rate on employment income for 20 years from the tax year of first work in Korea. A government bill published on 3 August 2026 proposes raising the rate to 21% and extending the period through 31 December 2029; it is a proposal, not the law in force.
Taxed on
Employment income (gross salary), separately taxed at a flat rate instead of progressive rates.
Who it applies to
- Foreign national employee or director with Korean employment income.
- First starts work in Korea on or before 31 December 2026 (Restriction of Special Taxation Act Art. 18-2(2)).
- Election applies to employment income received up to the end of the tax year ending within 20 years of the first day of work in Korea.
- Applies to the tax office or employer; withholding at 19% is possible.
- Proposed change, not law: the 2026 Tax Revision Bill published by the Ministry of Finance and Economy on 3 August 2026 would raise the preferential rate for foreign workers from 19% to 21% and extend the application period by three years, through 31 December 2029.
Exclusions
- Not available to employees of related-party (special-relationship) companies, other than the foreign-invested enterprises specified by decree; the National Tax Service gives the example of a worker who holds 30% or more of the employer's shares during the employment.
- Electing the flat rate removes non-taxation, deductions, reductions and tax credits under the Income Tax Act and the Special Taxation Act, apart from certain welfare-type benefits specified by decree; employer-paid health and employment insurance are not tax-exempt under the flat rate (NTS guide). The income is not added to comprehensive income.
Tax residence
Residents (domicile or residence in Korea) are taxed on worldwide income; non-residents only on Korean-source income.
Visas
Applies to foreign employees of any visa category with Korean employment income; not tied to a visa.
Other taxes
Local income tax and national health, pension and employment insurance contributions apply separately.
Checked against official sources on Change log
Special regime
Income tax reduction for qualifying foreign engineers
Tax relief
Details
Deadline 31 December 2026: only foreign engineers whose first day of work in Korea is on or before that date qualify. They get a 50% income tax reduction on pay from a Korean employer for 10 years from their first day of work. The 70% rate for materials, parts and equipment engineers was open only to people who started work on or before 31 December 2022.
Taxed on
Income tax on employment income received for work provided in Korea to a domestic employer: 50% of the tax is reduced on income arising up to the month containing the tenth anniversary of the first day of work in Korea.
Who it applies to
- Foreign engineer as defined by presidential decree: a foreign worker providing technology under an engineering technology import contract, or a holder of a bachelor's or higher science or engineering degree with overseas research and development experience (National Tax Service guide).
- First day of work in Korea on or before 31 December 2026 (Restriction of Special Taxation Act Art. 18(1)).
- The pay is employment income for work provided in Korea to a domestic employer.
- From employment income paid on or after 28 February 2025, outstanding overseas talent under Article 28(1) of the Advanced Industry Talent Special Act can also claim (National Tax Service guide).
- The reduction is applied for through the employer (withholding agent), which withholds the reduced amount (Art. 18(3) and (4)).
Exclusions
- Materials, parts and equipment engineers get 70% for the first 3 years and 50% for the following 2 years only if their first day of work in Korea was on or before 31 December 2022; later starters get the general 50% for 10 years.
- Pay from an employer outside Korea is not covered: the reduction is for work provided to a domestic employer.
- Cannot be combined with the 19% flat rate: electing the flat rate removes income tax reductions.
- Applies to employment income only; social insurance is separate.
Tax residence
Applies to employment income of the worker in Korea.
Visas
Independent of visa type.
Other taxes
Individual local income tax is reduced by 10% of the income tax reduction (Restriction of Special Local Taxation Act Art. 167-2, applied to 31 December 2026). Social insurance contributions are separate.
Checked against official sources on Change log
Standard rules
Korea progressive comprehensive income tax rates (2023 to 2025 attribution years)
Progressive rates
Details
- On: Comprehensive income tax base (taxable income) after deductions
- Who: Residents with domicile or residence in Korea
- Limit: ₩14M/yr ≈ $11k
Residents pay progressive tax from 6% to 45% on comprehensive income; the NTS rates table shows eight bands. Residents are taxed on worldwide income, including foreign-source income; foreign nationals resident for five years or less in the last ten are taxed on foreign-source income only when it is paid in or remitted to Korea.
Taxed on
Comprehensive income tax base (taxable income) after deductions; tax = base times rate minus progressive deduction.
Who it applies to
- Residents with domicile or residence in Korea; foreign employees can instead elect the 19% flat rate on employment income where eligible.
- Resident means having a domicile in Korea or a residence of 183 days or more.
Exclusions
- Non-residents are taxed only on Korean-source income (Income Tax Act Art. 3(2)).
Limits
- KRW 14,000,000 a year (≈ $10,500) · 6% band up to KRW 14,000,000 (≈ $10,500)
- KRW 50,000,000 a year (≈ $37,500) · 15% band up to KRW 50,000,000 (≈ $37,500) (deduction KRW 1,260,000 (≈ $940))
- KRW 88,000,000 a year (≈ $66,000) · 24% band up to KRW 88,000,000 (≈ $66,000) (deduction KRW 5,760,000 (≈ $4,320))
- KRW 150,000,000 a year (≈ $112,000) · 35% band up to KRW 150,000,000 (≈ $112,000) (deduction KRW 15,440,000 (≈ $11,600))
- KRW 300,000,000 a year (≈ $225,000) · 38% band up to KRW 300,000,000 (≈ $225,000) (deduction KRW 19,940,000 (≈ $15,000))
- KRW 500,000,000 a year (≈ $375,000) · 40% band up to KRW 500,000,000 (≈ $375,000) (deduction KRW 25,940,000 (≈ $19,400))
- KRW 1,000,000,000 a year (≈ $750,000) · 42% band up to KRW 1,000,000,000 (≈ $750,000) (deduction KRW 35,940,000 (≈ $26,900)); 45% above (deduction KRW 65,940,000 (≈ $49,400))
Days in the country
- At least 183 days in continuous residence in Korea · A person with no domicile who has a residence in Korea for 183 days or more is a resident
Tax residence
Foreign residents with a total domicile or residence period of five years or less in the ten years before the end of the tax period are taxed on foreign-source income only to the extent it is paid in Korea or remitted to Korea (see “Korea: remittance basis for foreign-source income of foreigners with 5 years or less of residence”).
Visas
Applies by tax residence, not visa type.
Other taxes
Local income tax is charged on top of national income tax; the table covers 2023 to 2025 attribution years as published by the NTS.
Checked against official sources on Change log
Special regime
Korea: remittance basis for foreign-source income of foreigners with 5 years or less of residence
Tax relief
Details
- On: Foreign-source income that is paid in Korea or remitted to Korea
- Who: Foreign national (not a Korean citizen) who is a Korean tax resident
A foreign resident whose total period of domicile or residence in Korea is five years or less in the ten years before the end of the tax period is taxed on foreign-source income only to the extent it is paid in Korea or remitted to Korea.
Taxed on
Foreign-source income that is paid in Korea or remitted to Korea; Korean-source income and all other income is taxed in full under the progressive income tax.
Who it applies to
- Foreign national (not a Korean citizen) who is a Korean tax resident.
- Sum of periods with a domicile or residence in Korea over the 10 years before the end of the taxable period is 5 years or less.
- Resident means having a domicile in Korea or a residence of 183 days or more.
Exclusions
- After more than five years of domicile or residence within the ten-year look-back, foreign-source income is taxed on a worldwide basis as for Korean residents.
- Income not paid or remitted into Korea stays outside the Korean base for qualifying foreigners.
Days in the country
- At least 183 days in continuous residence in Korea · A person with no domicile who has a residence in Korea for 183 days or more is a resident
Tax residence
The five-year test is counted over the ten years before the end of the relevant taxable period; non-residents are taxed only on Korean-source income (article 3(2)).
Visas
Applies by tax residence status and nationality, not by visa category.
Other taxes
Local income tax, VAT and social insurance apply separately; see “Optional flat tax rate for foreign employees” and “Korea progressive comprehensive income tax rates” for employment tax rates.
Checked against official sources on Change log
Checked against official sources on Change log
South Korea in pictures
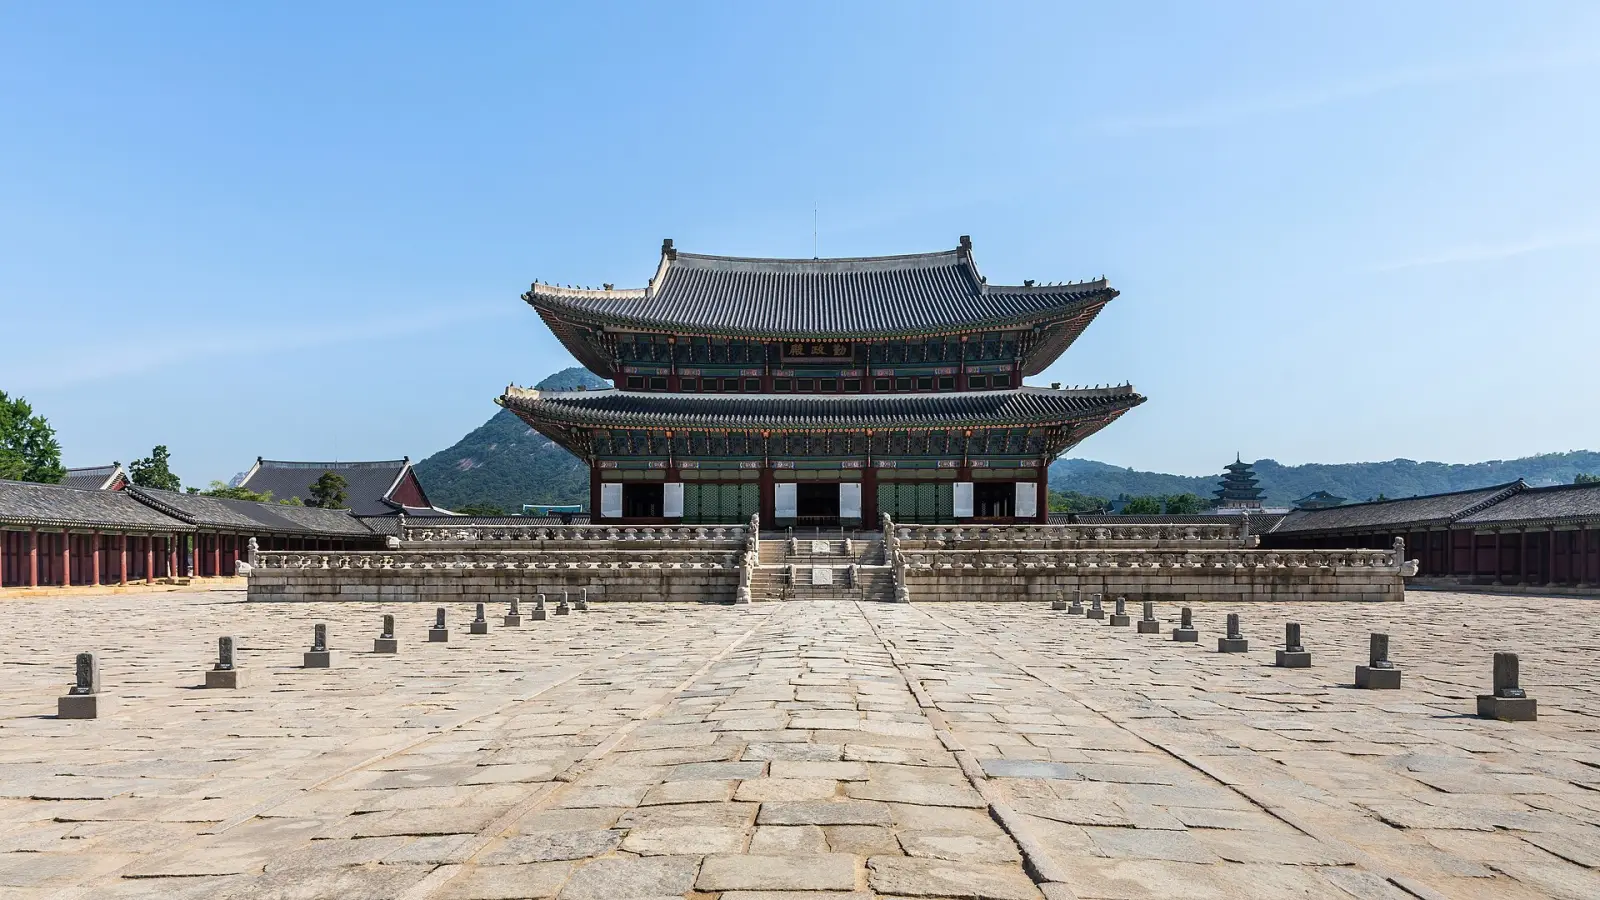
Switch to later · 6
Investing
F-2 · $500k investor
Investment needed: from $300k
Business / Startup
D-9 trade (after study)
Investment needed: ₩100M+ ≈ $75k
Work
K-STAR to F-2
First stay: 5 yrs
Work
F-2-R regional visa
First stay: 5 yrs
Work
F-2 Points talent
First stay: 5 yrs
Work
E-7-4 Skilled points
Income needed: ₩26M+ a year ≈ $20k
Path to permanent residence · 2
- PR after 3 years · Resident, Long-term Resident with High-amount Investment (F-2)
- PR · Permanent Resident (F-5)
Arriving in South Korea: first steps
- Ensure you have private medical insurance that meets the required coverage for your visa route.
- Secure a residential address, such as a lease or accommodation booking, especially if required for your visa.
- Open a Korean bank account for managing finances and receiving payments if needed.
- Register with the local immigration office and apply for an Alien Registration Card if your stay requires it.
- Check if your visa route requires additional registrations, such as with the tax office or health insurance system.
- Keep your passport, visa documents, and proof of address accessible for any official appointments.
Questions people ask
What special talent visas does South Korea have?
South Korea has 1 talent scheme. Top-Tier · science gives a first stay of 5 years.
Does South Korea have a working holiday visa?
Yes. South Korea has 1 working holiday visa. Working Holiday (H-1) gives a first stay of 1 year.
What is the South Korea digital nomad visa income requirement in 2026?
South Korea has 1 nomad or remote-work visa. Workcation visa (F-1-D) asks for an income from KRW 52,410,000 a year (≈ $39,300) and gives a first stay of 1 year that can be renewed.
How much do you need to invest for residency in South Korea?
South Korea has 4 investor routes. F-5 investor · ₩3bn asks for an investment of at least KRW 3,000,000,000 (≈ $2,250,000). F-2 investor · ₩1.5bn asks for an investment of at least KRW 1,500,000,000 (≈ $1,120,000) and gives a first stay of 5 years that can be renewed. Jeju property investor asks for an investment of at least KRW 1,000,000,000 (≈ $750,000) and gives a first stay of 5 years that can be renewed.
Can I move to South Korea by starting a business?
South Korea has 2 business or startup routes. Startup Korea Special (D-8-4) gives a first stay of 5 years. D-8 Tech Start-up gives a first stay of 5 years that can be renewed.
What work visas does South Korea offer foreigners?
South Korea has 3 work visas. Job Seeker (D-10) gives a first stay of 1 year that can be renewed. Special Occupation (E-7) asks for a salary from KRW 25,890,000 a year (≈ $19,400) and gives a first stay of 3 years that can be renewed. Top-Tier · industry job asks for a salary from KRW 149,865,000 a year (≈ $112,000) and gives a first stay of 5 years.
How do I get a student visa for South Korea?
South Korea has 2 student visas. D-4 language study gives a first stay of 2 years that can be renewed. Student visa (D-2) gives a first stay of 2 years that can be renewed.
Can my nationality or ancestry give me residence in South Korea?
Yes. South Korea has 1 route by nationality or ancestry. Korean F-4 overseas Korean visa gives a first stay of 2 years that can be renewed.
Can I join my spouse or partner in South Korea?
Yes. South Korea has 2 spouse visas. Spouse of a citizen asks for an income from KRW 25,195,752 a year (≈ $18,900) and gives a first stay of 3 years that can be renewed. Spouse of a permanent resident gives a first stay of 5 years.
Does South Korea have a special tax regime for new residents?
Yes: Korea: remittance basis for foreign-source income of foreigners with 5 years or less of residence. A foreign resident whose total period of domicile or residence in Korea is five years or less in the ten years before the end of the tax period is taxed on foreign-source income only to the extent it is paid in Korea or remitted to Korea. It is separate from the visa and has its own conditions.
Compare with
≈ USD figures are approximate: daily reference rates from ExchangeRate-API, dated 12 Oct 2026, refreshed when the site is updated.
Ask the AI about South Korea AI
An AI assistant answers from the published records on this page and cites them. It can't assess your personal eligibility. Don't include personal details.