Moving to Brazil
8 ways to move to Brazil in our guide: 1 nomad / remote-work visa, 2 investor routes, 1 work visa, 1 student visa, 1 route by nationality or ancestry, 2 spouse visas.
Remote workers: Digital nomad visa, $1,500+ a month. Smallest investment: Investor · R$500k in a company, from BRL 150k ≈ $30k. Checked against official sources on .
Brazil has several temporary visa routes for foreigners, including digital nomads, workers, and students. Visas and tax are separate.
Nomad / Remote work · 1

Digital nomad visa
Income needed: $1,500+ a month
Investing · 2

Investor
Investment needed: from BRL 150k ≈ $30k
- R$500k in a companyfrom BRL 150k ≈ $30k
- R$1M propertyfrom BRL 700k ≈ $140k
Work · 1

Student · 1

Student visa
First stay: 1 yr
For your nationality or ancestry · 1

Open only to citizens of certain countries or to people with family roots here. Unlike free movement, each needs an application.
Spouse visas · 2

For people married to, or in a partnership with, a citizen or permanent resident.
Spouse of a resident
Spouse of a citizen
Free movement and visa-free stays · 2
Tax
If you become a Brazilian tax resident, you are generally taxed on your foreign-source income under resident rules, though treaty or reciprocity credits may apply.
Standard rules
Brazil personal income tax: residents taxed on worldwide income, progressive 0-27.5% plus 2026 reduction and minimum tax on income above R$600,000
27.5% tax
Details
- On: Worldwide income of tax residents, reported monthly
- Who: Permanent visa holders are resident from the date of arrival
- Limit: BRL 5,000/mo ≈ $1,000
Brazilian tax residents are taxed on worldwide income at progressive rates up to 27.5%, with foreign-source income reported through Carnê-Leão; since 1 January 2026 a reduction cancels the tax on taxable monthly income up to R$5,000. Under Lei 15.270 of 26 November 2025 the minimum tax on total income above R$600,000 applies to income received in calendar year 2026, assessed in the annual return filed in 2027 (exercício 2027).
Taxed on
Worldwide income of tax residents, reported monthly (Carnê-Leão) and in the annual return; Brazilian-source income of non-residents, taxed at source. Monthly table from January 2026: exempt up to R$2,428.80; 7.5% to R$2,826.65 (deduction R$182.16); 15% to R$3,751.05 (R$394.16); 22.5% to R$4,664.68 (R$675.49); 27.5% above (R$908.73). Annual table for calendar year 2026 (exercício 2027): exempt to R$29,145.60; 7.5% to R$33,919.80; 15% to R$45,012.60; 22.5% to R$55,976.16; 27.5% above. Top marginal rate shown as ratePercent.
Who it applies to
- Permanent visa holders are resident from the date of arrival. Holders of a temporary visa who come to work under an employment relationship (or as a Mais Médicos scholarship doctor) are also resident from the date of arrival. Other temporary visa holders become resident on completing 184 days, continuous or not, within up to 12 months, or earlier on obtaining a permanent visa or an employment relationship if that occurs before 184 days.
- If 184 days are not completed within a 12-month period, a new period of up to 12 months starts on the next entry.
- Minimum tax (Lei 15.270 art. 16-A): applies from exercício 2027, calendar year 2026, to an individual whose total income received in the calendar year exceeds R$600,000. The rate is 10% at R$1,200,000 or more and rises linearly from 0 to 10% between R$600,000 and R$1,200,000 (rate % = income / 60,000 minus 10); the tax due is the rate times the base, less income tax due in the annual return, tax withheld exclusively at source, and other credits listed in art. 16-A paragraph 3. The law entered into force on publication (26 November 2025) with effects from 1 January 2026 (art. 8).
Exclusions
- No exemption or reduced regime for foreign-source income of new residents exists in the Carnê-Leão or residence rules.
- Tax paid abroad can be offset only where a treaty or reciprocity act exists.
- Dividends and profits above R$50,000 per month paid by one company to one resident individual carry 10% withholding from January 2026 (art. 6-A); dividends from results up to calendar year 2025 approved by 31 December 2025 are excluded.
- Non-residents are taxed only on Brazilian-source income; their foreign-source income is outside Brazilian tax.
Limits
- BRL 5,000 a month (≈ $1,000) · Taxable monthly income up to which the Lei 15.270 reduction (up to R$312.89) cancels the income tax due, from January 2026
- BRL 7,350 a month (≈ $1,470) · Monthly taxable income from which no reduction applies; between R$5,000.01 and R$7,350 the reduction is R$978.62 minus 0.133145 times the income
- BRL 60,000 a year (≈ $12,000) · Annual taxable income up to which the annual reduction (up to R$2,694.15) cancels the tax; reduction ends at R$88,200 (calendar year 2026)
- BRL 50,000 a month (≈ $10,000) · Dividends from one company to one resident individual above this amount in a month carry 10% withholding
- BRL 600,000 a year (≈ $120,000) · Total income received in calendar year 2026 above which the minimum tax applies (exercício 2027); 10% from R$1,200,000
Days in the country
- At least 184 days in up to 12 months, temporary visa holders · Presence in Brazil, continuous or not, makes a temporary-visa holder a resident on the day the 184th day is completed
Tax residence
Foreign-source income is converted to US dollars at the foreign central-bank rate on the receipt date and then to reais at the Banco Central rate (Carnê-Leão rules).
Visas
Residence for tax purposes follows the visa type and days present: permanent visa gives residence from arrival, temporary visa from the 184th day or earlier permanent visa or employment.
Other taxes
Offshore entities and trusts are taxed under Lei 14.754 of 2023; social security contributions and state or municipal taxes apply separately.
Checked against official sources on Change log
Checked against official sources on Change log
Brazil in pictures
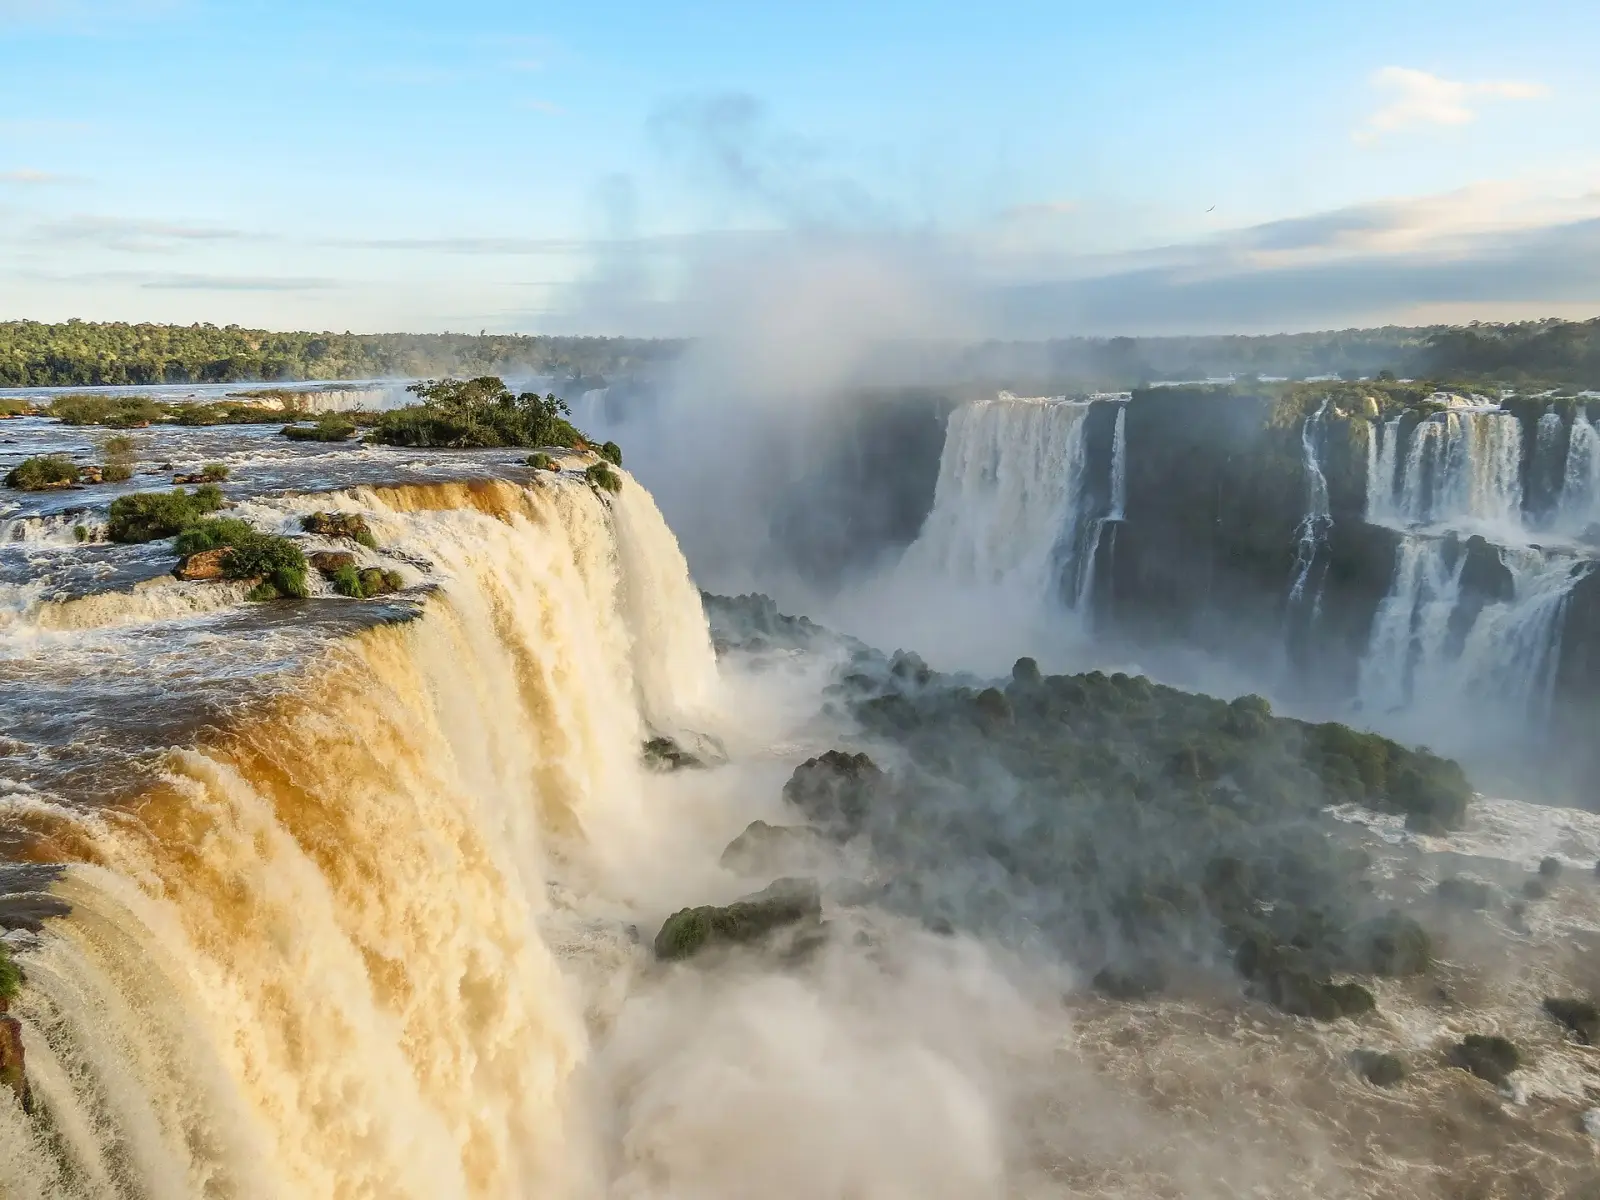
Path to permanent residence · 1
- Citizenship · Brazilian nationality by birth for children born abroad to a Brazilian parent (Constitution Article 12 I c) – consular birth registration
Arriving in Brazil: first steps
- Check if you need health insurance as part of your visa application.
- Register your address with the Federal Police within the required timeframe.
- Open a Brazilian bank account if needed for local transactions.
Questions people ask
What is the Brazil digital nomad visa income requirement in 2026?
Brazil has 1 nomad or remote-work visa. Digital nomad visa asks for an income of at least $1,500 a month and gives a first stay of 1 year that can be renewed.
How much do you need to invest for residency in Brazil?
Brazil has 2 investor routes. Investor · R$1M property asks for an investment from BRL 700,000 (≈ $140,000) and gives a first stay of 4 years that can be renewed. Investor · R$500k in a company asks for an investment from BRL 150,000 (≈ $30,100).
What work visas does Brazil offer foreigners?
Brazil has 1 work visa. Work visa gives a first stay of 2 years that can be renewed.
How do I get a student visa for Brazil?
Brazil has 1 student visa. Student visa gives a first stay of 1 year that can be renewed.
Can my nationality or ancestry give me residence in Brazil?
Yes. Brazil has 1 route by nationality or ancestry. It is Brazilian nationality by descent.
Can I join my spouse or partner in Brazil?
Yes. Brazil has 2 spouse visas. There is also Spouse of a resident and Spouse of a citizen.
Compare with
≈ USD figures are approximate: daily reference rates from ExchangeRate-API, dated 12 Oct 2026, refreshed when the site is updated.
Ask the AI about Brazil AI
An AI assistant answers from the published records on this page and cites them. It can't assess your personal eligibility. Don't include personal details.
Sources (5)
Official sources
- Resolução Normativa CNIg nº 36 — investimento imobiliário · Ministério da Justiça e Segurança Pública · checked 2026-10-11 · published 2018-10-09
- Lei nº 13.445/2017 (Lei de Migração), art. 30 · Presidência da República · checked 2026-10-10 · published 2017-05-24
- Taxas — Polícia Federal (imigração) · Polícia Federal · checked 2026-10-11
- Resolução Normativa CNIg nº 36/2018 (as amended by Resoluções CNIG/MJSP nº 46/2021 and nº 49/2024) · Ministério da Justiça e Segurança Pública · checked 2026-10-11
- Taxas de imigração — isenções (nacionais da CPLP) · Polícia Federal do Brasil · checked 2026-10-11