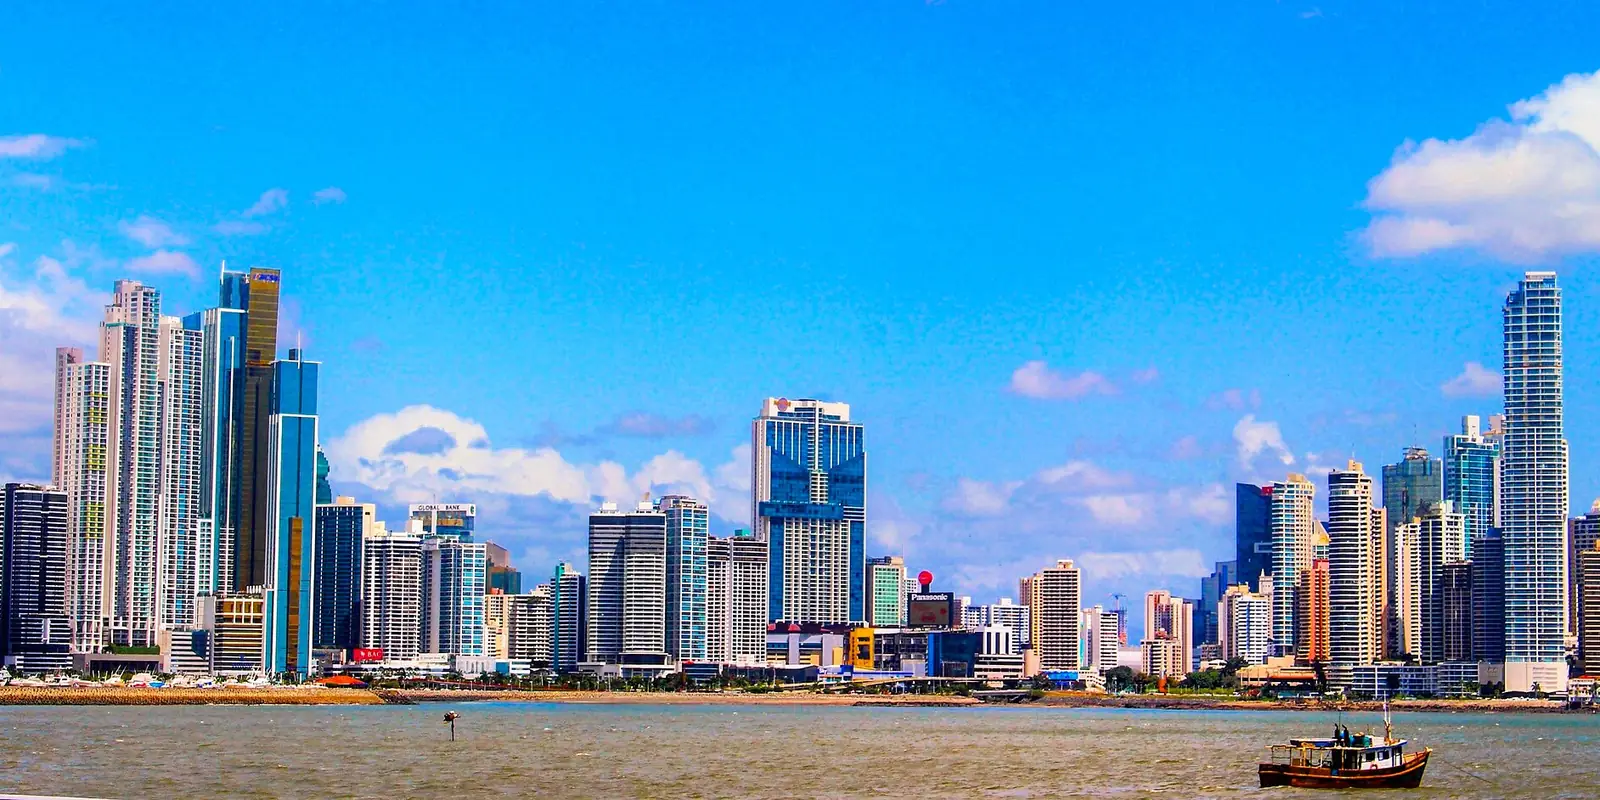
Moving to Panama
8 ways to move to Panama in our guide: 1 nomad / remote-work visa, 3 investor routes, 2 pay-to-stay routes, 1 work visa, 1 spouse visa.
Remote workers: Remote worker visa, PAB 36k+ a year ≈ $36k. Smallest investment: Friendly Nations residence, from PAB 200k ≈ $200k. Tax for newcomers: Panama territorial income tax, Territorial. Checked against official sources on .
Panama offers a set of residence routes that mix investment, pension income and remote work, with a long-standing territorial tax system. The records describe permanent residence for qualified investors, pensioners and nationals of certain friendly countries, plus a short-stay visa for remote workers.
Nomad / Remote work · 1

Remote worker visa
Income needed: PAB 36k+ a year ≈ $36k
Investing · 3

Qualified Investor
Investment needed: from PAB 300k ≈ $300k
Retire or live on savings · 2

Retired rentista
Income needed: PAB 850+ a month ≈ $850
Pensionado residence
Income needed: from PAB 750 a month ≈ $750
Work · 1

Friendly Nations residence
Investment needed: from PAB 200k ≈ $200k
Spouse visas · 1

For people married to, or in a partnership with, a citizen or permanent resident.
Spouse of a citizen
First stay: 2 yrs
Tax
Panama taxes income produced inside Panama only. The taxable base is gross income less foreign-source income, exempt income and deductible costs, and the personal return has a separate line for foreign-source income. The records note no residency test, so how your foreign-source income is treated depends on the territorial rules rather than on holding a permit.
Special regime
Panama territorial income tax (foreign-source income outside the tax base)
Tax relief
Details
- Who: Applies to every taxpayer, natural or legal, national or foreign
Panama taxes income produced inside Panama only; the taxable base of a taxpayer is gross income less foreign-source income, exempt income and deductible costs, and the DGI personal return has a separate line for foreign-source income.
Taxed on
Taxable income = gross income minus foreign-source income, exempt/non-taxable income and deductible costs and expenses (Código Fiscal art. 695 as amended by Ley 8 of 2010); art. 694 par. 2 lists activities whose income is not treated as produced in Panama (invoicing from a Panama office for goods moving only abroad, directing from Panama transactions that are completed abroad, distributing dividends out of income not produced in Panama).
Who it applies to
- Applies to every taxpayer, natural or legal, national or foreign (art. 694 definition of contribuyente); no application, visa status or registration is needed to have foreign-source income left out of the base.
- Foreign-source income is reported on line 18 of the DGI natural-person return, citing par. 2 of art. 694 of the Código Fiscal and special laws.
Exclusions
- Income from work or services performed in Panama, Panama-located assets and Panama business activity is Panama-source and taxable.
- Persons domiciled abroad who receive payments for services that benefit persons in Panama and affect Panama-source income are subject to withholding on 50% of the amount remitted under art. 694 lit. e as amended by Ley 8 of 2010, unless they register as taxpayers.
- Costs and expenses attributable to foreign-source income are not deductible against taxable income.
Tax residence
no residency test is recorded.
Visas
The territorial base applies regardless of visa or residence permit type; it is a feature of the income tax, not of an immigration route.
Other taxes
Social security (CSS) and educational insurance are charged on salary by separate tariffs set out in the DGI instructivo (educational insurance tariff 2.75% of the base for employees per the instructivo).
Checked against official sources on , some details partly verifiedChange log
Standard rules
Panama personal income tax (ordinary context)
Territorial
Details
- On: Net taxable income produced in Panama (territorial)
- Who: Natural persons, resident or not
- Limit: PAB 11k/yr ≈ $11k
Natural persons pay income tax on Panama-source net taxable income at 0% up to B/.11,000, 15% on the excess up to B/.50,000, and B/.5,850 plus 25% above B/.50,000 (art. 700 as set by Ley 8 of 2010).
Taxed on
Net taxable income produced in Panama (territorial); foreign-source income is subtracted before the tariff is applied.
Who it applies to
- Natural persons, resident or not, with Panama-source income file a sworn return within three months after the end of the fiscal year (DGI instructivo).
Exclusions
- Foreign-source income is not part of the taxable base.
Limits
- PAB 11,000 a year (≈ $11,000) · Net taxable income up to this amount is taxed at 0% (art. 700 as amended by Ley 8 of 2010); rates are as published in 2010 and not re-verified against later amendments.
- PAB 50,000 a year (≈ $50,000) · Above this net taxable income the tax is B/.5,850 on the first B/.50,000 plus 25% of the excess; 15% applies between B/.11,000 and B/.50,000.
Visas
No visa-based variation in the ordinary income tax.
Other taxes
CSS social-security and educational-insurance contributions apply to salaries.
Checked against official sources on , some details partly verifiedChange log
Checked against official sources on Change log
Panama in pictures
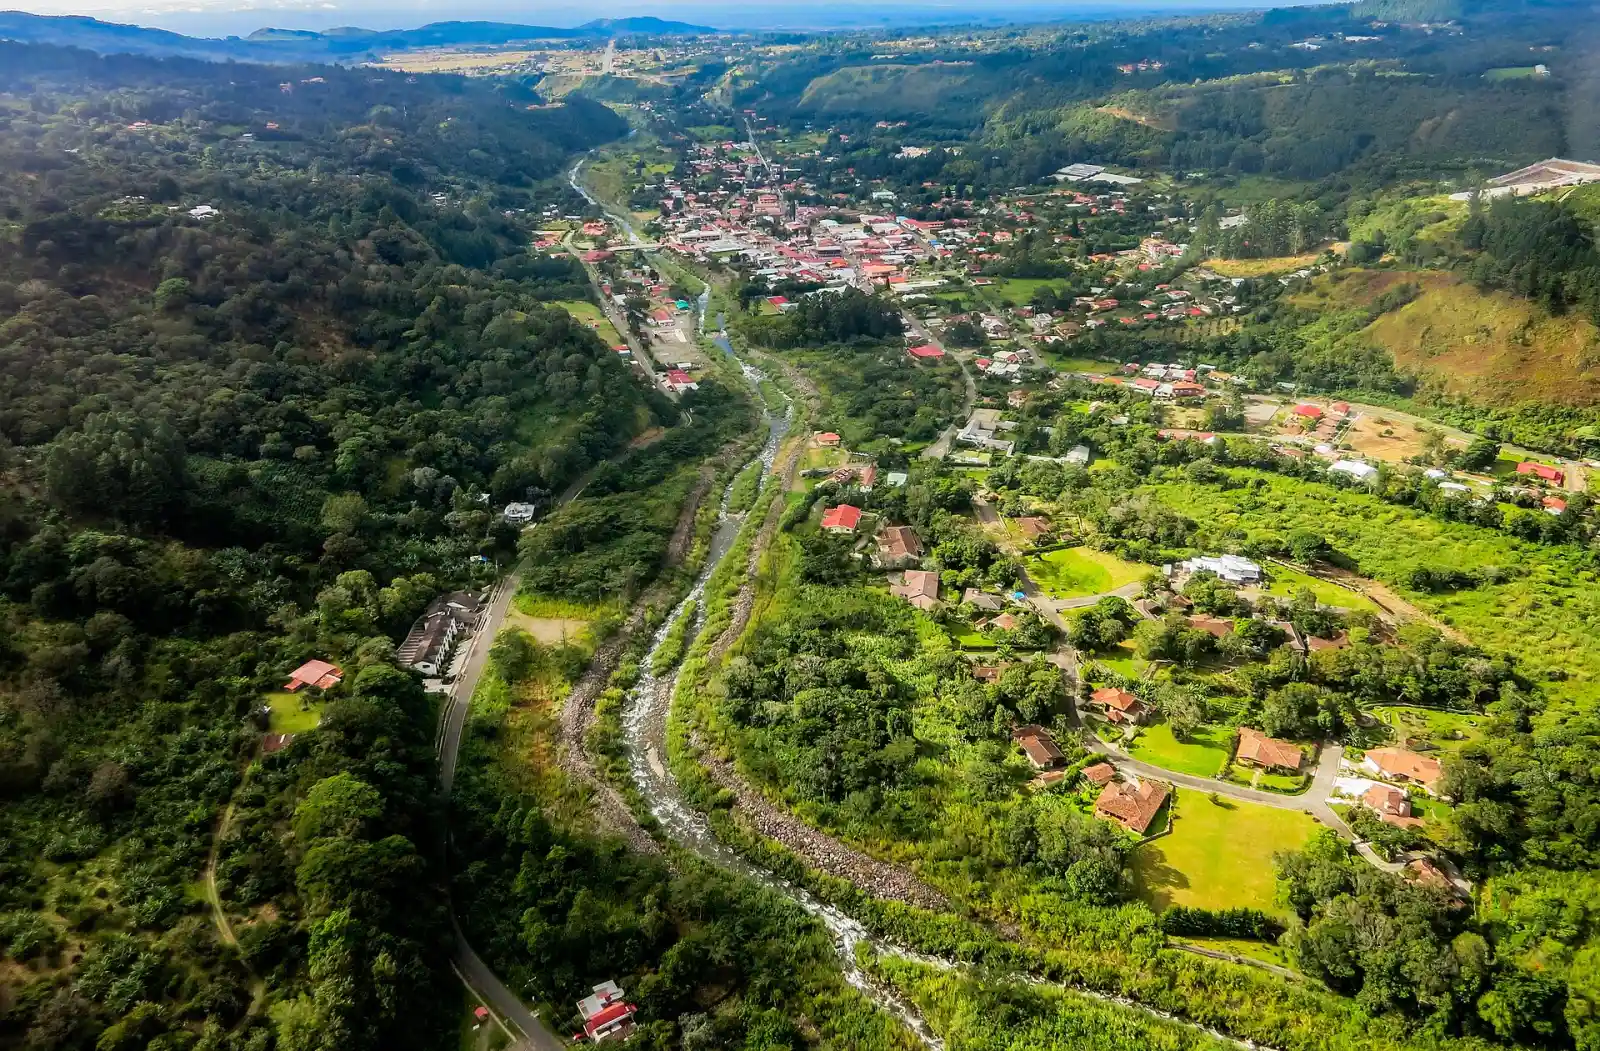
Arriving in Panama: first steps
- Arrange medical insurance where the route requires it
- Keep passport, police and health certificates ready for the application
- For investment routes, keep proof of the investment and present it annually
- For the remote-worker route, carry the employer letter and evidence of foreign-source income
- Check the migration service website for the current nationality list and forms
Questions people ask
What is the Panama digital nomad visa income requirement in 2026?
Panama has 1 nomad or remote-work visa. Remote worker visa asks for an income of at least PAB 36,000 a year (≈ $36,000) and gives a first stay of 9 months that can be renewed.
How much do you need to invest for residency in Panama?
Panama has 3 investor routes. Qualified Investor · Property asks for an investment of at least PAB 300,000 (≈ $300,000). Qualified Investor · Deposit asks for an investment from PAB 500,000 (≈ $500,000). Qualified Investor · Securities asks for an investment of at least PAB 500,000 (≈ $500,000).
Can I retire or live in Panama on my savings or pension?
Panama has 2 retirement or pay-to-stay routes. Retired rentista asks for an income of at least PAB 850 a month (≈ $850) and gives a first stay of 5 years that can be renewed. Pensionado residence asks for an income from PAB 750 a month (≈ $750).
What work visas does Panama offer foreigners?
Panama has 1 work visa. Friendly Nations residence asks for an investment from PAB 200,000 (≈ $200,000) and gives a first stay of 2 years.
Can I join my spouse or partner in Panama?
Yes. Panama has 1 spouse visa. Spouse of a citizen gives a first stay of 2 years.
Does Panama have a special tax regime for new residents?
Yes: Panama territorial income tax (foreign-source income outside the tax base). Panama taxes income produced inside Panama only; the taxable base of a taxpayer is gross income less foreign-source income, exempt income and deductible costs, and the DGI personal return has a separate line for foreign-source income. It is separate from the visa and has its own conditions.
Compare with
≈ USD figures are approximate: daily reference rates from ExchangeRate-API, dated 12 Oct 2026, refreshed when the site is updated.
Ask the AI about Panama AI
An AI assistant answers from the published records on this page and cites them. It can't assess your personal eligibility. Don't include personal details.