Moving to Chile
6 ways to move to Chile in our guide: 1 investor route, 1 pay-to-stay route, 2 work visas, 1 student visa, 1 spouse visa.
No digital nomad visa. Smallest investment: Investor · US$500k, $500k+. Tax for newcomers: Chilean income tax: three years on Chilean-source income only for new residents (Ley de la Renta art. 3), Tax relief. Checked against official sources on .
Chile offers a few clear temporary residence routes, each tied to a different purpose: investing or managing a foreign-backed company, taking up paid work with a Chilean employer, or studying at a recognised institution. Visas and tax are handled separately.
Investing · 1

Investor · US$500k
Investment needed: $500k+
Retire or live on savings · 1

Retiree / rentista
Work · 2

Paid work residence
First stay: 2 yrs
Investor's staff residence
Student · 1

Student residence
Details
Residencia Temporal — Estudiantes de establecimientos reconocidos (subcategoría 3)
- Proof of enrolment and of financial support is required
- Scholarship holders present the scholarship certificate
- A passport valid one year is required
Temporary residence for students of recognised institutions. 1
Requirements
- Proof of enrolment and of financial support is required. 1
- Scholarship holders present the scholarship certificate. 1
- A passport valid one year is required. 1
- A criminal-record certificate (over 18) is required. 1
Stay
- Temporary residence; the migration service page does not state its length.
- Renewable, subject to the conditions in force at renewal.
Work
Holders may do paid work up to 30 hours per week without extra authorisation.
Family
Dependants can apply under the dependant status of the temporary residence.
Checked against official sources on Change log
Spouse visas · 1

For people married to, or in a partnership with, a citizen or permanent resident.
Spouse visa
Free movement and visa-free stays · 1
Tax
The records for Chile do not describe how newcomers are taxed or how foreign-source income is treated.
Special regime
Chilean income tax: three years on Chilean-source income only for new residents (Ley de la Renta art. 3)
Tax relief
Details
- On: Chilean-source income during the first three years
- Who: Foreign national who establishes domicile or residence in Chile
A foreigner who sets up domicile or residence in Chile pays tax only on Chilean-source income during the first three years from entry; after that, worldwide income is taxed unless the Regional Director grants an extension in qualified cases.
Taxed on
Chilean-source income during the first three years; worldwide income afterwards.
Who it applies to
- Foreign national who establishes domicile or residence in Chile.
- The three years count from the date of entry into Chile.
Exclusions
- Chilean-source income remains taxable from the start.
- Chilean nationals who recover domicile or residence in Chile are not covered.
Days in the country
- More than 183 days in any period of 12 consecutive months · Presence in Chile, continuous or not, of more than 183 days makes the person resident from the 184th day.
Tax residence
A person present in Chile for more than 183 days, continuous or not, within any 12 consecutive months is resident from the 184th day; domicile is a separate test. The three-year period runs from entry into Chile whether or not residence or domicile has yet been established.
Visas
The rule depends on domicile or residence, not on the type of temporary residence.
Other taxes
Extension of the three-year period must be requested from the Regional Director.
Checked against official sources on Change log
Special regime
Chile three-year Chilean-source-only taxation for foreigners who settle
Tax relief
Details
- On: Chilean-source income only during the period
- Who: Foreign national who constitutes domicile or residence in Chile
A foreigner who establishes domicile or residence in Chile is taxed only on Chilean-source income for the first three years counted from entry into Chile; the Regional Director may extend that period in qualified cases, and afterwards worldwide income is taxed.
Taxed on
Chilean-source income only during the period (Global Complementario or Impuesto Único de Segunda Categoría on income received from entry); worldwide income afterwards.
Who it applies to
- Foreign national who constitutes domicile or residence in Chile (art. 3 inciso 2 of the Ley sobre Impuesto a la Renta, as quoted in SII Oficio 2123 of 2018).
- The three years run from the date of entry into Chile, not from the date residence is acquired (SII Circular 63 of 2021 example: entry 1 March year X0, worldwide taxation from 2 March year X3).
- Extension beyond three years is a discretionary decision of the Director Regional in qualified cases.
Exclusions
- Chilean nationals who recover domicile or residence are not covered (SII Oficio 2123 of 2018).
- Before the 184th day of presence the person is a non-resident subject to impuesto adicional on Chilean-source income; after residence begins the Global Complementario or Único de Segunda Categoría applies.
Days in the country
- More than 183 days in any period of 12 consecutive months · Presence in Chile, continuous or not, of more than 183 days makes the person resident from the 184th day; entry and exit days count, transit days between two foreign points do not
Tax residence
Tax residence is purely objective (days present) since Ley 21.210 (2020); domicile is a separate concept assessed on intention and facts.
Visas
The rule depends on becoming domiciled or resident for tax purposes and on the entry date, not on a particular visa category.
Checked against official sources on Change log
Standard rules
Chile personal income tax: Second Category (employment) scale 0-40% and global complementary tax
Worldwide income
Details
- On: Worldwide income of residents after the three-year foreigner period
- Who: Domiciled in or resident in Chile (more than 183 days in any 12-month period)
- Limit: CLP 974k/mo ≈ $1,000
Salaried income above 13.5 UTM a month pays Impuesto Único de Segunda Categoría on a scale of 4%, 8%, 13.5%, 23%, 30.4%, 35% and 40% (above 310 UTM); after the three-year period (or any extension) a person who is domiciled or resident in Chile is taxed on income from any source, and a person present more than 183 days in any 12 consecutive months is resident from the 184th day.
Taxed on
Worldwide income of residents after the three-year foreigner period; Chilean-source income of non-residents (impuesto adicional, 35%). Employment income is taxed monthly on the taxable salary after mandatory pension, health and unemployment contributions, at the UTM-based scale; other income and annual reconciliation use the same scale in annual tax units (UTA = 12 UTM) under the Global Complementario tax.
Who it applies to
- Domiciled in or resident in Chile (more than 183 days in any 12-month period).
- The Second Category scale applies to income from dependent employment and pensions, withheld monthly by the employer.
Exclusions
- Foreigners within their first three years from entry pay only on Chilean-source income.
- Non-residents pay additional tax at a flat 35% on Chilean-source income instead of the scale.
Limits
- CLP 974,038.5 a month (≈ $1,000) · Exempt band: monthly taxable salary up to 13.5 UTM (CLP 974,038.50 (≈ $1,000) in October 2026) pays no Second Category tax.
- CLP 2,164,530 a month (≈ $2,220) · 4% band: monthly taxable income above CLP 974,038.50 (≈ $1,000) up to this amount; tax = income x 0.04 minus CLP 38,961.54 (≈ $40) (October 2026).
- CLP 3,607,550 a month (≈ $3,690) · 8% band: income above CLP 2,164,530 (≈ $2,220) up to this amount; tax = income x 0.08 minus CLP 125,542.74 (≈ $130).
- CLP 5,050,570 a month (≈ $5,170) · 13.5% band: income above CLP 3,607,550 (≈ $3,690) up to this amount; tax = income x 0.135 minus CLP 323,957.99 (≈ $330).
- CLP 6,493,590 a month (≈ $6,650) · 23% band: income above CLP 5,050,570 (≈ $5,170) up to this amount; tax = income x 0.23 minus CLP 803,762.14 (≈ $820).
- CLP 8,658,120 a month (≈ $8,860) · 30.4% band: income above CLP 6,493,590 (≈ $6,650) up to this amount; tax = income x 0.304 minus CLP 1,284,287.80 (≈ $1,310).
- CLP 22,366,810 a month (≈ $22,900) · 35% band: income above CLP 8,658,120 (≈ $8,860) up to this amount; tax = income x 0.35 minus CLP 1,682,561.32 (≈ $1,720); above this amount the rate is 40% (income x 0.40 minus CLP 2,800,901.82 (≈ $2,870)).
- CLP 72,151 a month (≈ $74) · Value of one UTM (monthly tax unit) for October 2026, set by the Internal Revenue Service; all bands are multiples of the UTM (13.5, 30, 50, 70, 90, 120 and 310 UTM) and move every month.
Days in the country
- More than 183 days in any period of 12 consecutive months · Physical presence in Chile, continuous or not
Tax residence
Resident from the 184th day of presence in any 12 consecutive months; domicile also creates residence. The three-year foreigner period applies from entry and can be extended on request.
Visas
Tax residence follows presence and domicile, not visa type.
Other taxes
Employee contributions (employer withholds): 10% of taxable pay to the pension fund plus the AFP commission, 7% health contribution, and 0.6% unemployment insurance on indefinite contracts (employer pays 2.4%). Taxable pay is capped at 90.0 UF a month for pension and health contributions and 135.2 UF a month for unemployment insurance from February 2026 payments. Contributions reduce the taxable base for the Second Category tax.
Checked against official sources on Change log
Checked against official sources on Change log
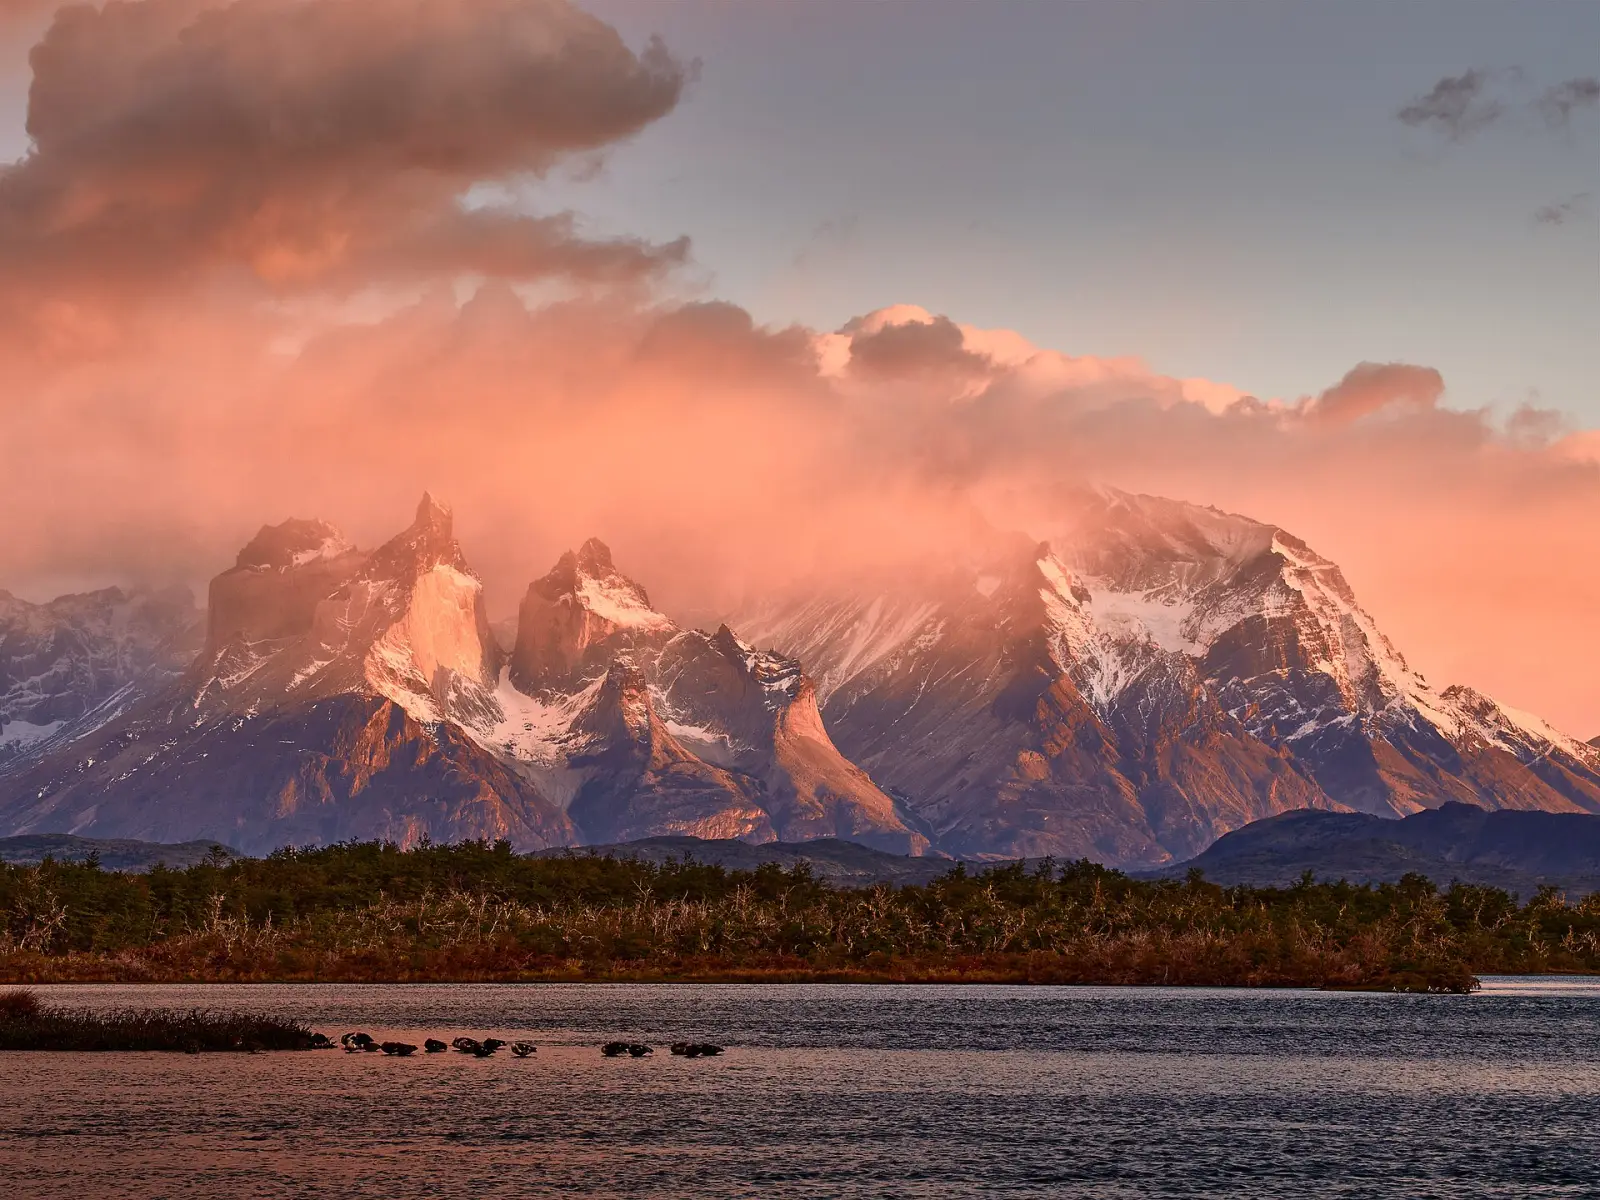
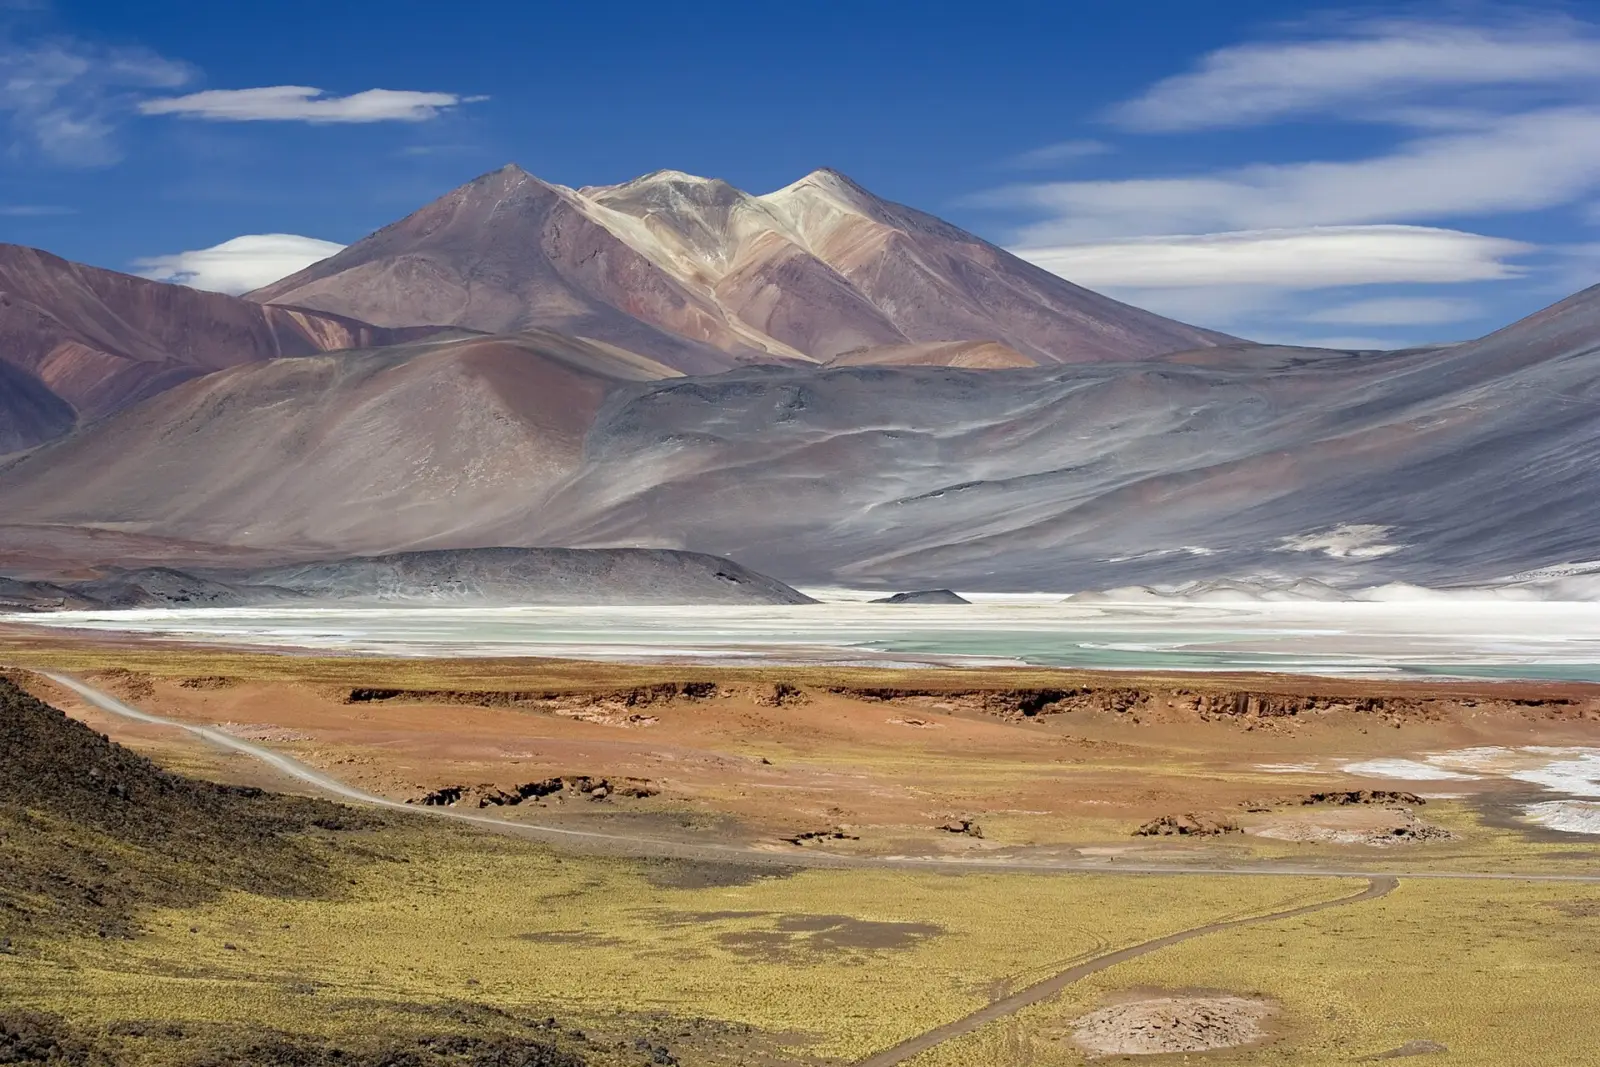
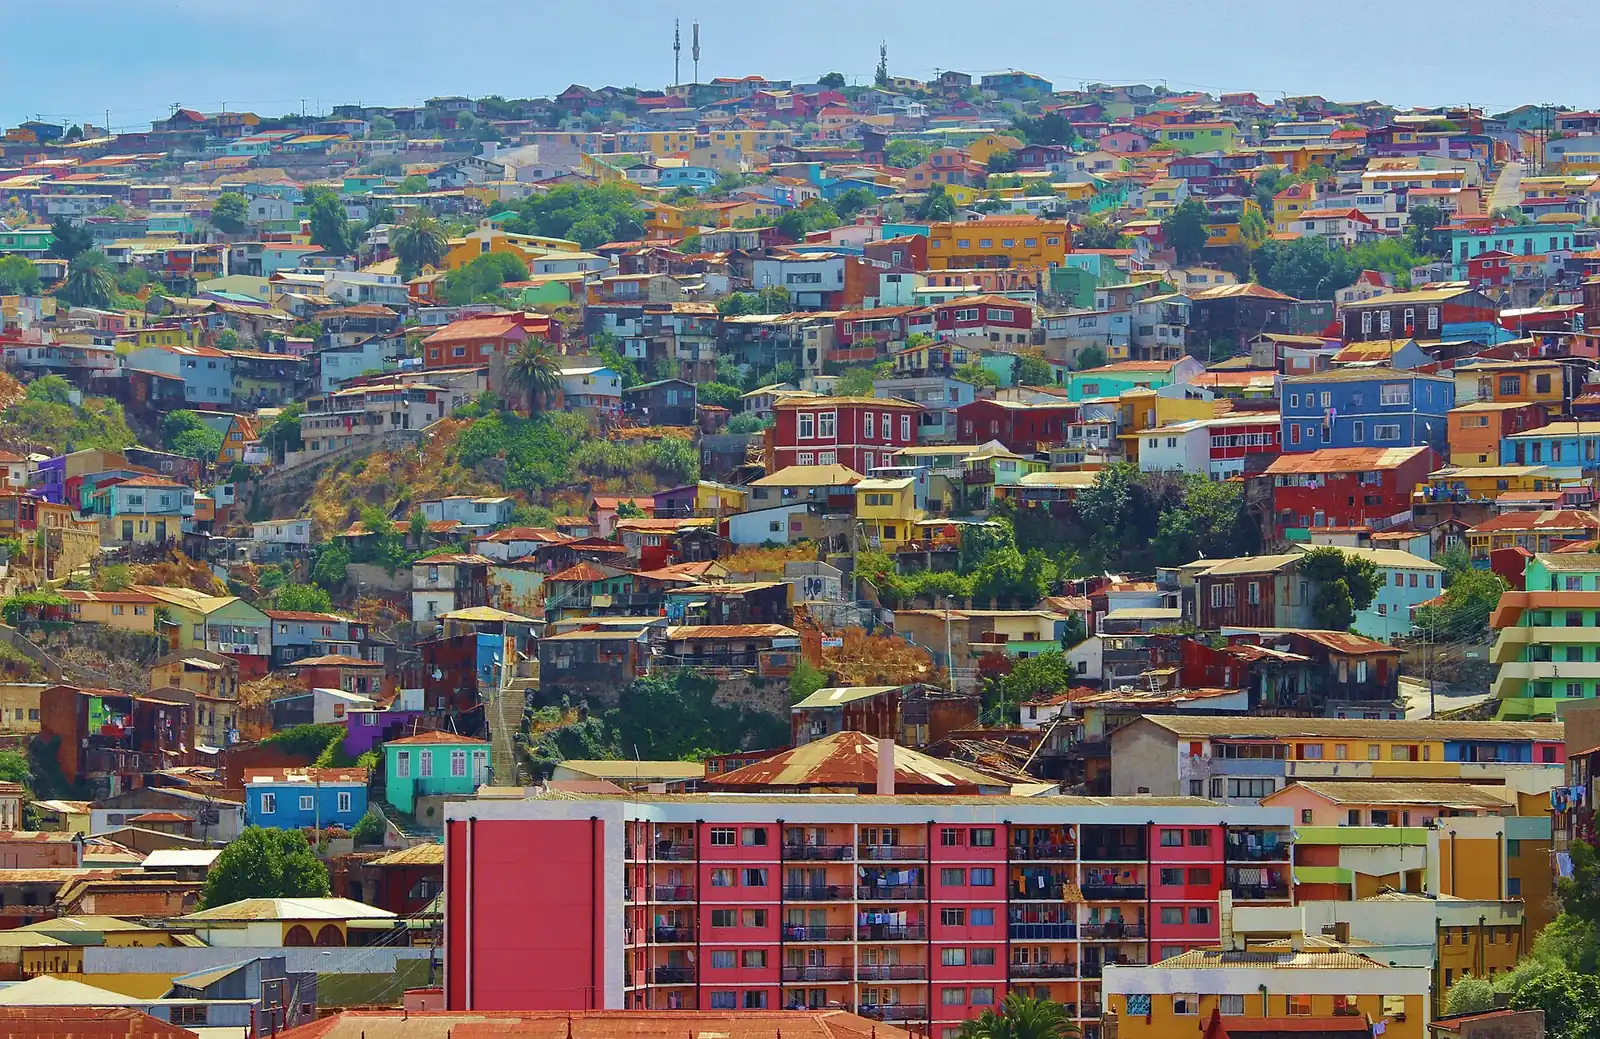
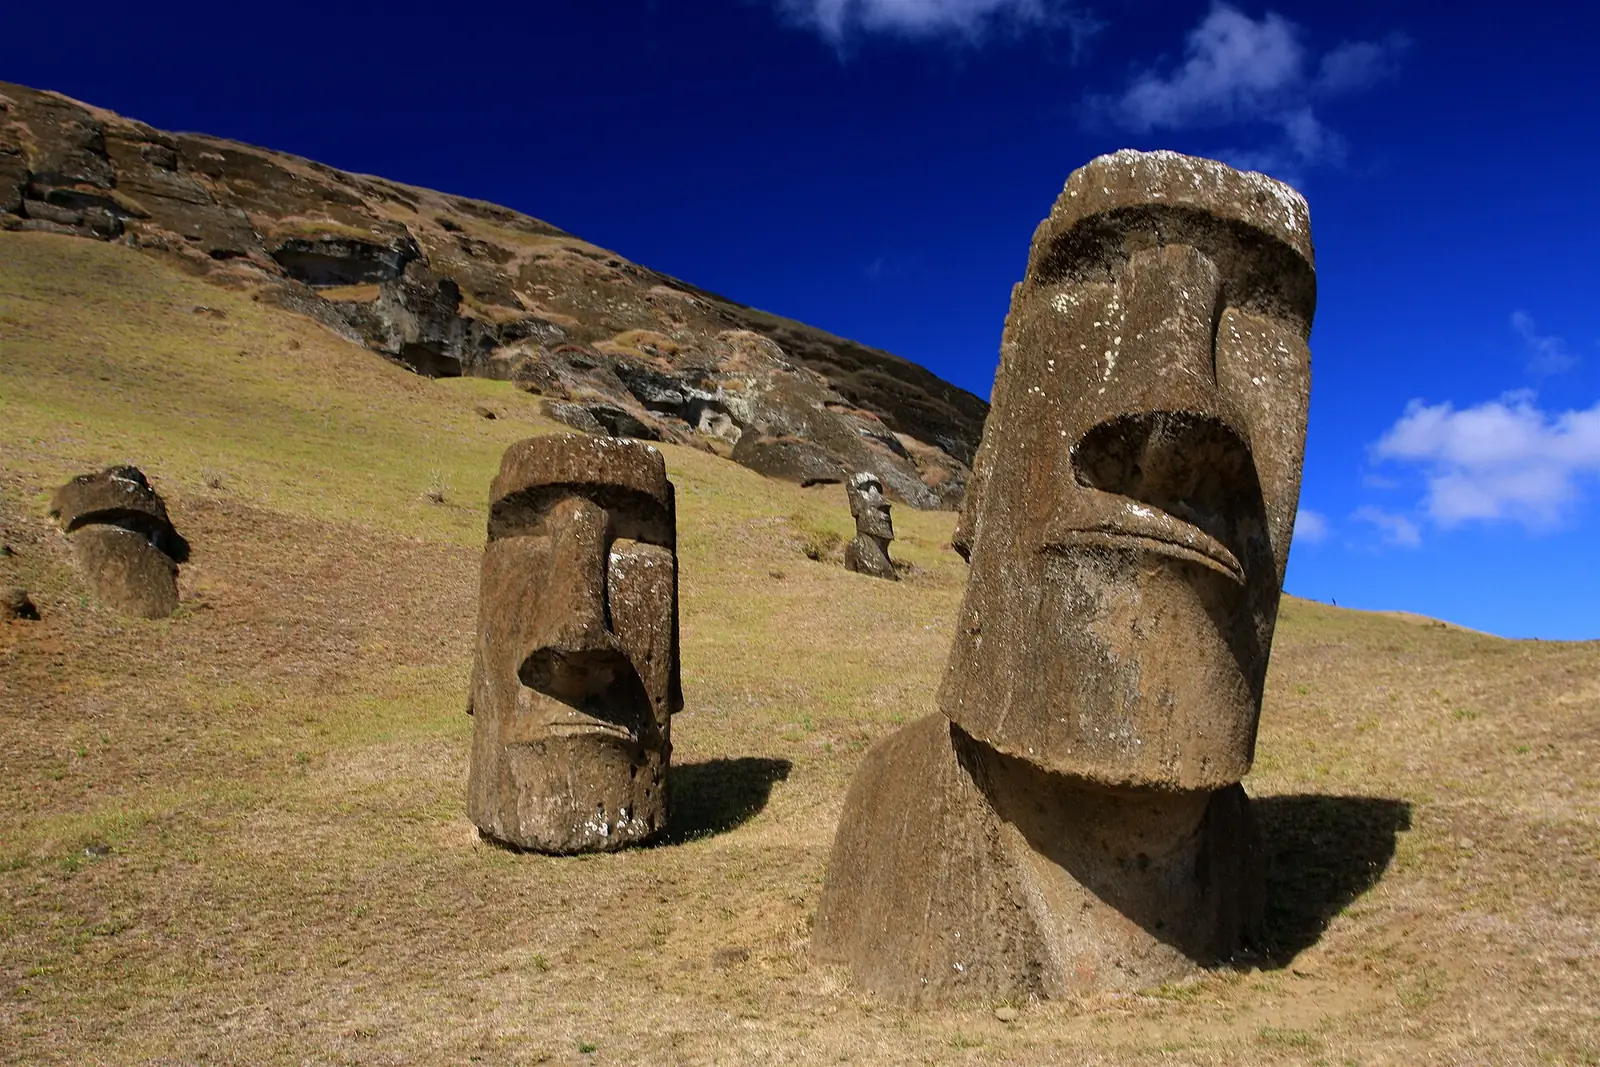
Chile in pictures
Arriving in Chile: first steps
- Apply for the relevant SERMIG temporary-residence subcategory, in most cases from abroad.
- For the investor-related route, include the InvestChile sponsorship letter and investment details; renewals need project-progress evidence.
- For paid work, gather employer and job evidence under the current category checklist.
- For study, secure enrolment or acceptance from a recognised establishment and meet the current subcategory documentation requirements.
Questions people ask
How much do you need to invest for residency in Chile?
Chile has 1 investor route. Investor · US$500k asks for an investment of at least $500,000.
Can I retire or live in Chile on my savings or pension?
Chile has 1 retirement or pay-to-stay route. It is Retiree / rentista.
What work visas does Chile offer foreigners?
Chile has 2 work visas. Paid work residence gives a first stay of 2 years that can be renewed. There is also Investor's staff residence.
How do I get a student visa for Chile?
Chile has 1 student visa. It is Student residence.
Can I join my spouse or partner in Chile?
Yes. Chile has 1 spouse visa. It is Spouse visa.
Does Chile have a special tax regime for new residents?
Yes: Chilean income tax: three years on Chilean-source income only for new residents (Ley de la Renta art. 3). A foreigner who sets up domicile or residence in Chile pays tax only on Chilean-source income during the first three years from entry; after that, worldwide income is taxed unless the Regional Director grants an extension in qualified cases. It is separate from the visa and has its own conditions.
Compare with
≈ USD figures are approximate: daily reference rates from ExchangeRate-API, dated 12 Oct 2026, refreshed when the site is updated.
Ask the AI about Chile AI
An AI assistant answers from the published records on this page and cites them. It can't assess your personal eligibility. Don't include personal details.
Sources (1)
Official sources
- Residencia Temporal — Estudiantes (subcategoría 3) · Servicio Nacional de Migraciones · checked 2026-10-12