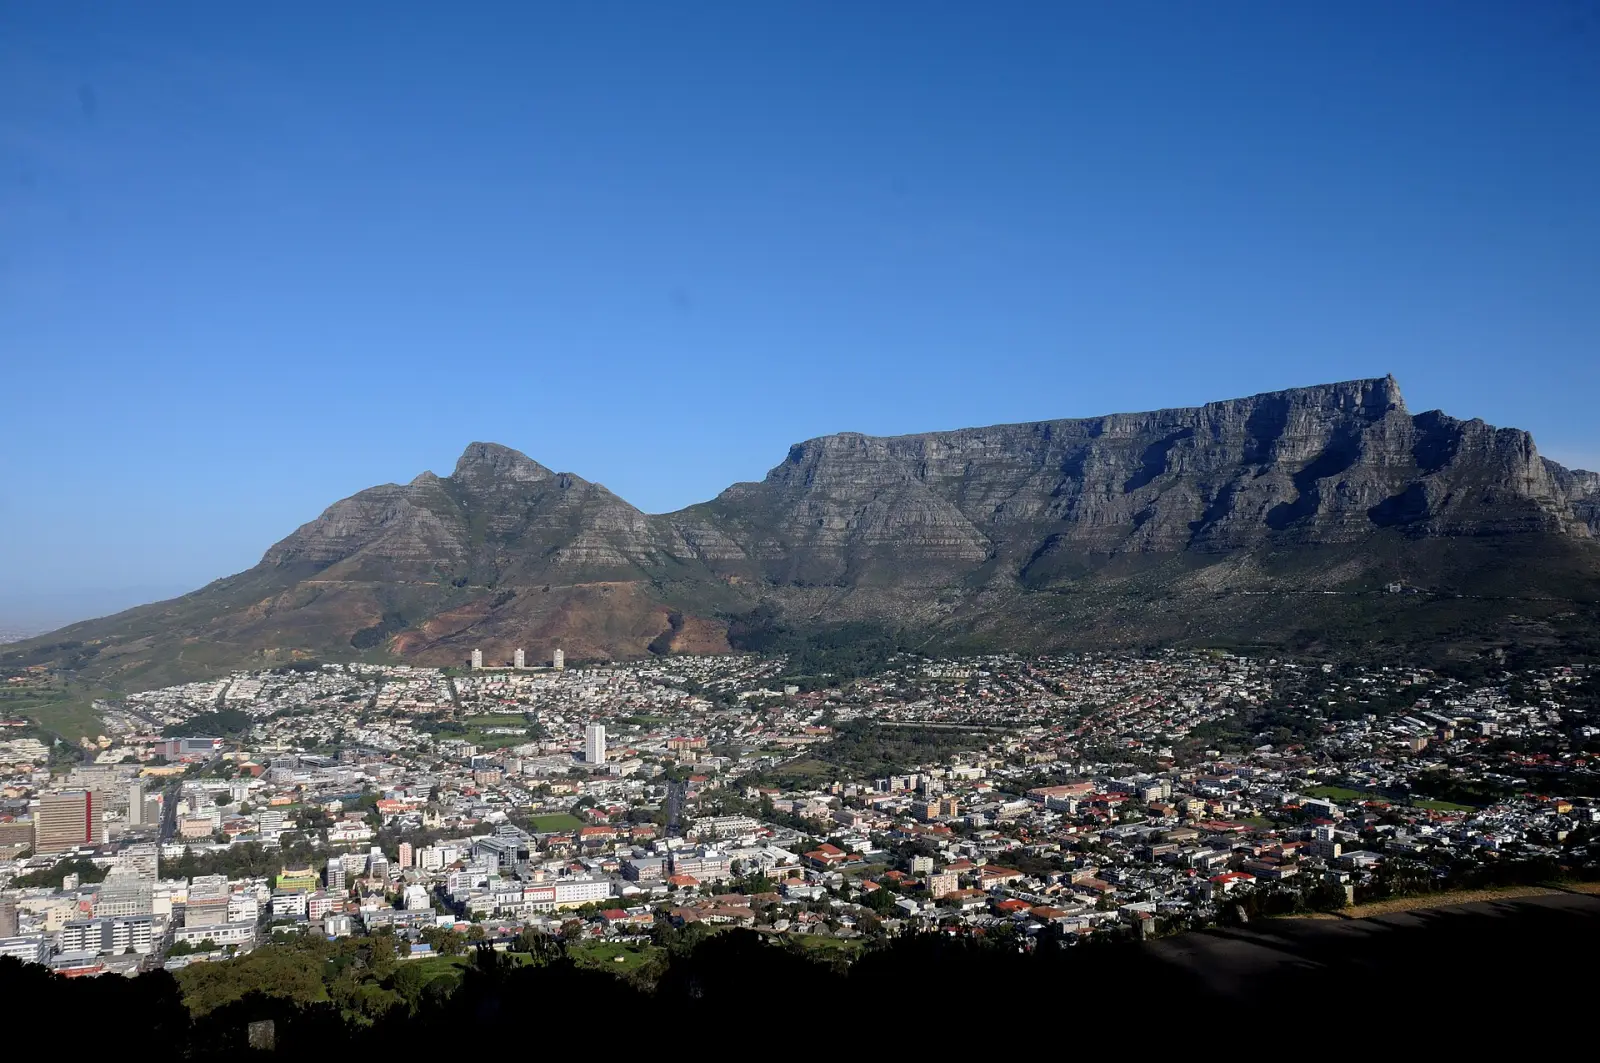
Moving to South Africa
6 ways to move to South Africa in our guide: 1 nomad / remote-work visa, 2 pay-to-stay routes, 1 business / startup route, 1 work visa, 1 spouse visa.
Remote workers: Remote Work Visa, ZAR 651k+ a year ≈ $39k. Smallest investment: PR · Business, ZAR 5M+ ≈ $302k. Checked against official sources on .
South Africa offers a range of routes for foreigners, from work and business to retirement and remote work. Visas and tax are separate.
Nomad / Remote work · 1

Remote Work Visa
Income needed: ZAR 651k+ a year ≈ $39k
Retire or live on savings · 2

Business / Startup · 1

PR · Business
Investment needed: ZAR 5M+ ≈ $302k
Work · 1

PR · Critical skills
Details
Permanent residence on critical skills grounds (Immigration Act s27(b))
- Work: Yes
- The applicant does not need to hold a temporary visa at the time of application
- The permanent residence permit fee is ZAR 1,520 (≈ $92)
Permanent residence for a foreigner with critical skills and qualifications. 1 2 3
What you must show and pay
- A fee of ZAR 1,520 (≈ $92) · Permanent residence permit fee. 2
Requirements
- The applicant has critical skills and qualifications under section 27(b) and Regulation 24(3). 3
- The applicant does not need to hold a temporary visa at the time of application. 1
- The permanent residence permit fee is ZAR 1,520 (≈ $92). 2
- Apply on form BI-947 with a police clearance certificate and a medical report. 3
Stay
- Permanent residence.
Work
Full work rights as a permanent resident.
Family
The permit may extend to immediate family members determined by the Director-General or as prescribed.
First checked against official sources on Change log
Spouse visas · 1

For people married to, or in a partnership with, a citizen or permanent resident.
Spouse of a citizen
Tax
South African tax residents are taxed on worldwide income, while non-residents are taxed only on South African-source income. If you are a resident employee working outside South Africa, you may exempt a portion of your foreign employment remuneration when you meet both day tests; the rest is taxed at normal rates.
Standard rules
South Africa residents: worldwide income taxed at 18-45% (2027 tax year), ordinarily resident and physical presence tests
45% tax
Details
- On: Taxable income of a resident (worldwide)
- Limit: ZAR 245k/yr ≈ $15k
South African tax residents, whether ordinarily resident or meeting the physical presence test, are taxed on worldwide income at 18% to 45% for the 2027 tax year (1 March 2026 to 28 February 2027); non-residents are taxed only on South African-source income.
Taxed on
Taxable income of a resident (worldwide); South African-source income of a non-resident. 2027 tax year scale: up to ZAR 245,100 (≈ $14,800) 18%; to 383,100 ZAR (≈ $23,200) 44,118 plus 26% of the excess over 245,100; to 530,200 ZAR (≈ $32,000) 79,998 plus 31% over 383,100; to 695,800 ZAR (≈ $42,100) 125,599 plus 36% over 530,200; to 887,000 ZAR (≈ $53,600) 185,215 plus 39% over 695,800; to 1,878,600 ZAR (≈ $114,000) 259,783 plus 41% over 887,000; above 1,878,600 ZAR (≈ $114,000) 666,339 plus 45% over 1,878,600. Primary rebate ZAR 17,820 (≈ $1,080) (secondary ZAR 9,765 (≈ $590) aged 65+, tertiary ZAR 3,249 (≈ $200) aged 75+). The 2026 tax year scale was unchanged from 2025.
Who it applies to
- Resident: ordinarily resident in South Africa, or, if not ordinarily resident, meeting the physical presence test.
- Physical presence test: more than 91 days in the tax year, more than 91 days in each of the 5 preceding tax years, and more than 915 days in total over those 5 years; the person becomes resident from the first day of the sixth year in which all three are met.
- A person treated as exclusively resident of another country under a tax treaty is not a resident.
- A physical-presence resident who is outside South Africa for at least 330 continuous full days ceases to be resident from the day of departure.
Exclusions
- Interest earned by a non-resident not present for more than 183 days in the 12 months before accrual is exempt from income tax.
Limits
- ZAR 245,100 a year (≈ $14,800) · 18% band ends; 26% applies up to ZAR 383,100 (≈ $23,200) (2027 tax year)
- ZAR 1,878,600 a year (≈ $114,000) · 45% applies to taxable income above this amount (2027 tax year)
- ZAR 99,000 a year (≈ $5,980) · Tax threshold under age 65, 2027 tax year (1 March 2026 to 28 February 2027)
- ZAR 17,820 a year (≈ $1,080) · Primary rebate, 2027 tax year
Days in the country
- More than 91 days in tax year and each of the 5 preceding tax years · Physical presence test: more than 91 days in the current year and in each of the five preceding years.
- More than 915 days in 5 tax years preceding the current year · Physical presence test: more than 915 days in total over the five preceding years.
- At least 330 days in continuous period outside South Africa · A physical-presence resident outside the country for at least 330 continuous full days ceases to be resident from the day of departure.
Tax residence
The tax year runs 1 March to 28 February. The physical presence test applies only to a person who is not ordinarily resident; ordinary residence depends on the place a person returns to from absences as home.
Visas
Tax residence is independent of immigration status; the visa does not set the tax regime.
Other taxes
Capital gains: inclusion gives a maximum effective rate of 18% for individuals with an annual exclusion of ZAR 50,000 (≈ $3,020). Dividends tax is 20%. Interest from South African sources is exempt up to ZAR 23,800 (≈ $1,440) a year (under 65).
Checked against official sources on Change log
Special regime
Foreign employment income exemption (Income Tax Act s10(1)(o)(ii))
Tax relief
Details
- On: Foreign-source employment remuneration of a resident employee
- Limit: ZAR 1.3M/yr ≈ $76k
A South African tax resident employee may exempt the first ZAR 1,250,000 (≈ $75,600) of remuneration for services rendered outside South Africa when both day tests are met; the excess is taxed at the normal rates.
Taxed on
Foreign-source employment remuneration of a resident employee
Who it applies to
- South African tax resident employee rendering services outside South Africa for an employer, South African or foreign.
- Outside South Africa for more than 183 full days in any 12-month period, including a continuous period of more than 60 full days.
Exclusions
- Public-sector employees and holders of public office appointed under an Act of Parliament.
- Independent contractor income, which is not remuneration.
- Non-residents.
Limits
- ZAR 1,250,000 a year (≈ $75,600) · Maximum exempt foreign employment remuneration, for years of assessment from 1 March 2020.
Days in the country
- More than 183 days in Any 12-month period · Full days outside South Africa required for the exemption.
- More than 60 days in Continuous period within the same 12 months · Continuous full days outside South Africa required for the exemption.
Tax residence
The employee must stay South African tax resident; the exemption does not apply to non-residents.
Visas
Applies to a resident who works abroad; a Remote Work Visa holder who is employed by a foreign company and is tax resident in South Africa does not fall under this exemption because the services are rendered inside South Africa.
Other taxes
Income above ZAR 1,250,000 (≈ $75,600) may be taxed in both countries unless a tax treaty gives sole taxing rights to one of them.
Checked against official sources on Change log
Checked against official sources on Change log
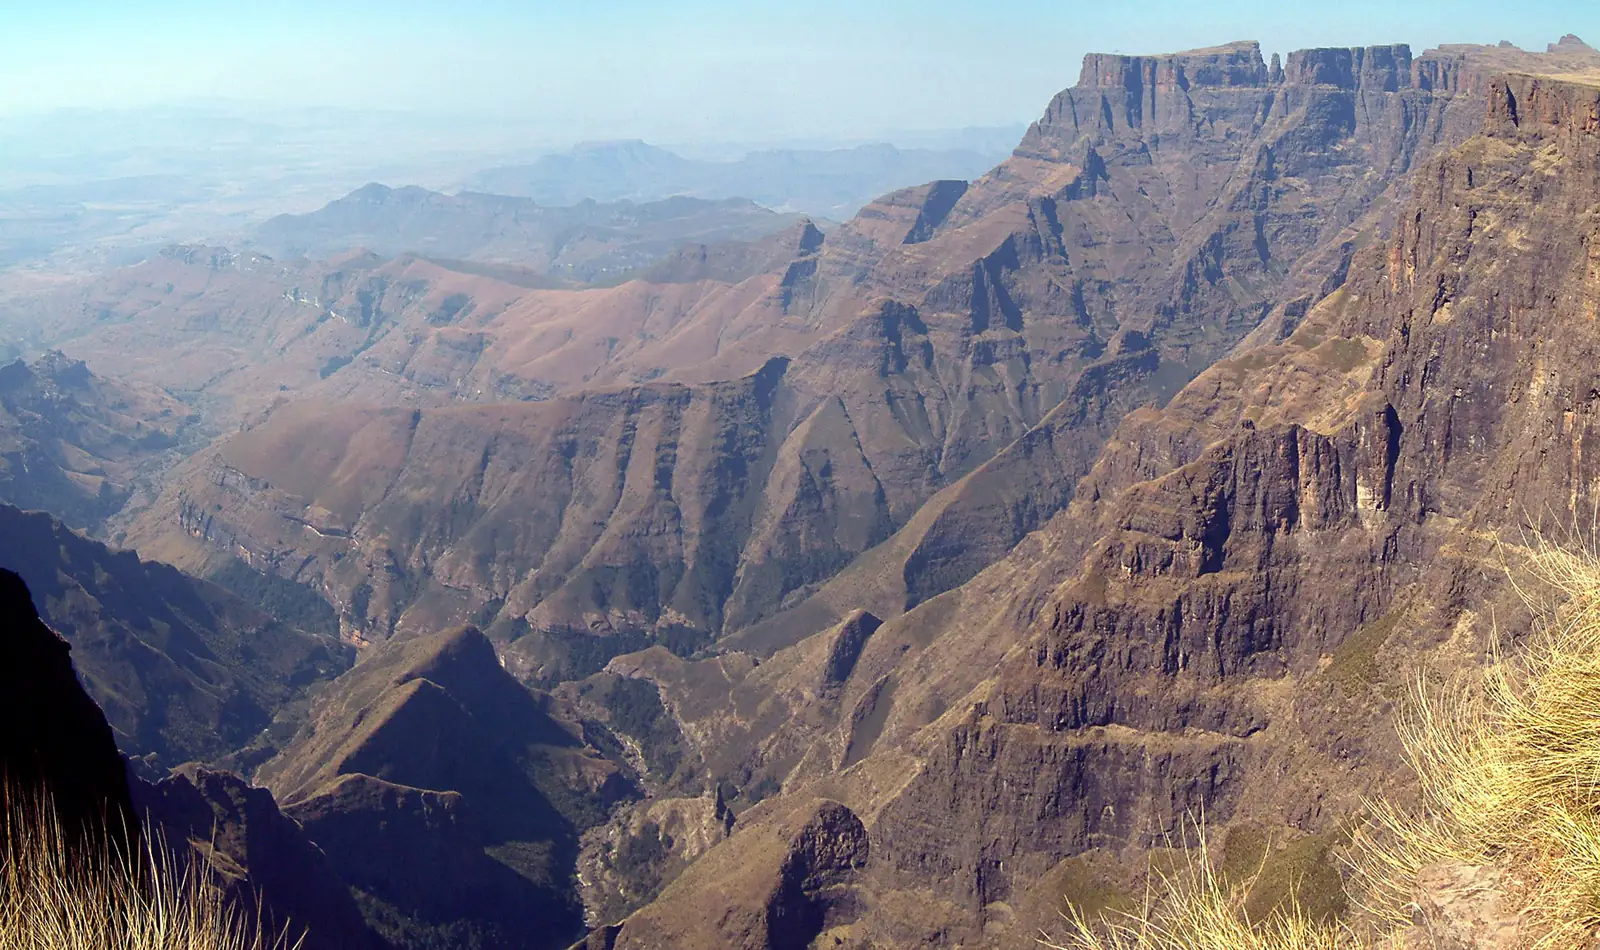
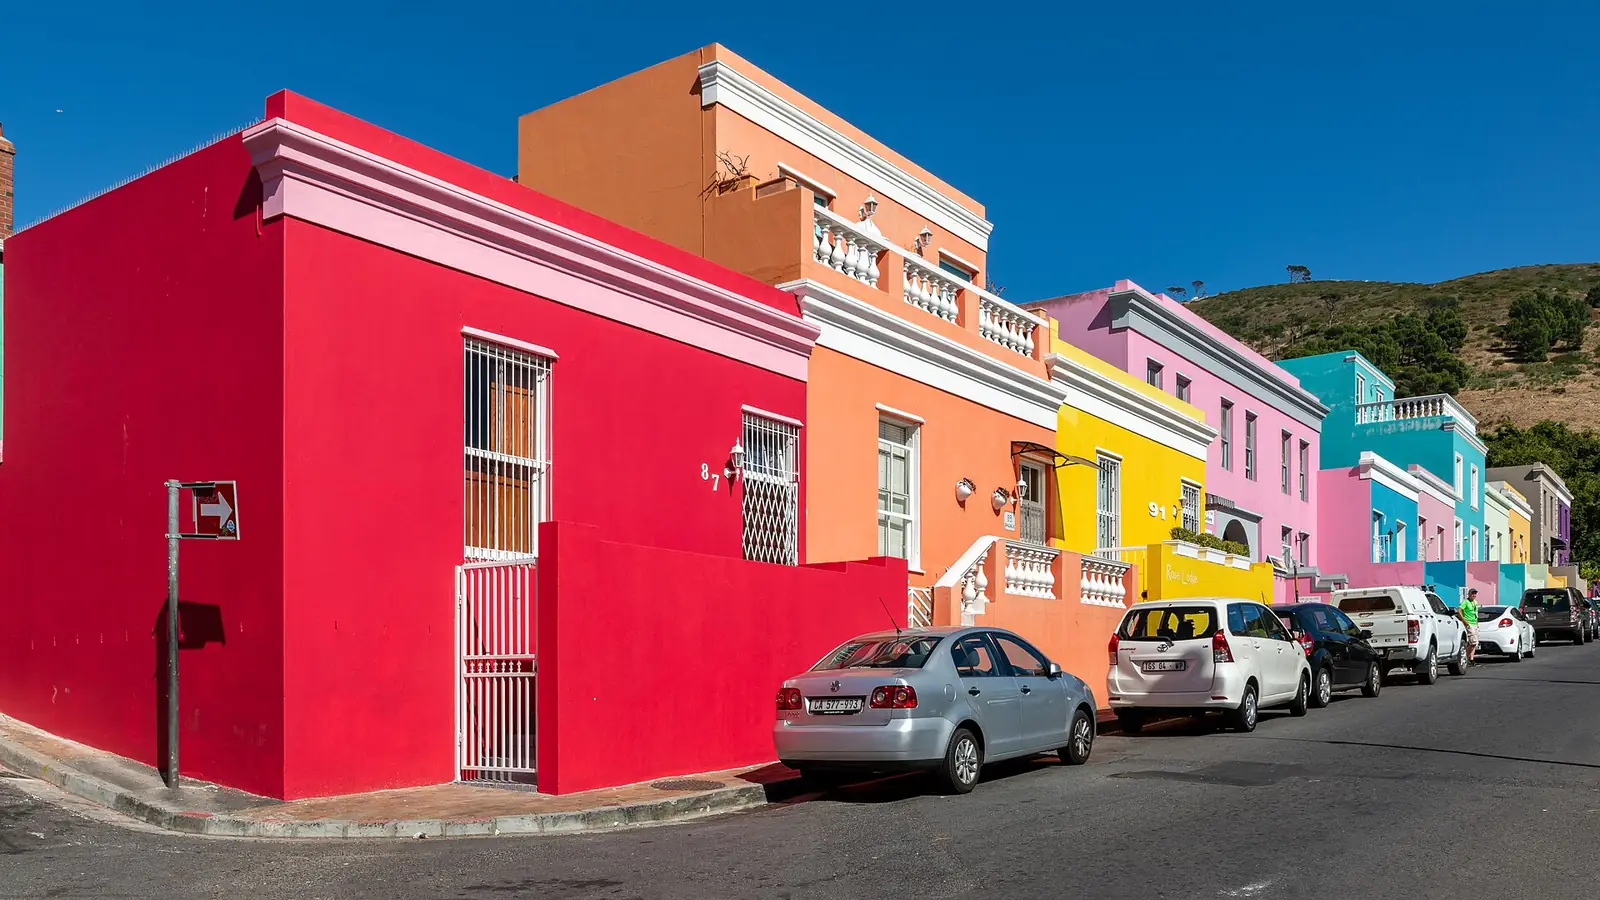
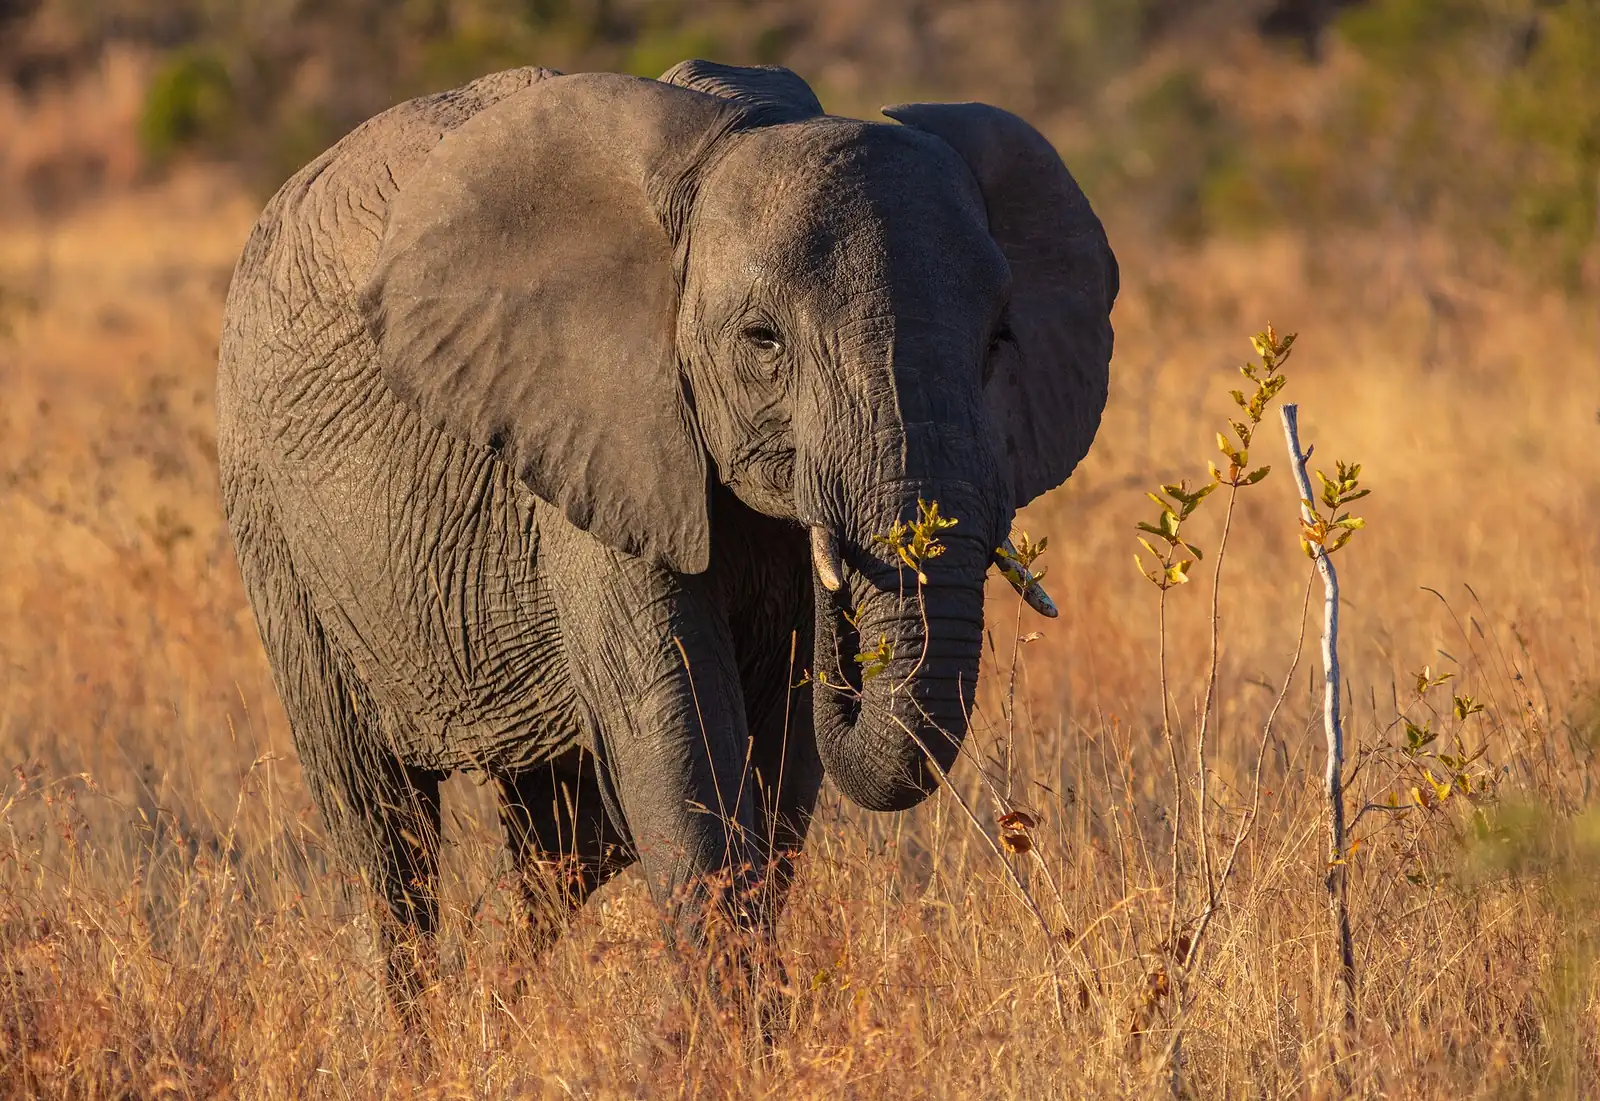
South Africa in pictures
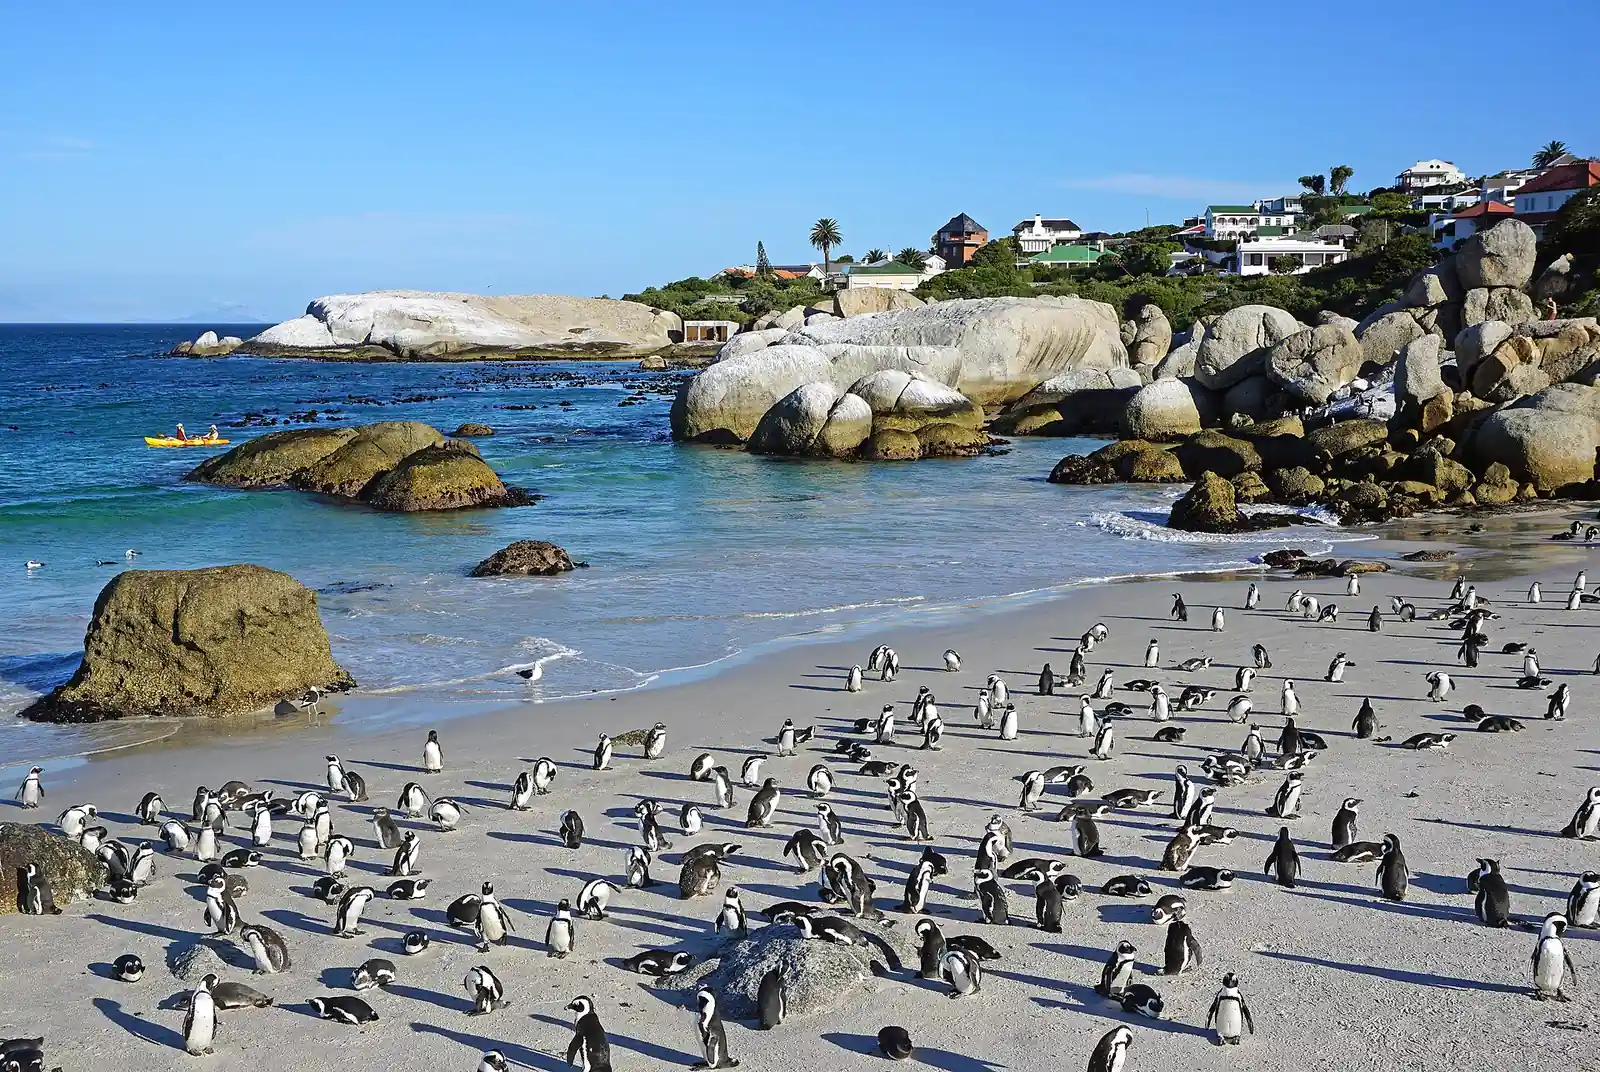
Shorter stays · 9
Retire or live on savings
Retired Person Visa
Income needed: ZAR 37k+ a month ≈ $2,240
Business / Startup
Business visa
Investment needed: ZAR 5M+ ≈ $302k
Not yet in force
Start-up visa (proposed)
Work
Corporate visa
First stay: 3 yrs
Work
Critical Skills visa
First stay: 5 yrs
Work
General Work visa
First stay: 5 yrs
Work
Intra-company transfer
First stay: 4 yrs
Student
Exchange visa
First stay: 1 yr
Student
Study visa
Path to permanent residence · 4
- PR after 5 years · Permanent residence after five years on a work visa (Immigration Act s26(a))
- PR · Permanent residence as a retired person (Immigration Act s27(e))
- PR · Permanent residence on business grounds (Immigration Act s27(c))
- PR · Permanent residence on critical skills grounds (Immigration Act s27(b))
Arriving in South Africa: first steps
- Arrange medical cover with a South African registered medical scheme if your visa requires it.
- Provide a South African address for your application and registration.
- Open a South African bank account for local transactions and proof of funds.
- Register with SARS for tax if you become a resident or earn South African-source income.
- Submit your visa application with all required forms, fees and supporting documents.
Questions people ask
What is the South Africa digital nomad visa income requirement in 2026?
South Africa has 1 nomad or remote-work visa. Remote Work Visa asks for an income of at least ZAR 650,796 a year (≈ $39,300) and gives a first stay of 3 years.
Can I retire or live in South Africa on my savings or pension?
South Africa has 2 retirement or pay-to-stay routes. PR · Financially independent asks for assets of at least ZAR 12,000,000 (≈ $725,000). PR · Retired person asks for an income of at least ZAR 37,000 a month (≈ $2,240).
Can I move to South Africa by starting a business?
South Africa has 1 business or startup route. PR · Business asks for an investment of ZAR 5,000,000 (≈ $302,000).
What work visas does South Africa offer foreigners?
South Africa has 1 work visa. It is PR · Critical skills.
Can I join my spouse or partner in South Africa?
Yes. South Africa has 1 spouse visa. It is Spouse of a citizen.
Compare with
≈ USD figures are approximate: daily reference rates from ExchangeRate-API, dated 12 Oct 2026, refreshed when the site is updated.
Ask the AI about South Africa AI
An AI assistant answers from the published records on this page and cites them. It can't assess your personal eligibility. Don't include personal details.
Sources (3)
Official sources
- Permanent Residency · Department of Home Affairs, South Africa · checked 2026-10-10
- Regulation Gazette 55209: First amendment of the regulations on fees (Immigration Act) · Department of Home Affairs, South Africa · checked 2026-10-10 · published 2026-08-17
- Permanent Residency (categories, form BI-947, documents) · Department of Home Affairs · checked 2026-10-11