Moving to Jordan
7 ways to move to Jordan in our guide: 3 investor routes, 1 pay-to-stay route, 2 work visas, 1 student visa.
No digital nomad visa. Smallest investment: Residency · JOD 150k regional, JOD 150k+ ≈ $212k. Checked against official sources on .
Jordan offers a calm, practical route to residency if you are ready to invest in property. The rules are clear: buy qualifying real estate, keep it, and you can secure a renewable stay.
Investing · 3

Residency
Investment needed: from JOD 150k ≈ $212k
Retire or live on savings · 1

Bank deposit residence
Savings needed: from JOD 10k ≈ $14k
Work · 2

Skilled work permit
First stay: 2 yrs
Work permit
Student · 1

Student residence
First stay: 1 yr
Tax
Tax rules for newcomers are not covered in the records.
Standard rules
Jordan: income tax on income arising in the Kingdom; general sales tax 16%
Details
- On: Income arising in Jordan (salaries, business and professional income, property trading)
- Who: Income arising in the Kingdom is taxable
- Limit: JOD 2,500/mo ≈ $3,530
Income tax under Law No. 34 of 2014 applies to income arising in Jordan, and exemptions apply only where the law names them; the general sales tax rate is 16% on goods and services not listed in the reduced-rate or exempt schedules.
Taxed on
Income arising in Jordan (salaries, business and professional income, property trading); general sales tax on supply value.
Who it applies to
- Income arising in the Kingdom is taxable, and exemption is the exception set out in the law.
- The general sales tax schedules list goods at 0%, 2%, 4%, 5% and 10%; remaining goods and services carry 16%.
Exclusions
- Exempt sources are listed in the law, including agricultural income from activity inside the Kingdom and the first JOD 2,500 (≈ $3,530) of gross monthly retirement pension, disability pension included (Article 4 of Income Tax Law No. 34 of 2014 as amended by Law No. 38 of 2018).
Limits
- JOD 2,500 a month (≈ $3,530) · Gross monthly retirement pension, disability pension included, is exempt from income tax up to this amount (Article 4(a)(14), as amended by Law No. 38 of 2018).
Tax residence
Income arising in Jordan is the taxable base; a resident's income from abroad is taxed only for income arising from funds and deposits from Jordan, at 10% of net income, under the 2014 law.
Visas
A residence permit does not set tax status.
Other taxes
General sales tax 16% standard rate.
Checked against official sources on , some details partly verifiedChange log
Standard rules
Jordan individual income tax: progressive scale, exemptions and national contribution
Details
- On: Net taxable income arising in Jordan after deductions
- Limit: JOD 5,000/yr ≈ $7,050
Resident individuals pay income tax at 5% on the first JOD 5,000 (≈ $7,050) of taxable income, 10% on the next JOD 5,000, (≈ $7,050) 15% on the next JOD 5,000, (≈ $7,050) 20% on the next JOD 5,000, (≈ $7,050) 25% up to JOD 1,000,000 (≈ $1,410,000) and 30% above that, after a personal exemption of JOD 9,000 (≈ $12,700) and a dependants exemption of JOD 9,000 (≈ $12,700).
Taxed on
Net taxable income arising in Jordan after deductions; a resident individual may deduct a personal exemption of JOD 9,000 (≈ $12,700) and a dependants exemption of JOD 9,000, (≈ $12,700) with up to JOD 1,000 (≈ $1,410) each for the taxpayer and spouse and up to JOD 3,000 (≈ $4,230) for children against medical, education, rent and housing-loan costs, and total exemptions capped at JOD 23,000 (≈ $32,400).
Who it applies to
- Applies to individuals with Jordan-source income, whether resident or non-resident.
- Personal and dependants exemptions are granted to resident individuals only; a non-resident Jordanian may claim the dependants exemption for dependants resident in Jordan.
- A national contribution of 1% applies to taxable income above JOD 200,000 (≈ $282,000).
Exclusions
- Non-residents receive no personal exemption.
- Income paid to non-residents that is not exempt is subject to 10% withholding at source.
- Foreign-source income of residents follows a separate rule described in the foreign-source income record.
Limits
- JOD 5,000 a year (≈ $7,050) · Each of the first four bands is JOD 5,000 (≈ $7,050) wide: 5%, 10%, 15% and 20%.
- JOD 20,000 a year (≈ $28,200) · Taxable income above this amount is taxed at 25% up to JOD 1,000,000 (≈ $1,410,000).
- JOD 1,000,000 a year (≈ $1,410,000) · Taxable income above this amount is taxed at 30%.
- JOD 9,000 a year (≈ $12,700) · Personal exemption of a resident individual (from tax year 2020).
- JOD 9,000 a year (≈ $12,700) · Exemption for dependants, whatever their number (from tax year 2020).
- JOD 23,000 a year (≈ $32,400) · Maximum total personal, dependants and spouse exemptions.
- JOD 200,000 a year (≈ $282,000) · National contribution of 1% applies to taxable income above this amount.
Days in the country
- At least 183 days in tax period (calendar year), consecutive or interrupted · A natural person who is physically present in Jordan for at least 183 days in the tax period is a resident person.
Tax residence
A resident natural person is someone who stays in Jordan for at least 183 days in the tax period, continuous or in several stays, or a Jordanian employee who works for the government or public institutions in or outside Jordan. The tax period is the calendar year unless the Department is notified of a different financial year.
Visas
Residence for tax is based on days present in the tax year, not on permit type.
Other taxes
General sales tax and social security contributions are separate from income tax. Tax at source is deducted from employment income under the executive instructions.
Checked against official sources on Change log
Standard rules
Jordan tax on foreign-source income of residents
10% tax
Details
- Who: Applies to a resident person (183 days or more in the tax year)
Jordan taxes income arising in or derived from Jordan; a resident's net foreign-source income is taxed at 10% with no deductions only where it arises from funds or deposits taken from Jordan, and other foreign-source income is outside the Jordanian tax base.
Taxed on
Net foreign-source income of a resident person that arises from funds or deposits from Jordan; the tax is a flat 10% and no deduction is allowed. Jordan-source income is taxed on the progressive scale for individuals.
Who it applies to
- Applies to a resident person (183 days or more in the tax year).
- Applies only to foreign-source income that arises from funds or deposits from Jordan.
Exclusions
- Foreign-source income of a resident that does not arise from funds or deposits from Jordan is not listed as taxable income.
- Income from services is Jordan-source where the work or activity is carried out in Jordan or the output is used in Jordan, including when earned by a non-resident.
- Income from e-commerce in goods and services is taxable.
Days in the country
- At least 183 days in tax period (calendar year), consecutive or interrupted · Resident status for the foreign-source rule requires physical presence in Jordan for at least 183 days in the tax period.
Tax residence
The territorial scope in Article 3 of the Income Tax Law is Jordan-source income; the 10% rule for foreign-source income applies to residents (183 days or more).
Visas
No residence permit grants a separate foreign-source income regime; the rule follows the 183-day residence test.
Other taxes
A 10% withholding tax applies to non-exempt income paid to non-residents. Interest on bank deposits in Jordan carries 5% withholding for individuals, which is final tax for them.
Checked against official sources on Change log
Checked against official sources on Change log
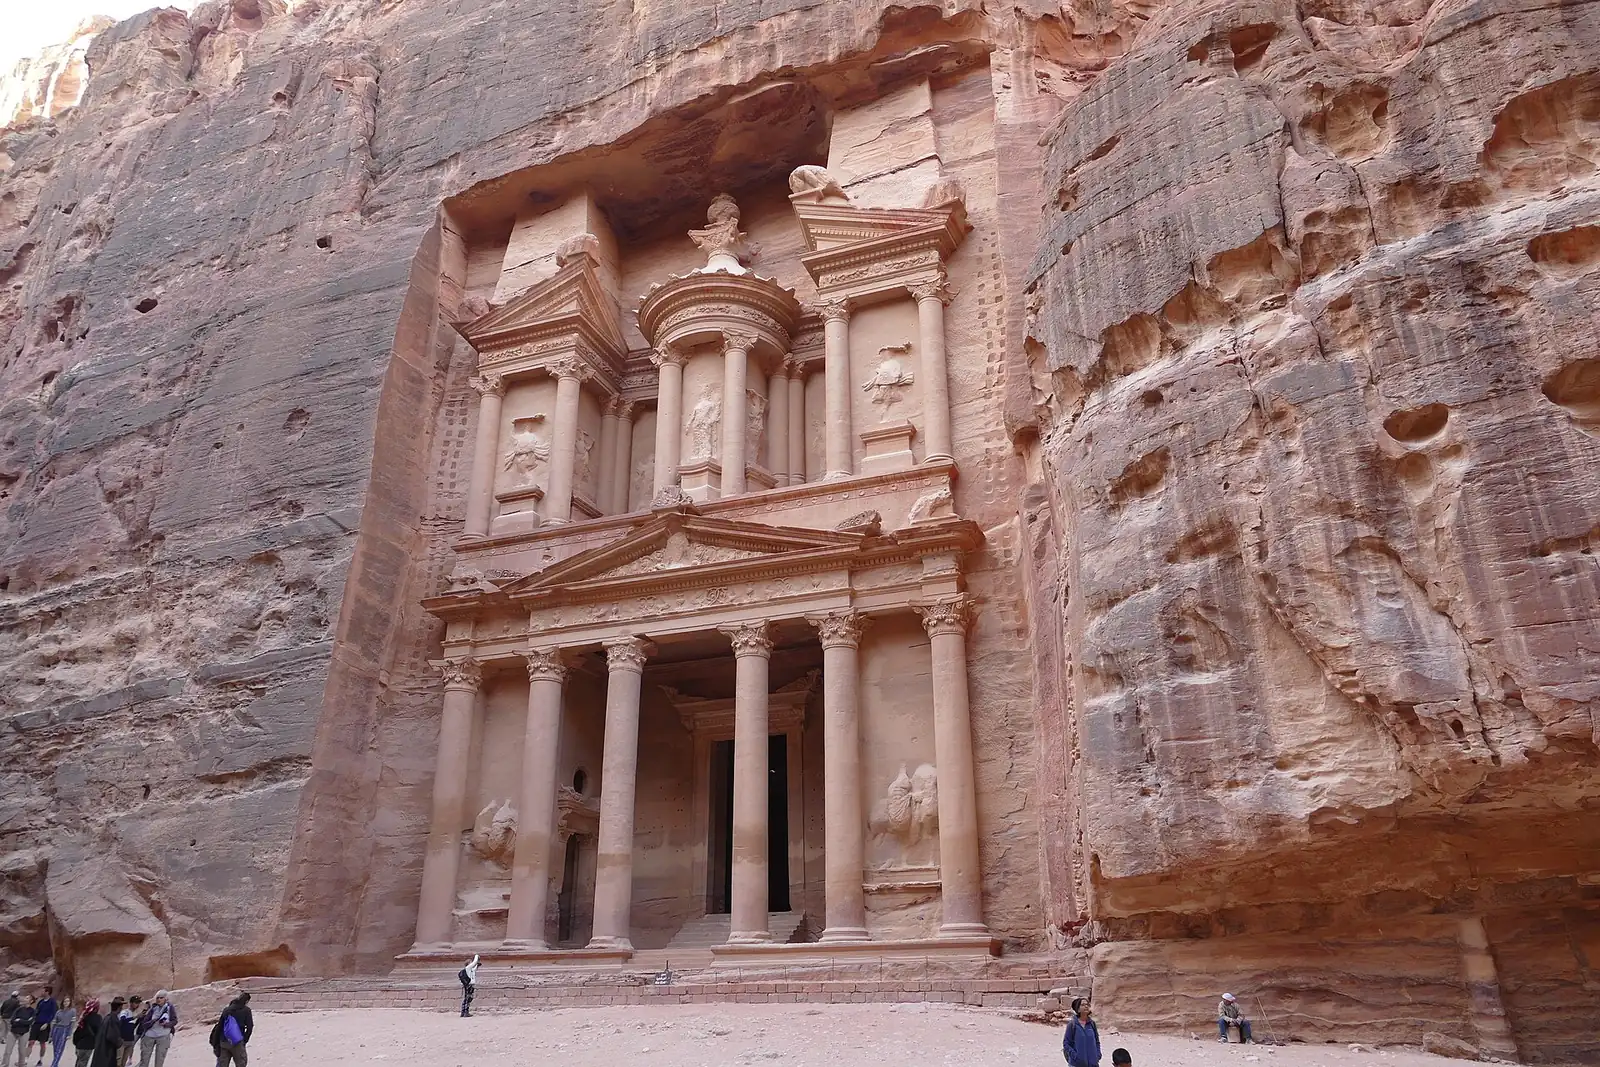
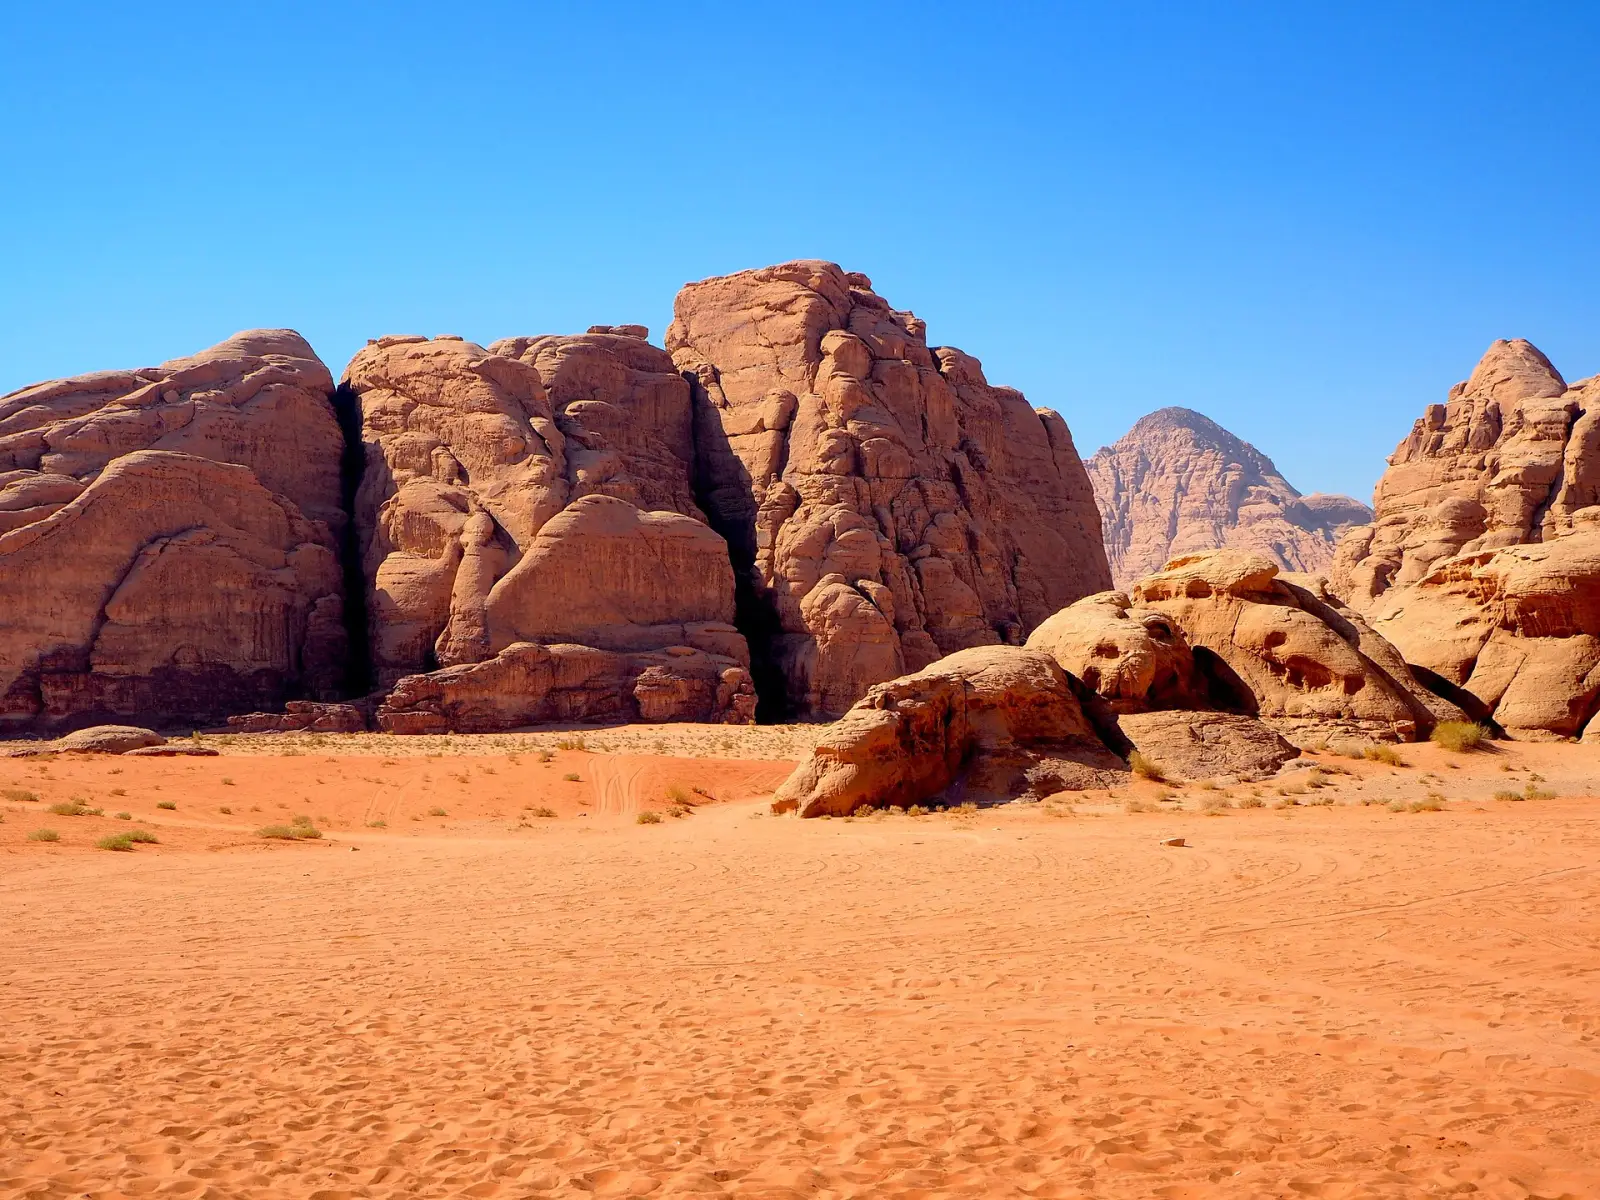
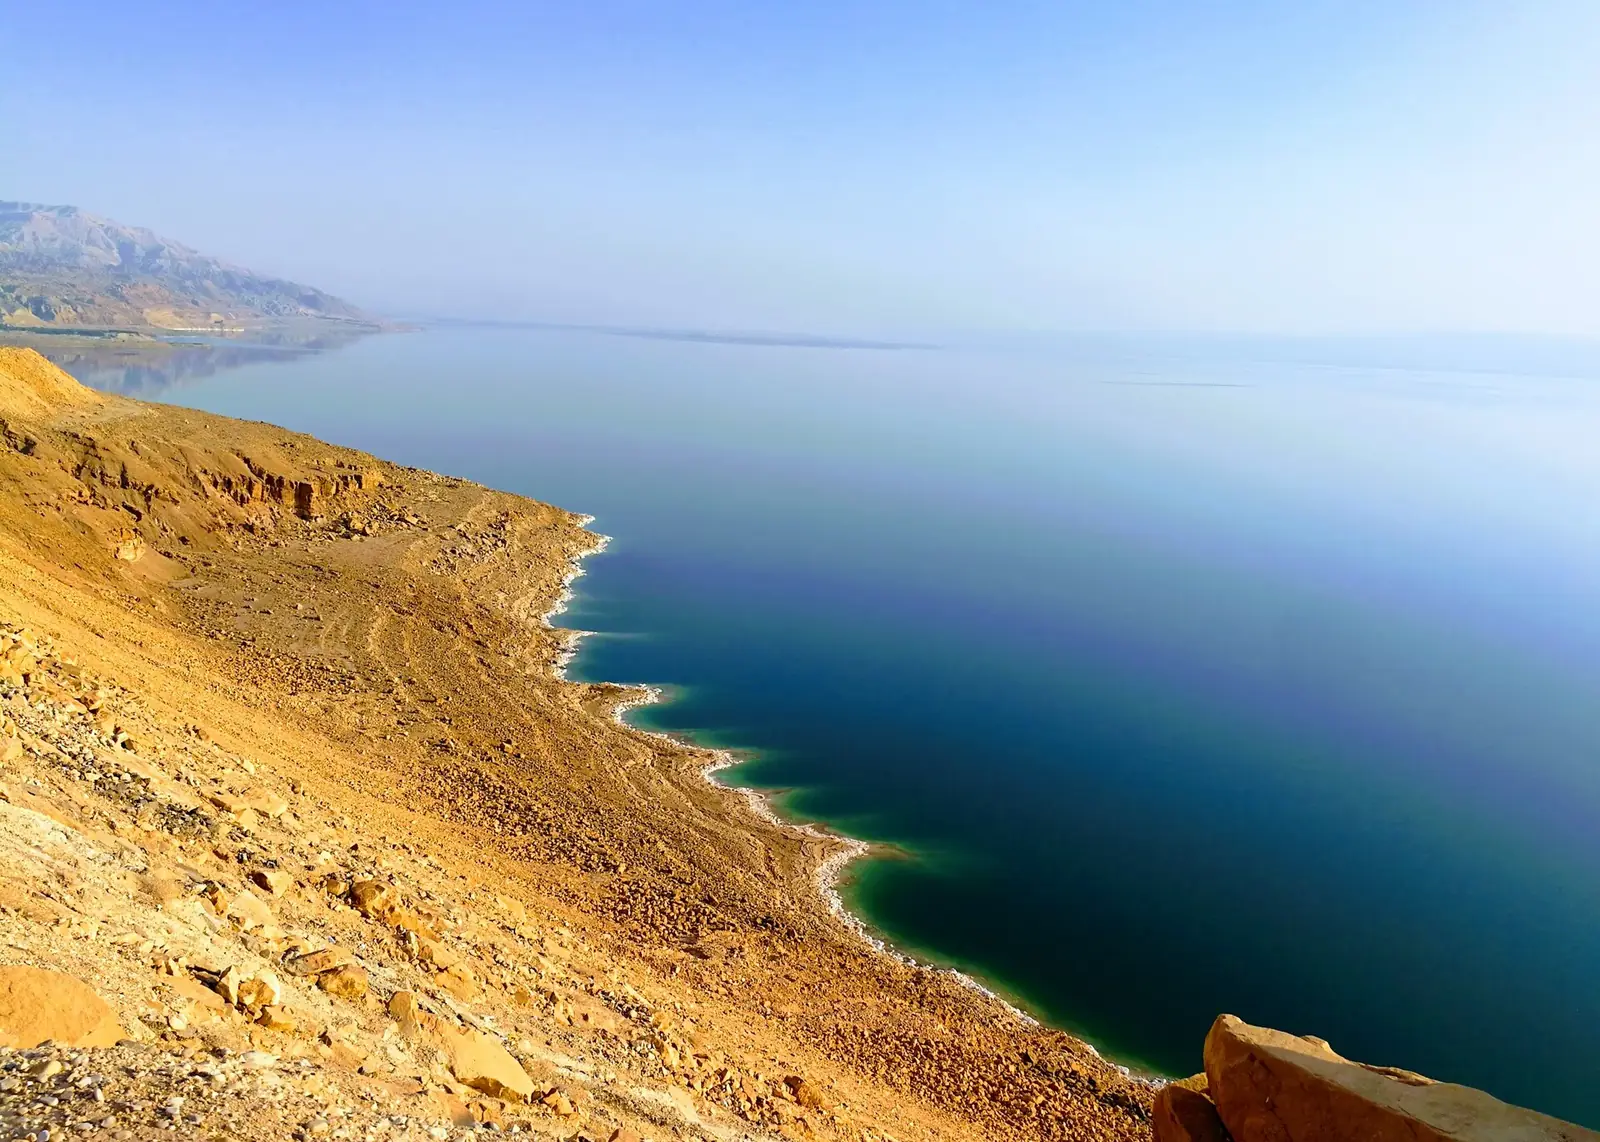
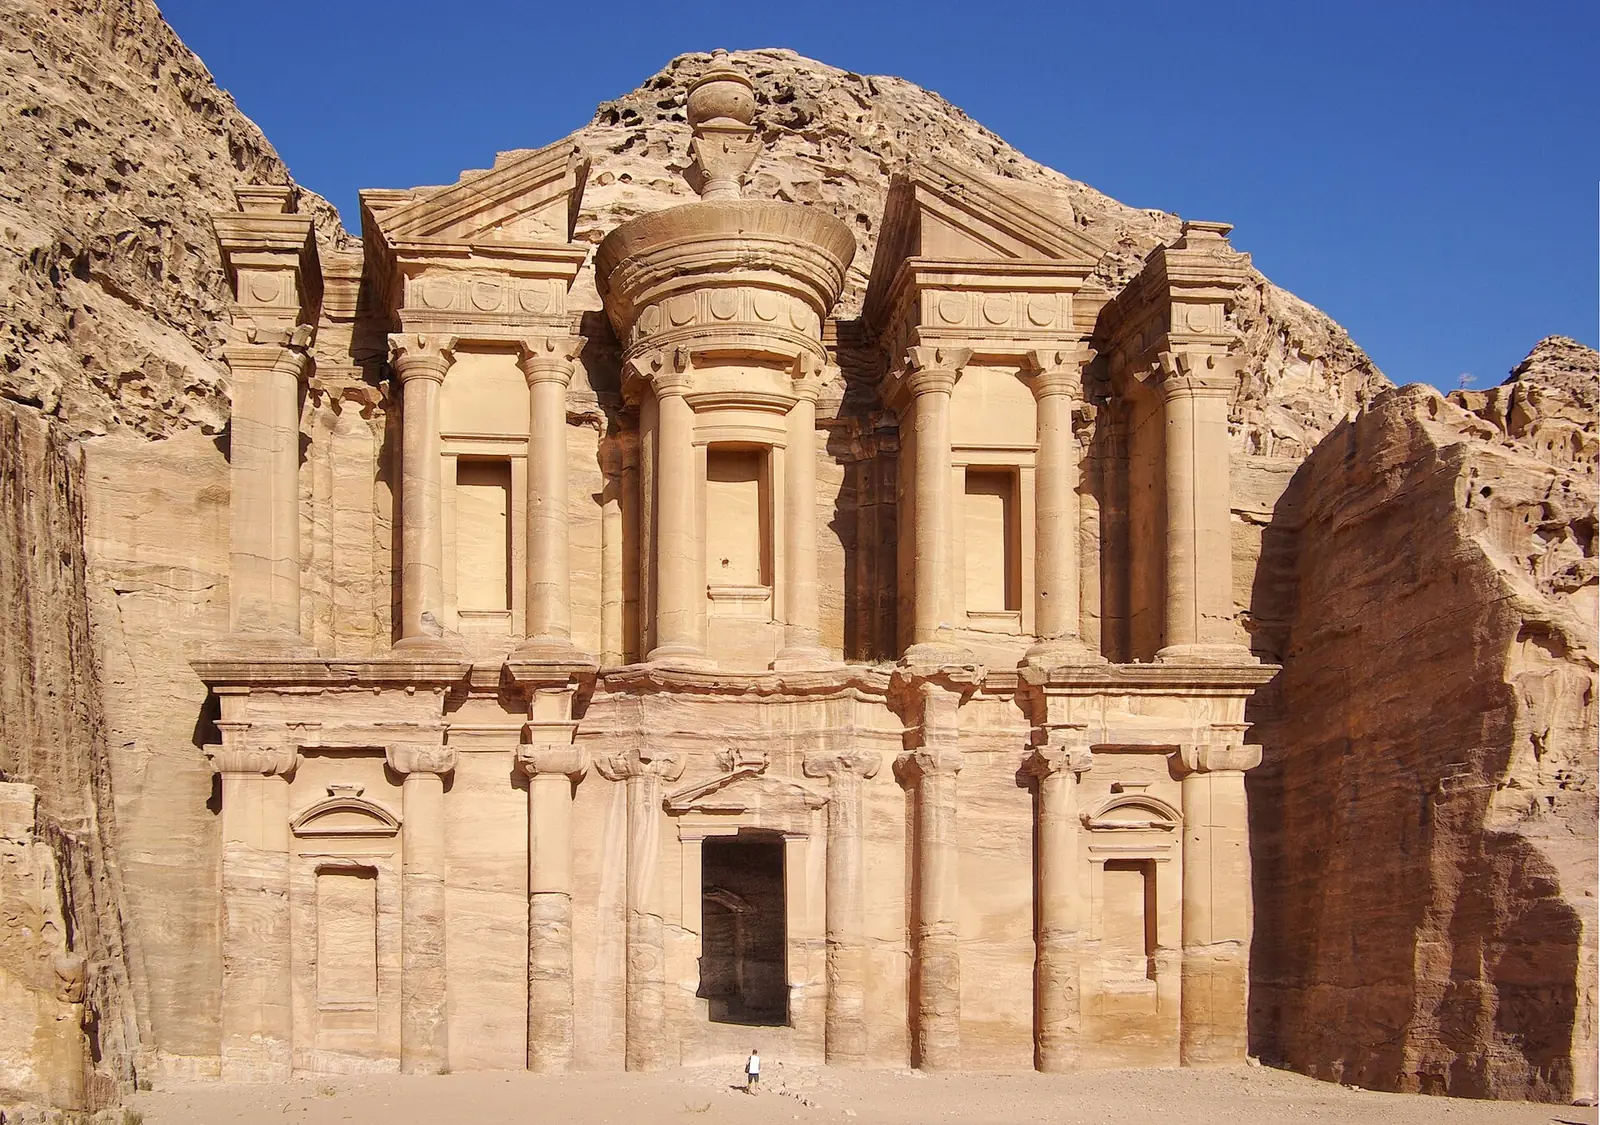
Jordan in pictures
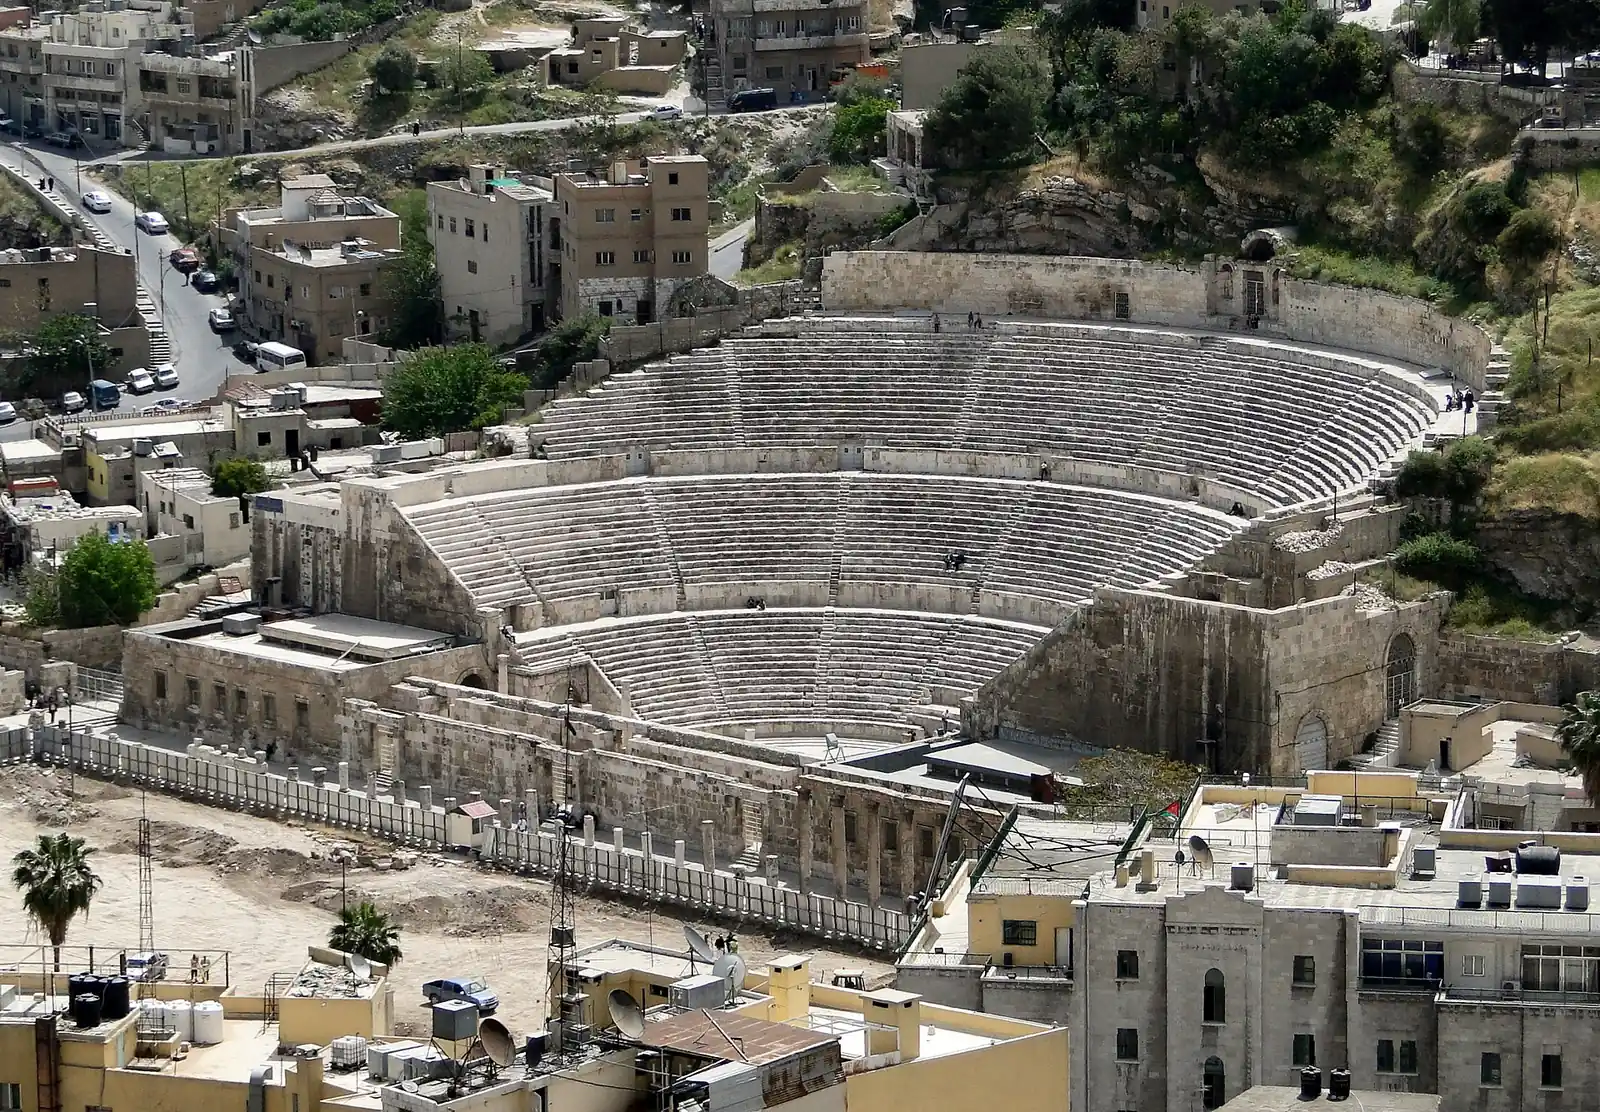
Arriving in Jordan: first steps
- Arrange health cover for yourself and any dependents.
- Secure a permanent address, as it is needed for residency paperwork.
- Open a local bank account for property and living expenses.
- Register your property purchase with the Department of Lands and Survey.
- Submit your investor file through the Ministry of Investment.
- Keep your property unsold and unmortgaged to maintain residency.
Questions people ask
How much do you need to invest for residency in Jordan?
Jordan has 3 investor routes. Residency · JOD 200k developer asks for an investment of at least JOD 200,000 (≈ $282,000) and gives a first stay of 5 years that can be renewed. Residency · JOD 300k private asks for an investment of at least JOD 300,000 (≈ $423,000) and gives a first stay of 5 years that can be renewed. Residency · JOD 150k regional asks for an investment of at least JOD 150,000 (≈ $212,000) and gives a first stay of 5 years that can be renewed.
Can I retire or live in Jordan on my savings or pension?
Jordan has 1 retirement or pay-to-stay route. Bank deposit residence asks for savings from JOD 10,000 (≈ $14,100) and gives a first stay of 5 years that can be renewed.
What work visas does Jordan offer foreigners?
Jordan has 2 work visas. Skilled work permit gives a first stay of 2 years that can be renewed. There is also Work permit.
How do I get a student visa for Jordan?
Jordan has 1 student visa. Student residence gives a first stay of 1 year that can be renewed.
Compare with
≈ USD figures are approximate: daily reference rates from ExchangeRate-API, dated 12 Oct 2026, refreshed when the site is updated.
Ask the AI about Jordan AI
An AI assistant answers from the published records on this page and cites them. It can't assess your personal eligibility. Don't include personal details.