Moving to Ireland
10 ways to move to Ireland in our guide: 1 working holiday visa, 1 pay-to-stay route, 1 business / startup route, 3 work visas, 1 student visa, 1 route by nationality or ancestry, 2 spouse visas.
No digital nomad visa. Tax for newcomers: Ireland: remittance basis for residents who are not Irish-domiciled, Remittance basis (non-dom). Checked against official sources on .
Ireland offers a range of routes for people who want to move there, from working holidays and study to employment permits and business start-ups. Each route has its own requirements, and the records here set out who can apply and what to expect.
Working holiday · 1

Working Holiday
Age limit and funds needed: Ages and funds vary by passport
Retire or live on savings · 1

Retirement / Stamp 0
Income needed: €50k+ a year ≈ $56k
Business / Startup · 1

Start-up Entrepreneur (STEP)
Assets needed: €50k+ ≈ $56k
Work · 3

Critical Skills permit
Income needed: from €37k a year ≈ $41k
General Employment permit
Income needed: from €33k a year ≈ $37k
Intra-company transfer permit
Income needed: from €37k a year ≈ $41k
Student · 1

Student permission
Savings needed: €10k+ ≈ $11k
For your nationality or ancestry · 1

Open only to citizens of certain countries or to people with family roots here. Unlike free movement, each needs an application.
Spouse visas · 2

For people married to, or in a partnership with, a citizen or permanent resident.
Spouse of a resident
Income needed: €30k+ a year ≈ $34k
Spouse of a citizen
Income needed: from €40k ≈ $45k
Free movement and visa-free stays · 2
Common Travel Area · Lets you live here
Open to 1 passport: United Kingdom.
EU free movement · Lets you live here
Open to 30 passports: Austria, Belgium, Bulgaria, Croatia, Cyprus, Czechia, Denmark, Estonia, Finland, France, Germany, Greece, Hungary, Iceland, Italy, Latvia, Liechtenstein, Lithuania, Luxembourg, Malta, Netherlands, Norway, Poland, Portugal, Romania, Slovakia, Slovenia, Spain, Sweden, Switzerland.
Tax
Tax is separate from immigration. New arrivals may be able to benefit from the Special Assignee Relief Programme (SARP), which disregards part of employment income for income tax for a limited number of years if you arrive after a certain date. Otherwise, Irish income tax rates apply, with a standard rate band and a higher rate above it, plus USC and PRSI.
Special regime
Special Assignee Relief Programme (SARP)
30% tax
Details
- Limit: €125k/yr ≈ $140k
For assignees arriving after 1 January 2026, 30% of employment income between EUR125,000 (≈ $140,000) and EUR1,000,000 (≈ $1,120,000) is disregarded for income tax for up to five consecutive years (four if the employer certifies after 90 days); assignments qualify for tax years 2012 to 2030.
Taxed on
Employment income from the relevant employer above the lower threshold, up to EUR1,000,000, (≈ $1,120,000) for income tax only.
Who it applies to
- Arrive in Ireland in a tax year from 2012 to 2030 at the request of the employer, to work for that employer or an associated company; the employer is incorporated and tax resident in a state with a double taxation agreement or tax information exchange agreement.
- Worked outside Ireland for the assigning employer for at least six months immediately before the assignment.
- Perform duties in Ireland for at least 12 consecutive months from the first assignment date.
- Not tax resident in Ireland for the five tax years before the arrival year; tax resident in every year for which relief is claimed.
- Minimum basic salary of EUR125,000 (≈ $140,000) a year (excluding bonuses, commissions, benefits and share-based pay) for arrivals from 2026; hold a PPSN.
- Employer certification submitted to Revenue within 90 days of arrival, or within 180 days for arrivals from 1 January 2026, in which case relief is not available for the first year.
Exclusions
- USC is charged on the full salary and relief does not extend to it.
- Maximum five consecutive years starting with the first year of entitlement; four years if employer certification is after 90 days (arrivals from 1 January 2026).
Limits
- EUR 125,000 a year (≈ $140,000) · Lower threshold for arrivals after 1 January 2026
- EUR 100,000 a year (≈ $112,000) · Lower threshold for arrivals from 1 January 2023 to 31 December 2025
- EUR 1,000,000 a year (≈ $1,120,000) · Upper limit of relieved income
Tax residence
Relief years are tax years of residence from the arrival year.
Visas
Independent of immigration permission; typically used with an intra-company or critical skills permit.
Other taxes
USC and PRSI are charged on full pay.
Checked against official sources on Change log
Standard rules
Irish income tax rates
Details
- On: Taxable income by band
- Who: Irish tax resident
- Limit: €44k/yr ≈ $49k
Income tax is 20% up to the standard rate band (EUR44,000 (≈ $49,200) for a single person) and 40% above it; USC and PRSI are additional.
Taxed on
Taxable income by band.
Who it applies to
- Irish tax resident.
Limits
- EUR 44,000 a year (≈ $49,200) · Standard rate band for a single person; 20% up to this amount, 40% above
Days in the country
- At least 183 days in tax year · Resident if present in Ireland 183 days or more in the tax year.
- At least 280 days in current and preceding tax year combined · Resident if present 280 days or more across two years, provided more than 30 days are spent in Ireland in the current year.
Tax residence
Residence is decided by days of presence in the tax year (section 819 TCA 1997).
Visas
Independent of permission type.
Other taxes
USC, PRSI and VAT are separate.
Checked against official sources on Change log
Special regime
Ireland: remittance basis for residents who are not Irish-domiciled
Tax relief
Details
- On: Actual sums remitted to Ireland out of foreign-source income
An individual resident in Ireland who is not Irish-domiciled is taxed on foreign-sourced income and foreign capital gains only to the extent they are remitted to Ireland; Irish-source income is taxed in full and the income of a non-Irish employment is taxable on the remittance basis only for duties performed outside Ireland.
Taxed on
Actual sums remitted to Ireland out of foreign-source income (Schedule D Case III) and foreign gains; Irish-source income and Irish gains on the arising basis at ordinary rates (20% standard rate band and 40% higher rate in the Revenue example for 2026).
Who it applies to
- Resident in Ireland for the tax year and satisfies Revenue that they are not domiciled in the State (section 71 TCA 1997).
Exclusions
- Duties of a non-Irish employment performed in Ireland are taxed under Schedule E on the arising basis.
- UK-source income is taxed on the arising basis (section 18 FA 2008).
- Other statutory exceptions are listed in Part 7 of the manual.
Days in the country
- At least 183 days in tax year · Resident if present in Ireland 183 days or more in the tax year.
- At least 280 days in current and preceding tax year combined · Resident if present 280 days or more across two years, provided more than 30 days are spent in Ireland in the current year.
Tax residence
Residence is by days of presence under section 819 TCA 1997; domicile is a separate general-law concept.
Visas
Not tied to a visa; SARP is a separate employment-income relief.
Other taxes
USC and PRSI follow their own rules; the Revenue manual notes the remittance basis is also available for foreign gains.
Checked against official sources on Change log
Checked against official sources on Change log
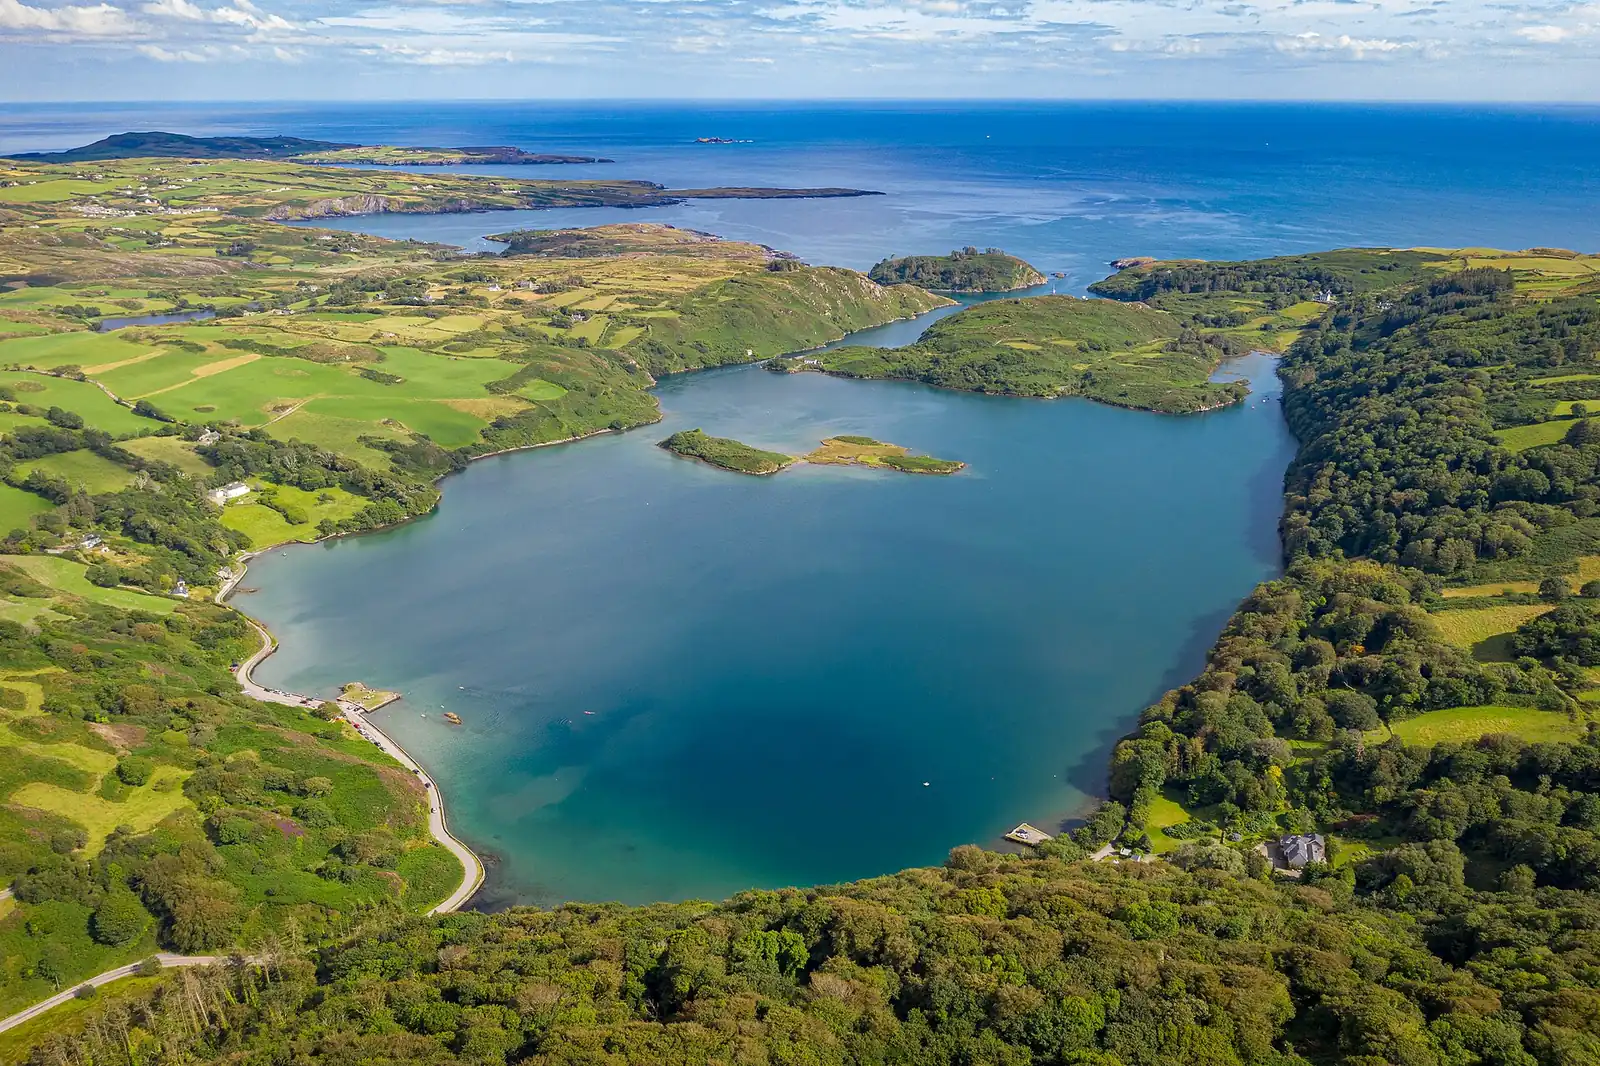
Ireland in pictures
Switch to later · 1
Work
Graduate programme
First stay: 1 yr
Path to permanent residence · 1
- Citizenship · Irish citizenship by descent and registration in the Foreign Births Register (Irish Nationality and Citizenship Act 1956, sections 7 and 27)
Arriving in Ireland: first steps
- Arrange health cover as required for your route.
- Provide proof of an Irish address for registration.
- Open an Irish bank account for day-to-day banking.
- Register with the immigration authorities as required by your permission.
- For students, attend at least the required percentage of classes and sit a recognised exam.
- For employment permit holders, start work with your named employer and follow the conditions of your permit.
Questions people ask
Does Ireland have a working holiday visa?
Yes. Ireland has 1 working holiday visa. Working Holiday asks for savings of at least HKD 40,000 (≈ $5,100) and gives a first stay of 1 year.
Can I retire or live in Ireland on my savings or pension?
Ireland has 1 retirement or pay-to-stay route. Retirement / Stamp 0 asks for an income of at least EUR 50,000 a year (≈ $55,900).
Can I move to Ireland by starting a business?
Ireland has 1 business or startup route. Start-up Entrepreneur (STEP) asks for assets of at least EUR 50,000 (≈ $55,900) and gives a first stay of 2 years that can be renewed.
What work visas does Ireland offer foreigners?
Ireland has 3 work visas. Critical Skills permit asks for a salary from EUR 36,848 a year (≈ $41,200) and gives a first stay of 2 years that can be renewed. General Employment permit asks for a salary from EUR 32,691 a year (≈ $36,500) and gives a first stay of 2 years that can be renewed. Intra-company transfer permit asks for a salary from EUR 36,605 a year (≈ $40,900) and gives a first stay of 2 years that can be renewed.
How do I get a student visa for Ireland?
Ireland has 1 student visa. Student permission asks for savings of at least EUR 10,000 (≈ $11,200).
Can my nationality or ancestry give me residence in Ireland?
Yes. Ireland has 1 route by nationality or ancestry. It is Irish citizenship by descent.
Can I join my spouse or partner in Ireland?
Yes. Ireland has 2 spouse visas. Spouse of a resident asks for an income of at least EUR 30,000 a year (≈ $33,500). Spouse of a citizen asks for an income from EUR 40,000 (≈ $44,700).
Does Ireland have a special tax regime for new residents?
Yes: Ireland: remittance basis for residents who are not Irish-domiciled. An individual resident in Ireland who is not Irish-domiciled is taxed on foreign-sourced income and foreign capital gains only to the extent they are remitted to Ireland; Irish-source income is taxed in full and the income of a non-Irish employment is taxable on the remittance basis only for duties performed outside Ireland. It is separate from the visa and has its own conditions.
Compare with
≈ USD figures are approximate: daily reference rates from ExchangeRate-API, dated 12 Oct 2026, refreshed when the site is updated.
Ask the AI about Ireland AI
An AI assistant answers from the published records on this page and cites them. It can't assess your personal eligibility. Don't include personal details.