Moving to Grenada
6 ways to move to Grenada in our guide: 1 nomad / remote-work visa, 3 investor routes, 2 work visas.
Remote workers: Remote work permit, XCD 100k+ a year ≈ $37k. Smallest investment: Citizenship · NTF $235k, $235k+. Tax for newcomers: Grenada: income tax charged on income accrued from sources in Grenada, Territorial. Checked against official sources on .
Grenada offers a few clear paths for people thinking about moving: a remote-work permit for those employed or running a business abroad, work permits tied to a local employer, and citizenship by investment for those ready to commit capital. Each route has its own rules, and they do not overlap.
Nomad / Remote work · 1

Remote work permit
Income needed: XCD 100k+ a year ≈ $37k
Investing · 3

Citizenship
Investment needed: from $235k
Work · 2

Internship work permit
First stay: 1 yr
Work permit
First stay: 1 yr
Free movement and visa-free stays · 1
CARICOM free movement · Lets you live here
Open to 11 passports: Antigua and Barbuda, Barbados, Belize, Dominica, Guyana, Jamaica, Saint Kitts and Nevis, Saint Lucia, Suriname, Trinidad and Tobago, VC.
Tax
Grenada taxes assessable income accrued from sources in Grenada, for residents and non-residents alike. Foreign-source income of a Grenada resident generally falls outside that charge unless it is deemed to arise in Grenada. Remote-work permit holders and their dependants are exempt from Grenadian income tax on income generated outside Grenada and are treated as non-resident for certain Acts. Residency can arise through a permanent place of abode with some presence, or through presence for a set period in the year.
Standard rules
Personal income tax and territorial basis
30% tax
Details
- Who: Residents and non-residents are charged on Grenadian-source income only
- Limit: XCD 24k/yr ≈ $8,890
The Income Tax Act taxes assessable income accrued from sources in Grenada for both residents and non-residents; individuals pay 10% on the first EC$24,000 of chargeable income (SRO 2 of 2017, from 1 January 2017) and 30% above (SRO 1 of 2014), after a EC$36,000 allowance for residents.
Taxed on
Income accrued from sources in Grenada (employment exercised in Grenada, local business and other Grenadian-source income)
Who it applies to
- Residents and non-residents are charged on Grenadian-source income only.
Exclusions
- Income accruing from a source outside Grenada to a retired individual who was not resident in Grenada before retirement is exempt.
Limits
- XCD 24,000 a year (≈ $8,890) · First EC$24,000 of chargeable income taxed at 10% (15% before 1 January 2017); the excess at 30%.
- XCD 36,000 a year (≈ $13,300) · Resident individuals deduct the first EC$36,000 of assessable income (s.42A as amended by SRO 1 of 2014).
Days in the country
- At least 183 days in year of assessment · Physical presence for not less than 183 days in the year of assessment makes an individual resident.
Tax residence
An individual is resident if the permanent place of abode is in Grenada and the person is present for some period in the year, or if present for 183 days or more in the year, or continuous with such a period in an adjacent year.
Visas
Citizenship by investment and the Remote Employment permit do not change the territorial basis; remote-work permit holders are separately exempted from income tax on income generated outside Grenada.
Checked against official sources on , some details partly verifiedChange log
Special regime
Remote-work permit income tax exemption
Tax relief
Details
- On: Income generated outside Grenada
No Grenadian income tax is payable on income generated outside Grenada by a remote-work permit holder or dependant, who are also deemed non-resident for the Citizenship Act, Immigration Act and Representation of the People Act.
Taxed on
Income generated outside Grenada
Who it applies to
- Holder of a remote-work permit and dependants, for the permit period.
Exclusions
- Income from employment or services in Grenada is outside the permit conditions.
Tax residence
Permit holders are presumed non-resident for the three Acts listed.
Visas
Tied to the remote-work permit under the Remote Employment Act, 2021.
Other taxes
Conditional duty exemptions on personal effects are listed in Schedule III of the Act.
Checked against official sources on , some details partly verifiedChange log
Special regime
Grenada: income tax charged on income accrued from sources in Grenada
Tax relief
Details
- On: Amounts accrued directly or indirectly from sources in Grenada (s.8)
- Who: Applies to residents and non-residents alike
- Limit: XCD 24k/yr ≈ $8,890
The Income Tax Act defines assessable income of both residents and non-residents as amounts accrued from sources in Grenada, so foreign-source income of a Grenada resident is outside the charge to tax unless it is deemed to arise in Grenada (for example employment exercised outside Grenada by an ordinarily resident person where payment is charged directly to a Grenadian source).
Taxed on
Amounts accrued directly or indirectly from sources in Grenada (s.8), with deemed Grenadian sources in s.10; individual rates in the Fifth Schedule: 10% on the first XCD 24,000 (≈ $8,890) of chargeable income (15% before 1 January 2017, changed by SRO 2 of 2017) and 30% on the excess (SRO 1 of 2014).
Who it applies to
- Applies to residents and non-residents alike; individual resident if present for 183 days, or with a permanent place of abode and some presence.
Exclusions
- Income deemed to accrue from Grenadian sources under s.10 is taxable even if earned abroad.
- Interest accruing to banks and banking businesses in Grenada is taxable whether or not received in Grenada.
Limits
- XCD 24,000 a year (≈ $8,890) · Chargeable income up to this amount taxed at 10% (15% before 1 January 2017); the excess at 30%.
Days in the country
- At least 183 days in year of assessment · Resident in Grenada if physically present for not less than 183 days in the year of assessment (definition of resident in Grenada, para (a)(ii)); a permanent place of abode in Grenada plus some presence also qualifies
Tax residence
Statutory residence by 183 days or permanent abode with some presence; the scope-of-charge rule (s.8) uses sources in Grenada for residents and non-residents.
Visas
The tax treatment follows from the Income Tax Act and is independent of citizenship-by-investment or residence permit status.
Other taxes
Company rate under SRO 1 of 2014 is 30%.
Checked against official sources on , some details partly verifiedChange log
Checked against official sources on Change log
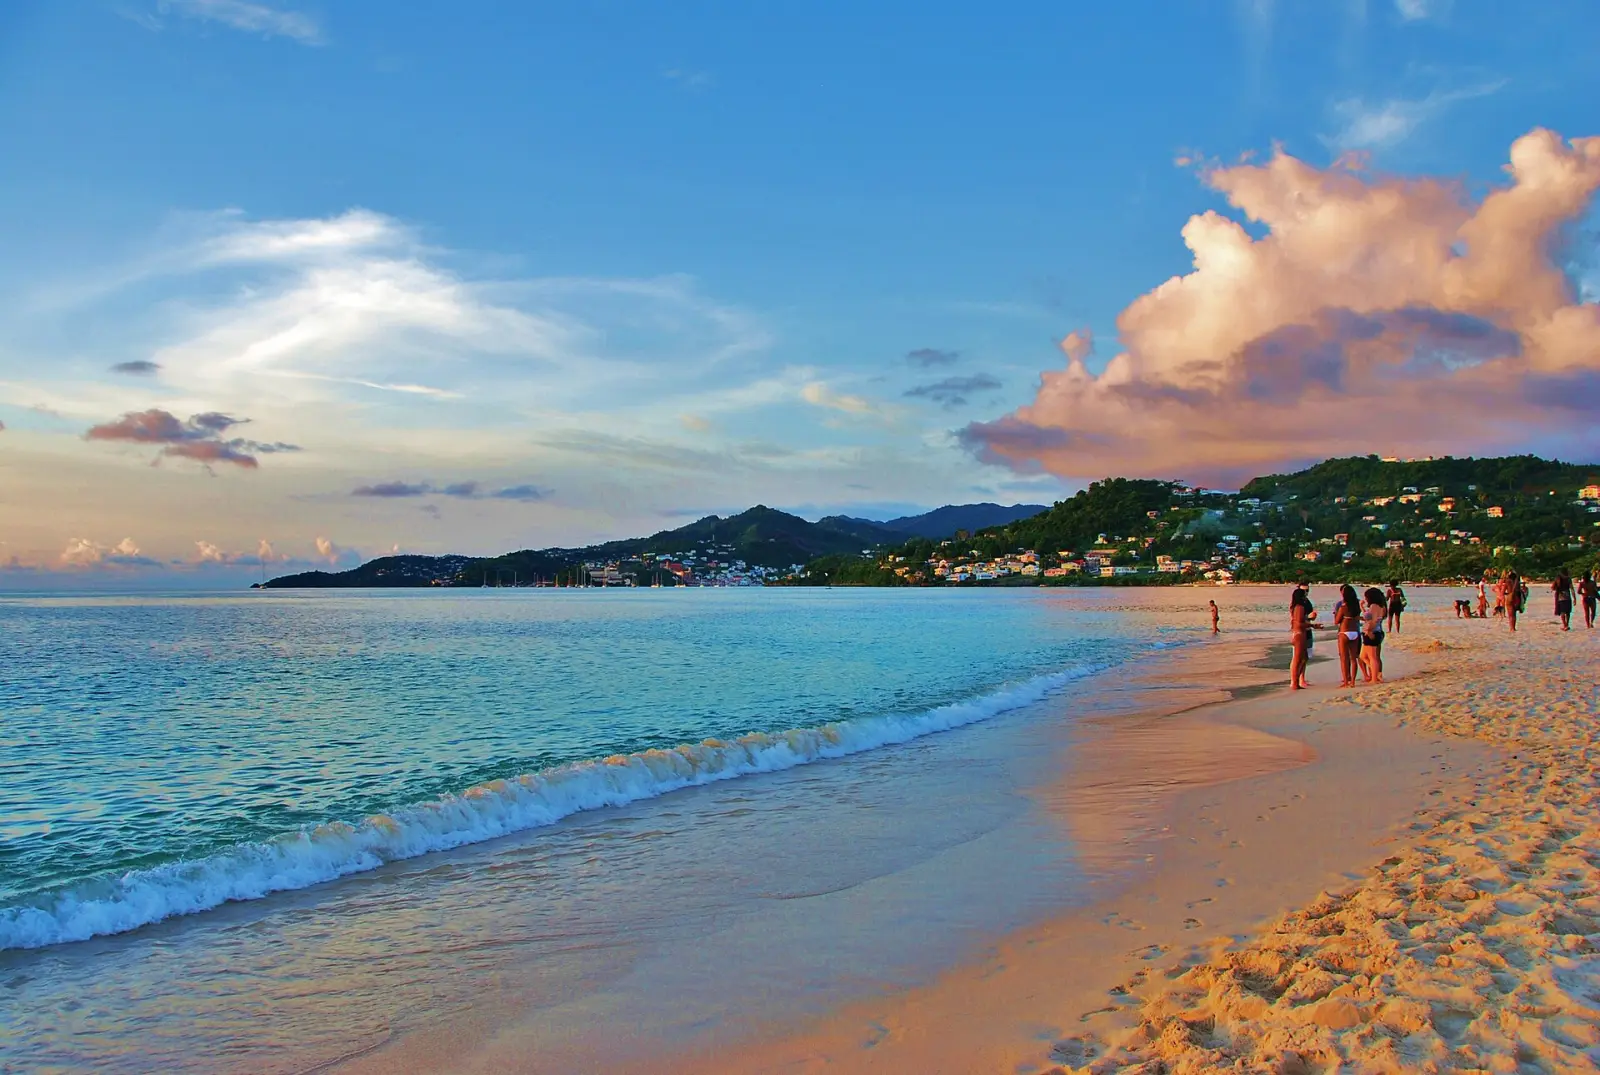
Grenada in pictures
Path to permanent residence · 1
- PR · Permit of permanent residence (Immigration Act s.24)
Arriving in Grenada: first steps
- Arrange health insurance covering your permit period, as required for the remote-work permit and useful for other routes.
- Keep your passport valid for the full period of any permit you hold.
- Obtain a police certificate for yourself and, where required, for dependants over the relevant age.
- If you are applying through a Local Agent for citizenship by investment, expect funds to be placed in an irrevocable escrow account before the application is considered.
- If you are taking up local work, remember the employer submits the work permit application to the Ministry of Labour and must meet wage and National Insurance obligations.
Questions people ask
What is the Grenada digital nomad visa income requirement in 2026?
Grenada has 1 nomad or remote-work visa. Remote work permit asks for an income of at least XCD 100,000 a year (≈ $37,000) and gives a first stay of 1 year that can be renewed.
How much do you need to invest for residency in Grenada?
Grenada has 3 investor routes. Citizenship · $350k property asks for an investment of at least $350,000. Citizenship · $270k shared asks for an investment of at least $270,000. Citizenship · NTF $235k asks for an investment of at least $235,000.
What work visas does Grenada offer foreigners?
Grenada has 2 work visas. Internship work permit gives a first stay of 1 year. Work permit gives a first stay of 1 year that can be renewed.
Does Grenada have a special tax regime for new residents?
Yes: Grenada: income tax charged on income accrued from sources in Grenada. The Income Tax Act defines assessable income of both residents and non-residents as amounts accrued from sources in Grenada, so foreign-source income of a Grenada resident is outside the charge to tax unless it is deemed to arise in Grenada (for example employment exercised outside Grenada by an ordinarily resident person where payment is charged directly to a Grenadian source). It is separate from the visa and has its own conditions.
Compare with
≈ USD figures are approximate: daily reference rates from ExchangeRate-API, dated 12 Oct 2026, refreshed when the site is updated.
Ask the AI about Grenada AI
An AI assistant answers from the published records on this page and cites them. It can't assess your personal eligibility. Don't include personal details.