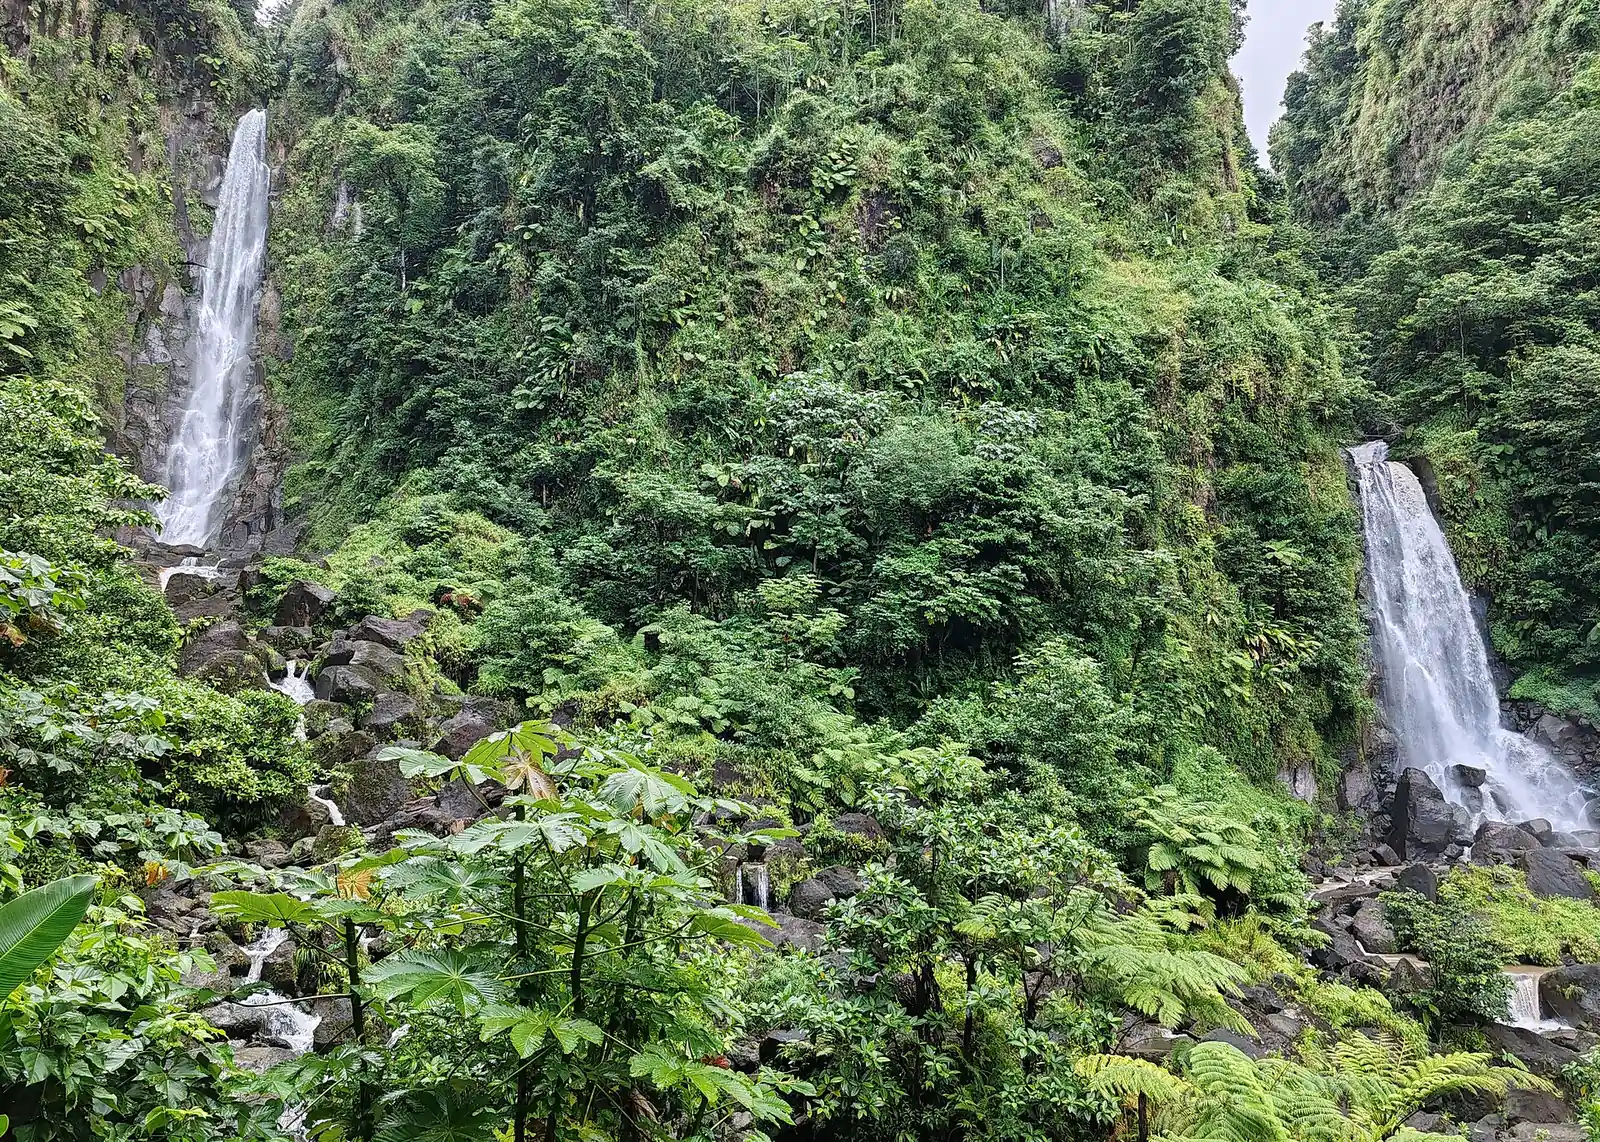
Moving to Dominica
4 ways to move to Dominica in our guide: 1 nomad / remote-work visa, 2 investor routes, 1 work visa.
Remote workers: WIN nomad visa, $50k+ a year. Smallest investment: Citizenship · $200k property, $200k+. Tax for newcomers: Dominica: resident but not ordinarily resident individuals taxed on foreign-source income only when received, Remittance basis. Checked against official sources on .
Dominica is a small Caribbean island that offers a calm, nature-focused base for remote workers and a formal route to citizenship for investors. This guide covers the main ways to stay: a remote-work visa, citizenship by investment, and a local work permit.
Nomad / Remote work · 1

WIN nomad visa
Income needed: $50k+ a year
Investing · 2

Citizenship
Investment needed: $200k+
Work · 1

Work permit
First stay: 1 yr
Free movement and visa-free stays · 2
CARICOM free movement · Lets you live here
CARICOM free movement · Lets you live here
Open to 11 passports: Antigua and Barbuda, Barbados, Belize, Grenada, Guyana, Jamaica, Saint Kitts and Nevis, Saint Lucia, Suriname, Trinidad and Tobago, VC.
Tax
Tax in Dominica depends on your residency and the route you take. Remote workers on the WIN visa get a waiver of Dominican income tax on their remote-work income and remain responsible for tax in their home country. If you become resident but not ordinarily resident, foreign-source income is taxed only when it is received in Dominica. Ordinary residents are taxed on all sources, but the rules are separate from immigration, so get advice for your own case.
Standard rules
Personal income tax (residents)
35% tax
Details
- Limit: XCD 30k/yr ≈ $11k
Resident individuals file annual returns; the Inland Revenue Division lists a resident allowance of EC$30,000, then 15% on the next EC$20,000, 25% on the next EC$30,000 and 35% on income above EC$80,000.
Taxed on
Employment, business, rental, royalty, interest and other income, totalled before allowances
Who it applies to
- Resident individuals, including those physically present in Dominica for more than 183 days continuously.
Exclusions
- Employment-only income below EC$30,000 does not require a return.
Limits
- XCD 30,000 a year (≈ $11,100) · Resident allowance; employment-only income below this amount needs no return.
- XCD 80,000 a year (≈ $29,600) · Income above this amount is taxed at 35%; EC$30,001 to 50,000 at 15% and EC$50,001 to 80,000 at 25% (Inland Revenue Division rates in force from 1 January 2018).
Days in the country
- More than 183 days in continuous presence · Individuals physically present in Dominica for more than 183 days continuously are treated as resident and must file returns.
Tax residence
The Inland Revenue Division describes as resident, for returns, people physically present in Dominica for more than 183 days continuously; the Income Tax Act test in the other Dominica income tax record is presence for not less than 183 days in the basis period.
Visas
The Citizenship by Investment Unit describes Dominica as having no wealth, gift, inheritance, foreign-source income or capital gains tax. WIN visa holders receive an income tax waiver on remote work and remain liable in their home country.
Checked against official sources on , some details partly verifiedChange log
Special regime
WIN visa income tax waiver
Tax relief
Details
- On: Income from remote work for non-Dominican-registered employers or clients
Remote workers on the Work in Nature visa receive a waiver of Dominican income tax on remote-work income and remain responsible for income tax in their normal country of residence.
Taxed on
Income from remote work for non-Dominican-registered employers or clients
Who it applies to
- Holder of the WIN Extended Stay Visa working remotely for companies and individuals not registered in Dominica.
Exclusions
- Does not remove tax liability in the holder's home country; import duty and VAT relief applies to personal items within the first three months only.
Tax residence
Applies for the visa period of up to 18 months.
Visas
Tied to the WIN Extended Stay Visa.
Other taxes
Customs Service Charge and Environmental Surcharge remain payable on imported personal effects.
Checked against official sources on , some details partly verifiedChange log
Special regime
Dominica: resident but not ordinarily resident individuals taxed on foreign-source income only when received
Tax relief
Details
- On: Foreign-source income is taxed only to the extent received in Dominica
Under section 8(2) of the Income Tax Act, an individual who is resident but not ordinarily resident in Dominica has assessable income that includes income accrued from sources outside Dominica only to the extent that such income is received in Dominica.
Taxed on
Foreign-source income is taxed only to the extent received in Dominica; Dominican-source income is taxed on an accrual basis at the progressive rates.
Who it applies to
- Individual who is resident in Dominica by the 183-day test or continuity rule but whose permanent place of abode is not in Dominica (not ordinarily resident).
Exclusions
- Individuals with a permanent place of abode in Dominica who are present for some period in the basis period are ordinarily resident and are taxed on all sources in or out of Dominica (s.8(1)(a)).
Days in the country
- At least 183 days in basis period for the year of assessment · Resident in Dominica if the individual is physically present for not less than 183 days in the basis period (Income Tax Act definition of resident in Dominica, para (a)(ii)); a permanent place of abode in Dominica plus presence for some period also makes an individual ordinarily resident (para (a)(i))
Tax residence
Resident status: 183 days or more in the basis period, or a permanent place of abode with some presence; ordinarily resident means resident under the permanent-place-of-abode limb.
Visas
The rule follows from tax residence under the Income Tax Act, not from a visa category.
Other taxes
Corporate income tax is charged at 25% from 1 January 2016 (IRD rates page).
Checked against official sources on , some details partly verifiedChange log
Standard rules
Dominica individual income tax: residents and rates
Details
- On: Chargeable income after the resident allowance: first XCD 30,000 (≈ $11,100) nil, then 15%
- Who: Resident allowance is available only to persons resident for tax purposes (IRD)
- Limit: XCD 30k/yr ≈ $11k
Resident individuals are entitled to a XCD 30,000 (≈ $11,100) resident allowance (from 1 January 2018) and are taxed at 15% on the next XCD 20,000, (≈ $7,410) 25% on the next XCD 30,000 (≈ $11,100) and 35% on chargeable income above XCD 80,000 (≈ $29,600); the statute taxes residents on all sources in or out of Dominica, with remittance treatment for residents who are not ordinarily resident.
Taxed on
Chargeable income after the resident allowance: first XCD 30,000 (≈ $11,100) nil, then 15% (XCD 30,001 (≈ $11,100)-50,000), 25% (XCD 50,001 (≈ $18,500)-80,000) and 35% above XCD 80,000 (≈ $29,600). Residents: assessable income from all sources in or out of Dominica; non-residents: sources in Dominica.
Who it applies to
- Resident allowance is available only to persons resident for tax purposes (IRD).
Exclusions
- Persons whose income is entirely employment income below XCD 30,000 (≈ $11,100) are not obliged to file a return (IRD).
Limits
- XCD 30,000 a year (≈ $11,100) · Resident allowance; chargeable income above it is taxed at 15% to XCD 50,000, (≈ $18,500) 25% to XCD 80,000 (≈ $29,600) and 35% above
- XCD 80,000 a year (≈ $29,600) · Chargeable income above this amount is taxed at 35%
Days in the country
- At least 183 days in basis period for the year of assessment · Resident in Dominica if the individual is physically present for not less than 183 days in the basis period (Income Tax Act definition of resident in Dominica, para (a)(ii)); a permanent place of abode in Dominica plus presence for some period also makes an individual ordinarily resident (para (a)(i))
Tax residence
Individuals physically present in Dominica for more than 183 days continuously are described by the IRD as resident and required to file by 31 March; the statute test is 183 days in the basis period.
Visas
Tax residence is independent of immigration or citizenship-by-investment status.
Other taxes
Corporate income tax is 25% from 1 January 2016; returns are due 31 March each year; late filing penalty is 5% of tax on chargeable income and late payment penalty 10% plus 1% monthly interest (IRD).
Checked against official sources on , some details partly verifiedChange log
Checked against official sources on Change log
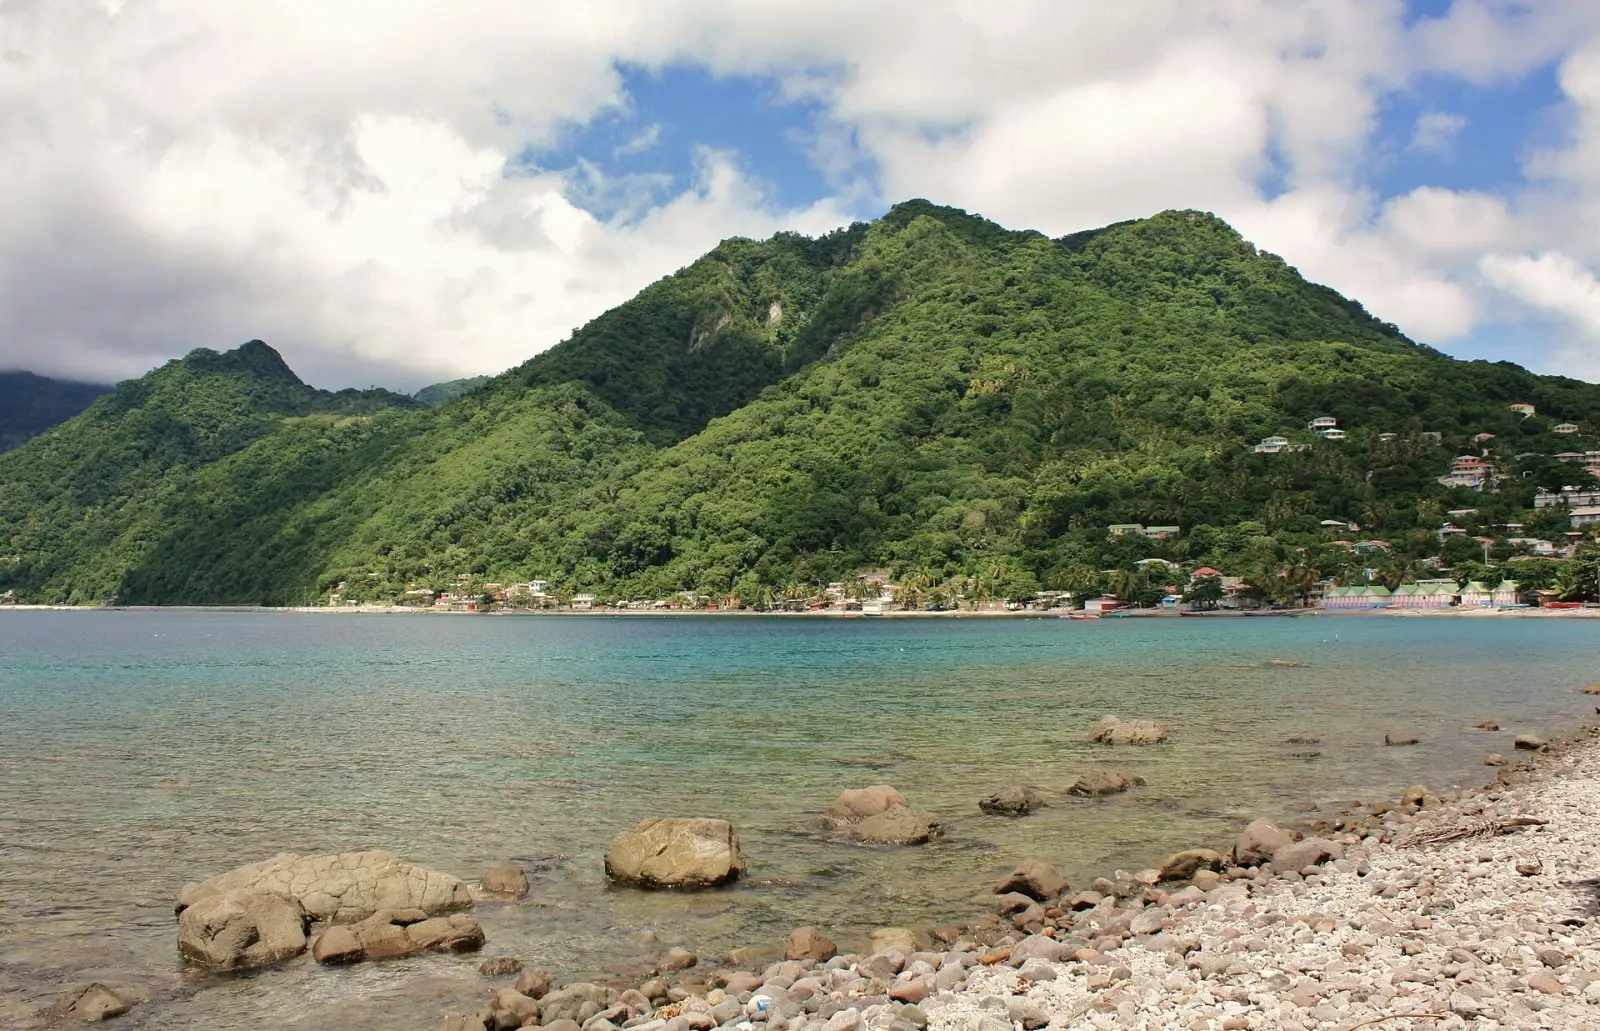
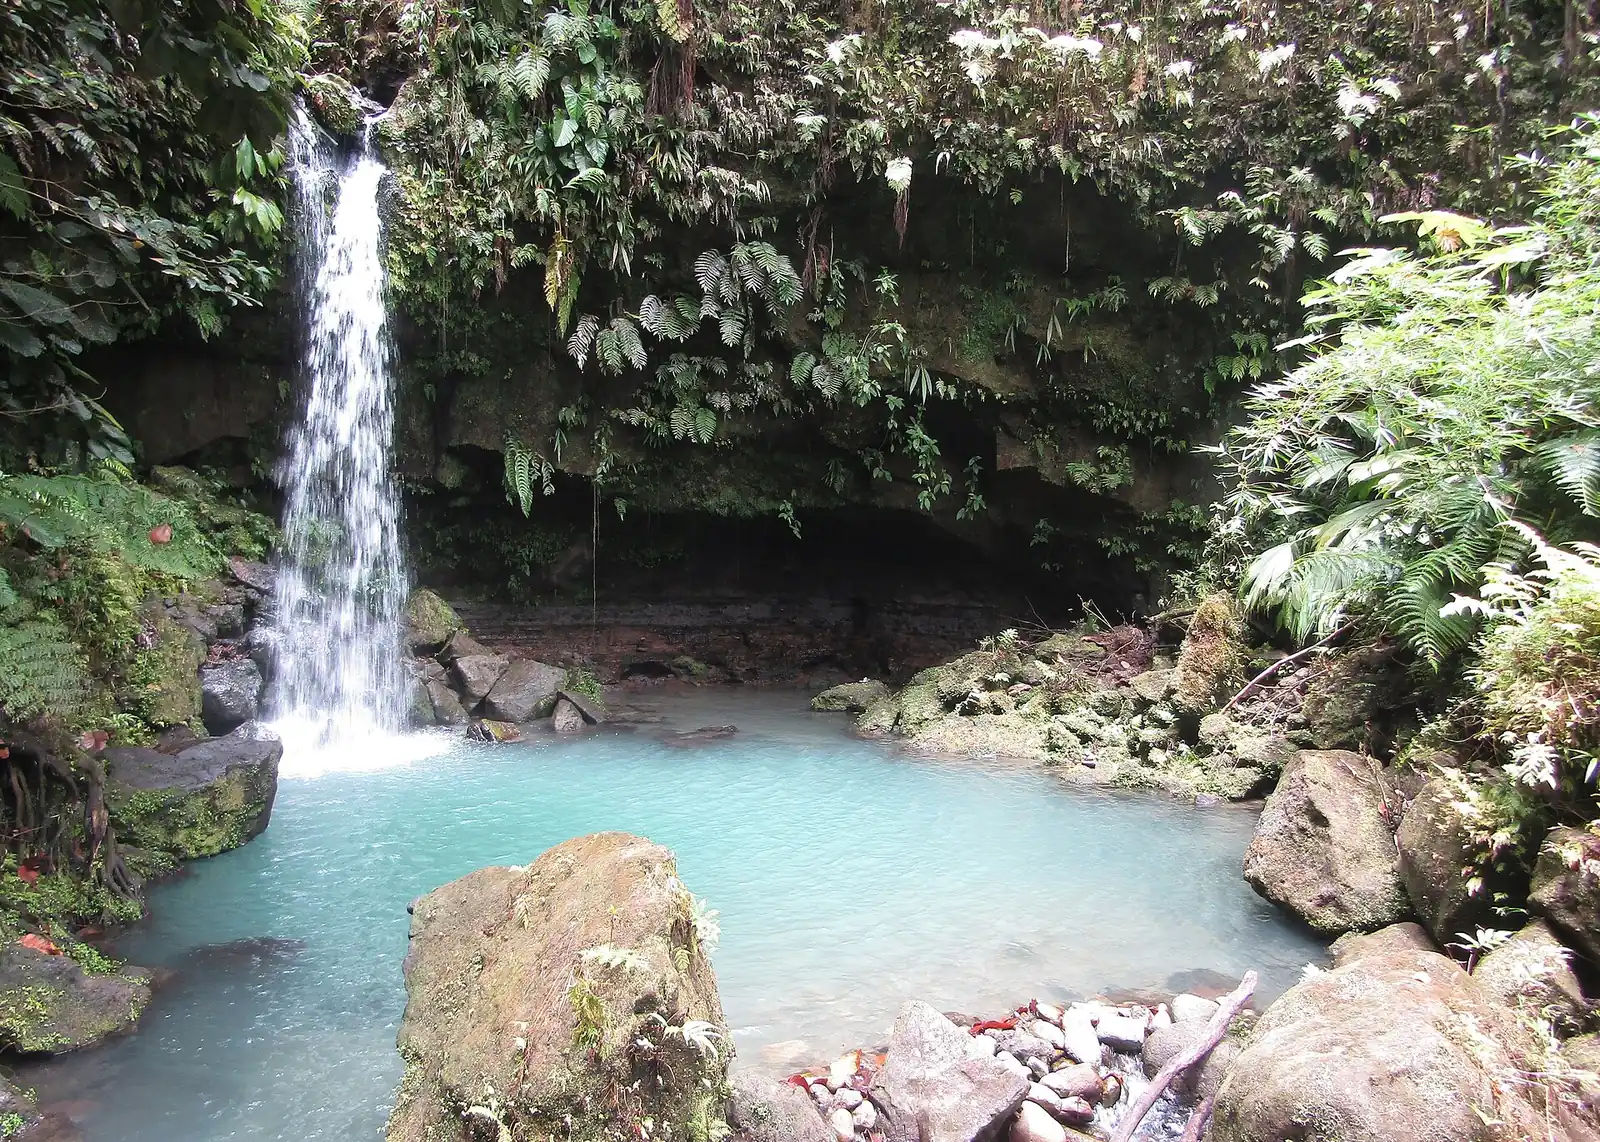
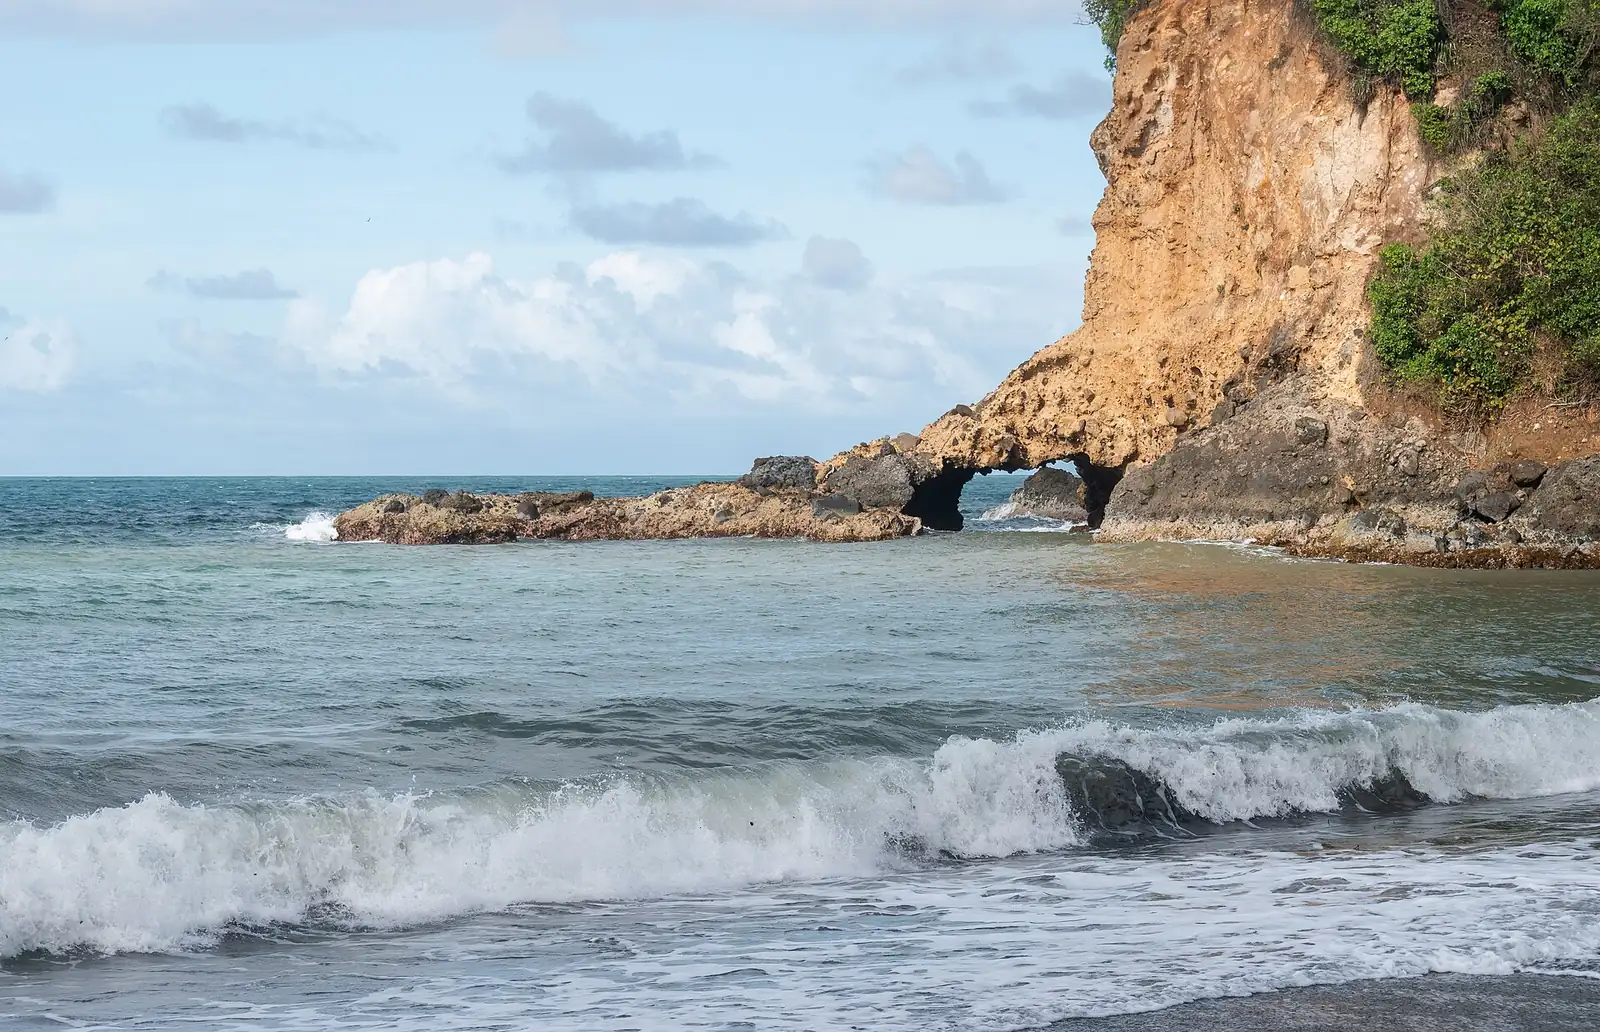
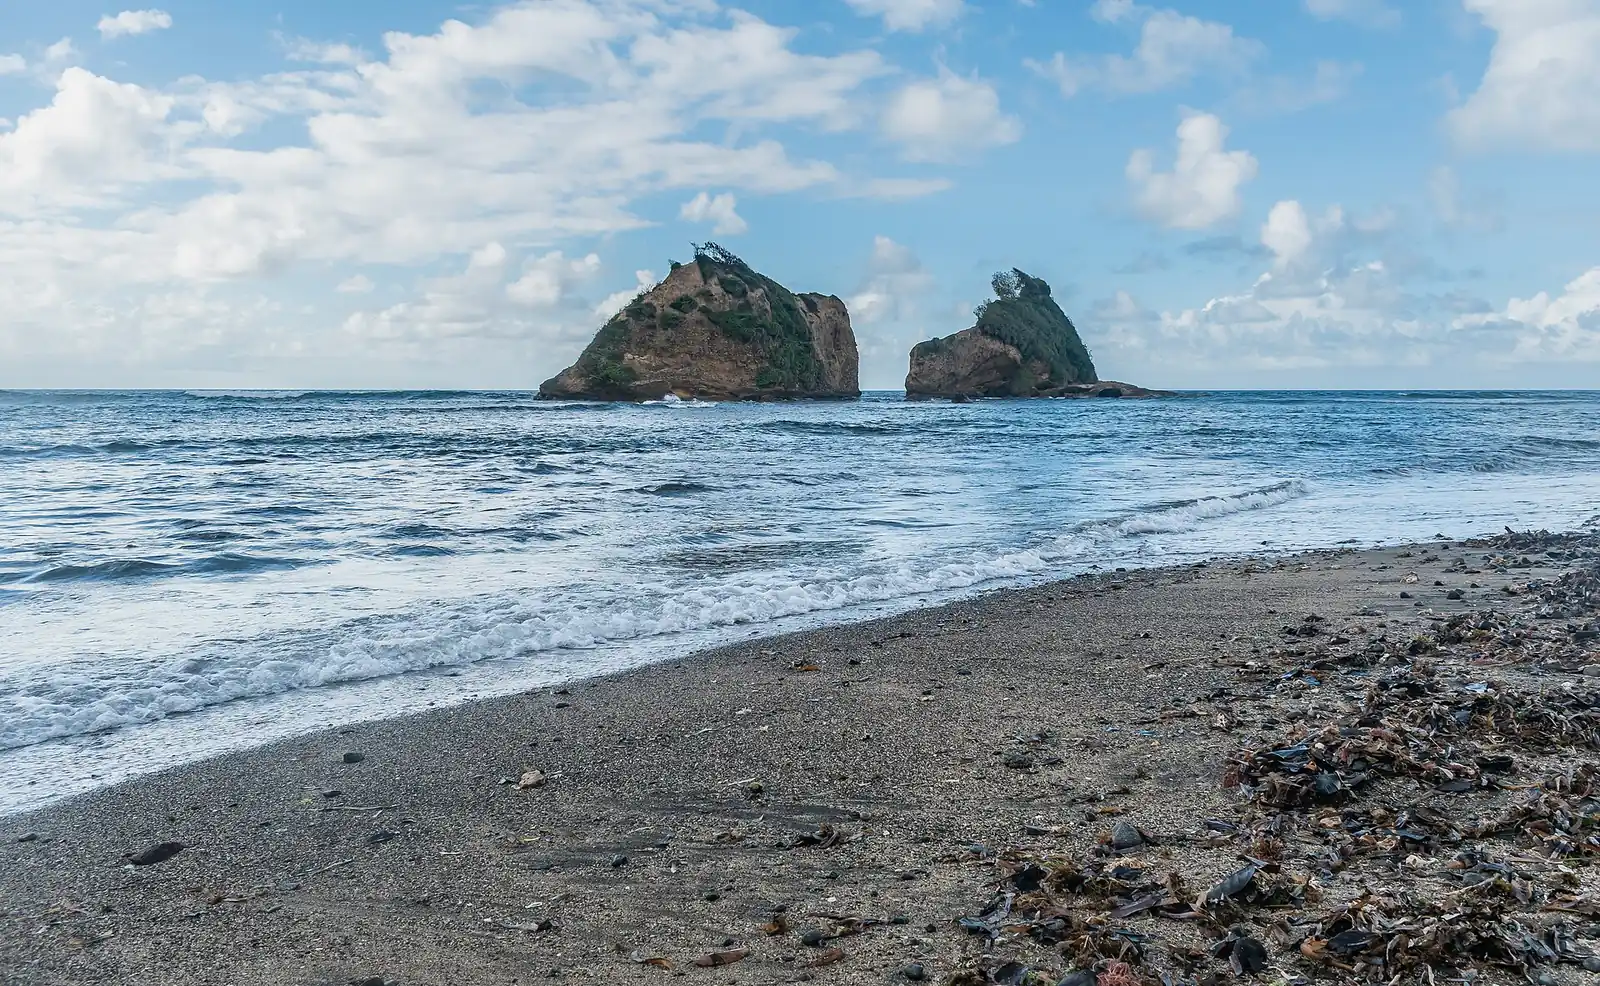
Dominica in pictures
Path to permanent residence · 1
- PR after 5 years · Permanent residence
Arriving in Dominica: first steps
- Check if you need health insurance or other cover for your stay, as the records do not specify requirements.
- Have proof of your address in Dominica ready for official processes.
- Register with the relevant authorities if your route requires it, such as the Labour Division for a work permit.
- Keep your approval letter and payment receipts safe, as you may need them for arrival and later steps.
Questions people ask
What is the Dominica digital nomad visa income requirement in 2026?
Dominica has 1 nomad or remote-work visa. WIN nomad visa asks for an income of at least $50,000 a year and gives a first stay of 1.5 years.
How much do you need to invest for residency in Dominica?
Dominica has 2 investor routes. Citizenship · $200k property asks for an investment of at least $200,000. Citizenship · EDF $200k asks for an investment from $200,000.
What work visas does Dominica offer foreigners?
Dominica has 1 work visa. Work permit gives a first stay of 1 year that can be renewed.
Does Dominica have a special tax regime for new residents?
Yes: Dominica: resident but not ordinarily resident individuals taxed on foreign-source income only when received. Under section 8(2) of the Income Tax Act, an individual who is resident but not ordinarily resident in Dominica has assessable income that includes income accrued from sources outside Dominica only to the extent that such income is received in Dominica. It is separate from the visa and has its own conditions.
Compare with
≈ USD figures are approximate: daily reference rates from ExchangeRate-API, dated 12 Oct 2026, refreshed when the site is updated.
Ask the AI about Dominica AI
An AI assistant answers from the published records on this page and cites them. It can't assess your personal eligibility. Don't include personal details.