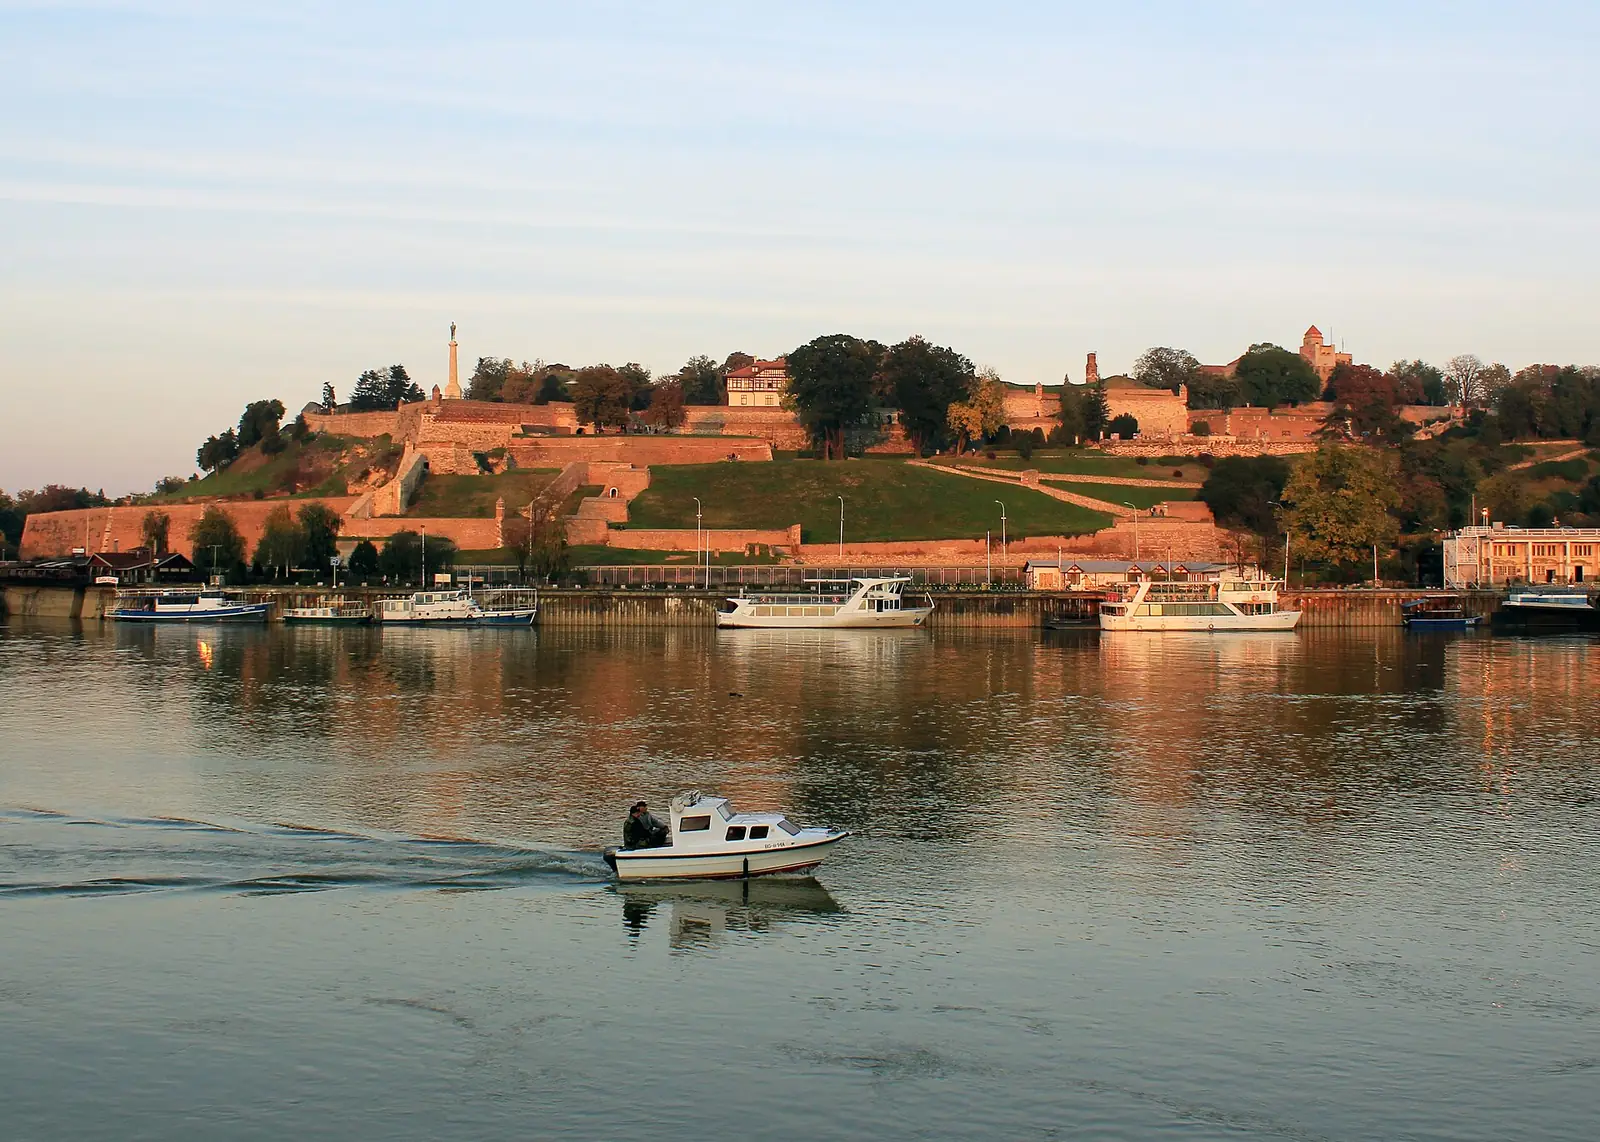
Moving to Serbia
12 ways to move to Serbia in our guide: 2 investor routes, 3 business / startup routes, 3 work visas, 1 student visa, 1 route by nationality or ancestry, 2 spouse visas.
No digital nomad visa. Tax for newcomers: Personal income tax: residence test and rates, 10% tax. Checked against official sources on .
Serbia offers a range of residence routes for foreigners, from property ownership and investment to work, business, study and talent. Each route has its own conditions, and the records here set out what is required for each.
Investing · 2

Property owner residence
First stay: 3 yrs
Company investor residence
Savings needed: €50k+ ≈ $56k
Business / Startup · 3

Independent professional
First stay: 3 yrs
Self-employed permit
First stay: 3 yrs
Startup founder residence
Income needed: RSD 1M+ ≈ $9,530
Work · 3

Intra-company transfer
First stay: 3 yrs
Work permit (single permit)
First stay: 3 yrs
Talent residence
First stay: 1 yr
Student · 1

Student residence
First stay: 3 yrs
For your nationality or ancestry · 1

Open only to citizens of certain countries or to people with family roots here. Unlike free movement, each needs an application.
Serbian origin residence
First stay: 1 yr
Spouse visas · 2

For people married to, or in a partnership with, a citizen or permanent resident.
Spouse of a resident
First stay: 3 yrs
Spouse of a citizen
First stay: 3 yrs
Free movement and visa-free stays · 1
Open Balkan · Lets you live here
Open to 2 passports: Albania, North Macedonia.
Tax
Residents are taxed on income earned in Serbia and abroad; salary and self-employment income are taxed at a flat rate, while capital income, capital gains, royalties and property income have their own rates. Non-residents are taxed on Serbian-source income. Registered entrepreneurs may elect to pay a flat-rate tax on a lump-sum income set by the tax authority instead of on actual income.
Standard rules
Personal income tax: residence test and rates
10% tax
Details
- On: Residents: income by category earned in Serbia and abroad
- Who: Resident: domicile or centre of business and life interests in Serbia
- Limit: RSD 34k/mo ≈ $330
Residents are taxed on income earned in Serbia and in another state; salary and self-employment income are taxed at 10%, capital income and capital gains at 15%, royalties and property income at 20%, with a tax credit for income tax paid abroad up to the Serbian tax on that income.
Taxed on
Residents: income by category earned in Serbia and abroad. Non-residents: Serbian-source income.
Who it applies to
- Resident: domicile or centre of business and life interests in Serbia, or 183 or more days (any partial day counts, transit excluded) in a 12-month period beginning or ending in the tax year.
- Foreign tax credit (Art. 12): a resident who earns income in another state, on which tax was paid there, receives a credit equal to the foreign tax, not above the Serbian tax on that income.
- Salary tax base is the salary minus a non-taxable amount of RSD 34,221 (≈ $330) a month for full-time work in 2026; the amount is RSD 37,369 (≈ $360) a month from 1 January 2027.
- Mandatory social contributions on salary: pension and disability 14% employee and 10% employer, health 5.15% each, unemployment 0.75% employee.
Exclusions
- A person who was not present in the tax year and has no domicile or centre of interests in Serbia is not resident for that year.
Limits
- RSD 34,221 a month (≈ $330) · Non-taxable amount deducted from full-time salary in 2026; RSD 37,369 (≈ $360) from 1 January 2027.
Days in the country
- At least 183 days in 12-month period beginning or ending in the tax year · Presence in Serbia for 183 or more days, continuous or interrupted.
Visas
Tax residence arises from presence or interests, not from a residence permit.
Other taxes
Social contributions on salary and self-employment (pension and disability, health, unemployment) and the annual personal income tax on large income are separate; contribution rates on salary are 24% pension, 10.3% health and 0.75% unemployment in total.
Checked against official sources on , some details partly verifiedChange log
Special regime
Flat-rate (lump-sum) taxation of entrepreneurs
10% tax
Details
- Who: Entrepreneur registered with the competent register who applies to the tax authority
- Limit: RSD 6M/yr ≈ $57k
Registered entrepreneurs may elect to pay 10% self-employment income tax on a lump-sum income set by the tax authority instead of on actual income.
Taxed on
Lump-sum income determined by decision of the tax authority from average monthly salary, number of employees and an activity coefficient (Art. 40-41).
Who it applies to
- Entrepreneur registered with the competent register who applies to the tax authority.
Exclusions
- Advertising and market research; wholesale and retail trade, hotels and restaurants, financial intermediation and real-estate activities (kiosk trade excepted); businesses with investment by other persons; entrepreneurs registered for VAT.
Limits
- RSD 6,000,000 a year (≈ $57,200) · Total turnover in the previous year (or planned turnover when starting) above this removes the right to lump-sum taxation.
Visas
Requires a registered entrepreneur status; a foreigner needs a residence ground such as self-employment.
Other taxes
Social contributions are separate.
Checked against official sources on , some details partly verifiedChange log
Special regime
Newly settled taxpayer: 70% reduction of the salary tax base and contribution base for five years
Tax relief
Details
- On: Salary from a permanent employment contract with a qualifying employer
- Who: Has not mainly lived in Serbia in the 24 months before signing the employment contract
- Limit: RSD 440k/mo ≈ $4,190
A person who has not mainly lived in Serbia in the previous 24 months (or is under 40 and returns from studies abroad), and is hired on a permanent contract by a qualifying Serbian employer for a role that needs special expertise, pays salary tax and contributions on a base reduced by 70% for five years.
Taxed on
Salary from a permanent employment contract with a qualifying employer, after the standard non-taxable deduction (Art. 15a), reduced by 70%; the contribution base is the salary reduced by 70%.
Who it applies to
- Has not mainly lived in Serbia in the 24 months before signing the employment contract; or is under 40 and lived mainly abroad in the previous 12 months for further education or training.
- Is hired on a permanent contract by a Serbian-resident employer that is not related to the person's previous employer.
- The expertise condition is treated as met when monthly salary is above RSD 439,692 (≈ $4,190) (first group) or above RSD 293,128 (≈ $2,790) (second group, under 40 returning from studies).
- Settles in Serbia and is a tax resident by centre of business and life interests and a resident for treaty purposes.
- The relief runs five years from signing the contract while the conditions continue, including after a change of employer.
Exclusions
- The wording covers salary under a permanent employment contract; fixed-term contracts are not named.
Limits
- RSD 439,692 a month (≈ $4,190) · Salary above which the role and expertise condition is treated as met (first group: no mainly Serbian residence in the previous 24 months).
- RSD 293,128 a month (≈ $2,790) · Salary above which the role and expertise condition is treated as met (second group: under 40, studied or trained abroad in the previous 12 months).
Tax residence
The person must settle in Serbia with the employment or within a reasonable time after and be a tax resident by centre of business and life interests; the relief starts with the first salary for the month in which the competent authority's proof is obtained.
Visas
Not tied to a permit; a foreigner needs a residence and work ground, for example a single permit on employment.
Other taxes
The 10% salary tax and contributions (14% employee and 10% employer pension, 5.15% health each, 0.75% unemployment) apply to the reduced base; value added tax and other taxes are separate.
Checked against official sources on , some details partly verifiedChange log
Checked against official sources on Change log
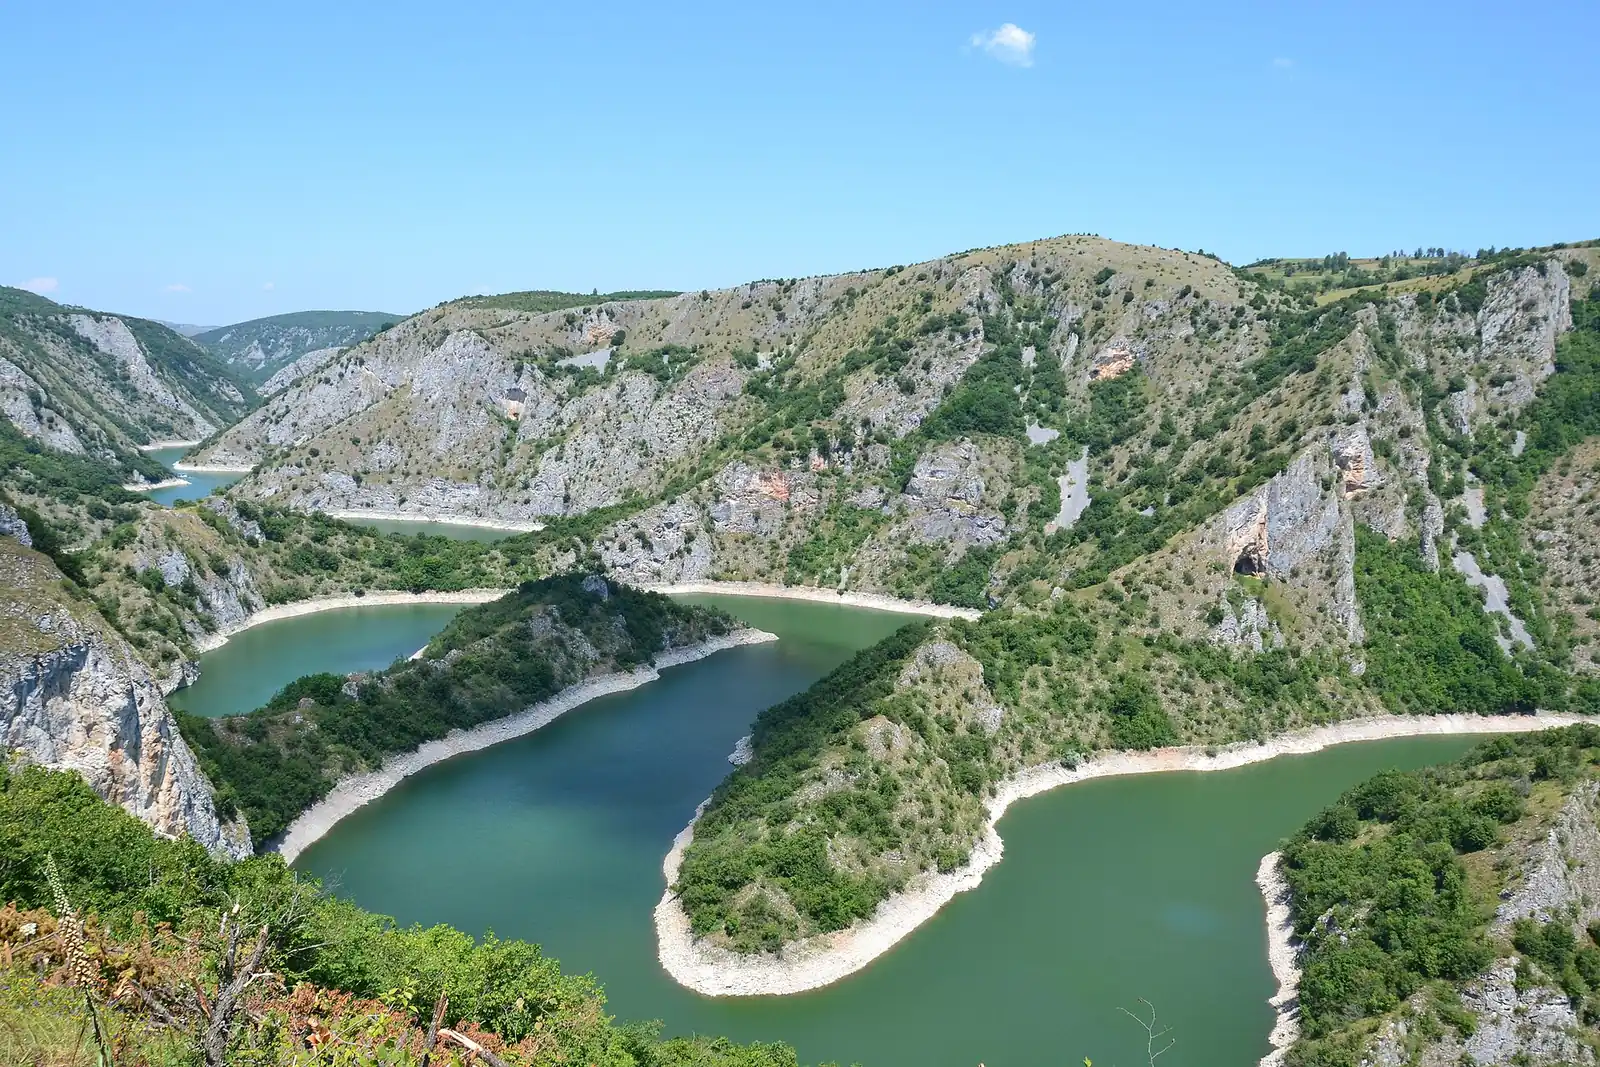
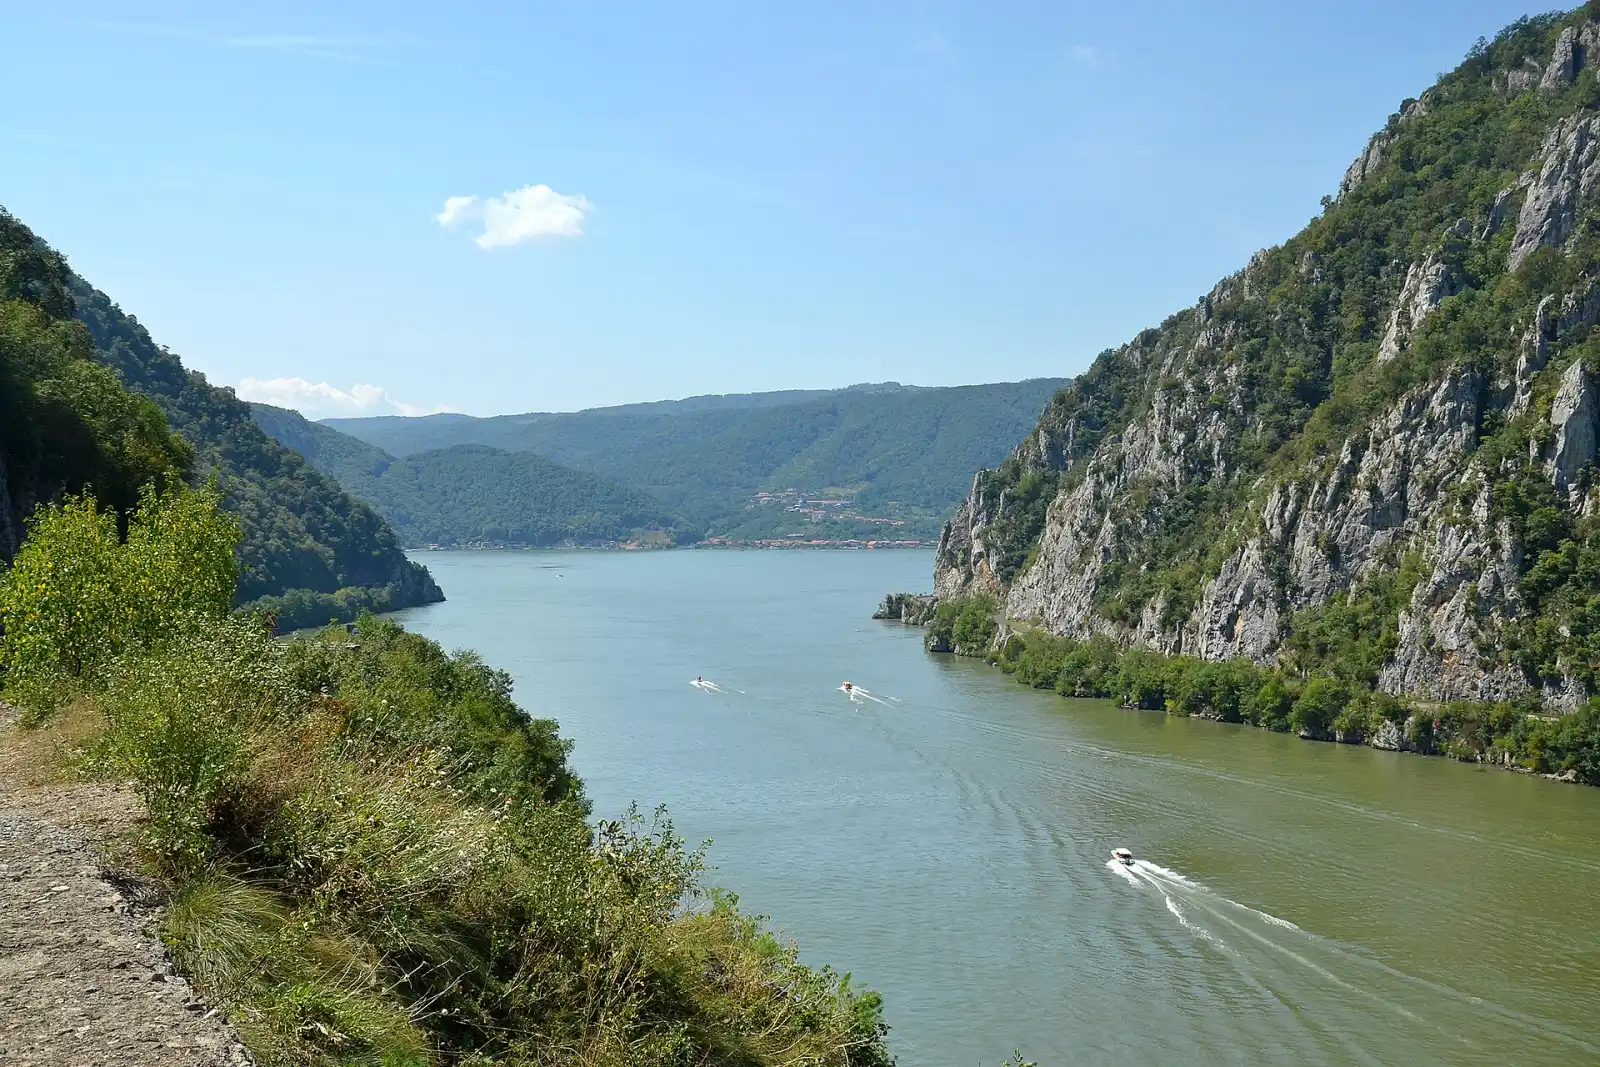
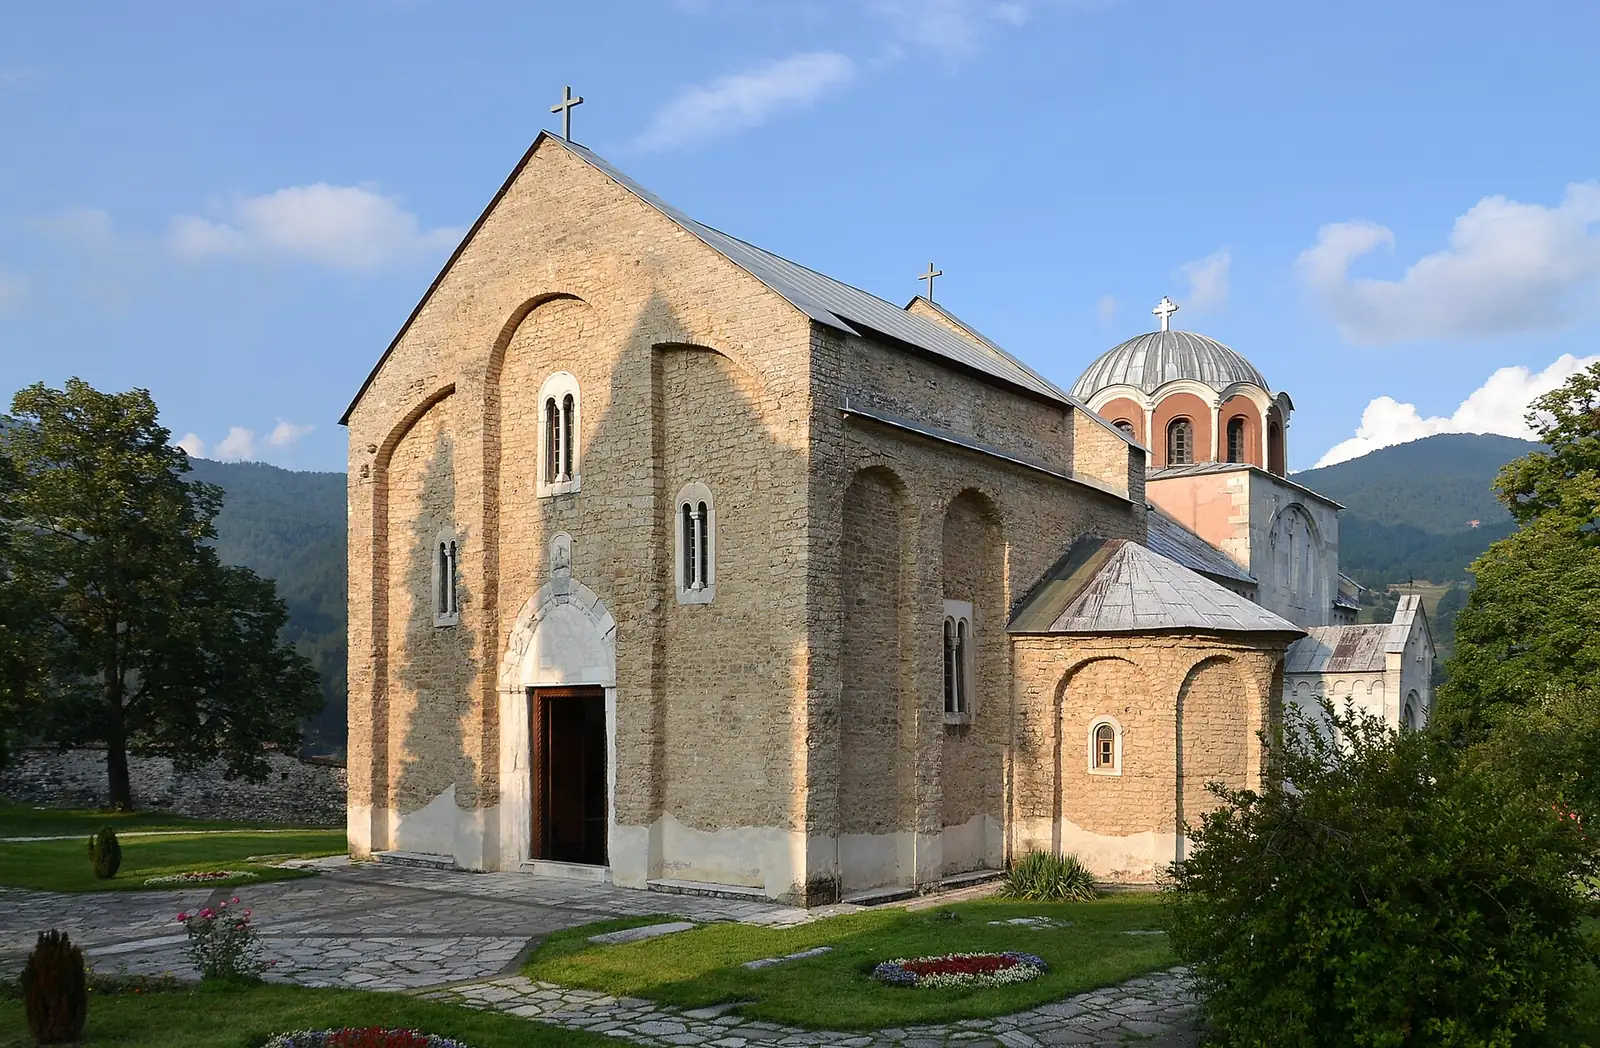
Serbia in pictures
Arriving in Serbia: first steps
- Arrange health insurance that meets the requirement for your permit route.
- Register a residential address in Serbia, as proof of registered address is required for most applications.
- Open a Serbian bank account if your route requires proof of funds on a Serbian bank account.
- Gather the standard application documents: valid passport, proof of subsistence, proof of health insurance, registered address and the administrative fee.
- File your application on the Foreign Nationals Portal or at the police directorate, depending on your route.
- If you are employed, your employer handles the labour market test and electronic filing; proof of subsistence and health insurance is not filed by employed foreigners or their immediate family.
Questions people ask
How much do you need to invest for residency in Serbia?
Serbia has 2 investor routes. Property owner residence gives a first stay of 3 years that can be renewed. Company investor residence asks for savings of at least EUR 50,000 (≈ $55,900) and gives a first stay of 6 months that can be renewed.
Can I move to Serbia by starting a business?
Serbia has 3 business or startup routes. Independent professional gives a first stay of 3 years that can be renewed. Self-employed permit gives a first stay of 3 years that can be renewed. Startup founder residence asks for an income of at least RSD 1,000,000 (≈ $9,530) and gives a first stay of 1 year that can be renewed.
What work visas does Serbia offer foreigners?
Serbia has 3 work visas. Intra-company transfer gives a first stay of 3 years that can be renewed. Work permit (single permit) gives a first stay of 3 years that can be renewed. Talent residence gives a first stay of 1 year that can be renewed.
How do I get a student visa for Serbia?
Serbia has 1 student visa. Student residence gives a first stay of 3 years that can be renewed.
Can my nationality or ancestry give me residence in Serbia?
Yes. Serbia has 1 route by nationality or ancestry. Serbian origin residence gives a first stay of 1 year that can be renewed.
Can I join my spouse or partner in Serbia?
Yes. Serbia has 2 spouse visas. Spouse of a resident gives a first stay of 3 years that can be renewed. Spouse of a citizen gives a first stay of 3 years that can be renewed.
Compare with
≈ USD figures are approximate: daily reference rates from ExchangeRate-API, dated 12 Oct 2026, refreshed when the site is updated.
Ask the AI about Serbia AI
An AI assistant answers from the published records on this page and cites them. It can't assess your personal eligibility. Don't include personal details.
Sources (5)
Official sources
- Temporary residence: grounds, single permit to reside and work, required documents · Ministry of Interior of the Republic of Serbia · checked 2026-10-10
- Law on Foreigners (Sl. glasnik RS 24/2018, 31/2019, 62/2023), Serbian text · Paragraf (reprint of the Official Gazette text) · checked 2026-10-10
- Temporary residence: bases for approval · Government of the Republic of Serbia (Welcome to Serbia portal) · checked 2026-10-10
- Digital nomads in Serbia · Welcome to Serbia (Government of the Republic of Serbia) · checked 2026-10-12
- Frequently asked questions: temporary residence and single permit fees · Government of the Republic of Serbia (Welcome to Serbia portal) · checked 2026-10-11