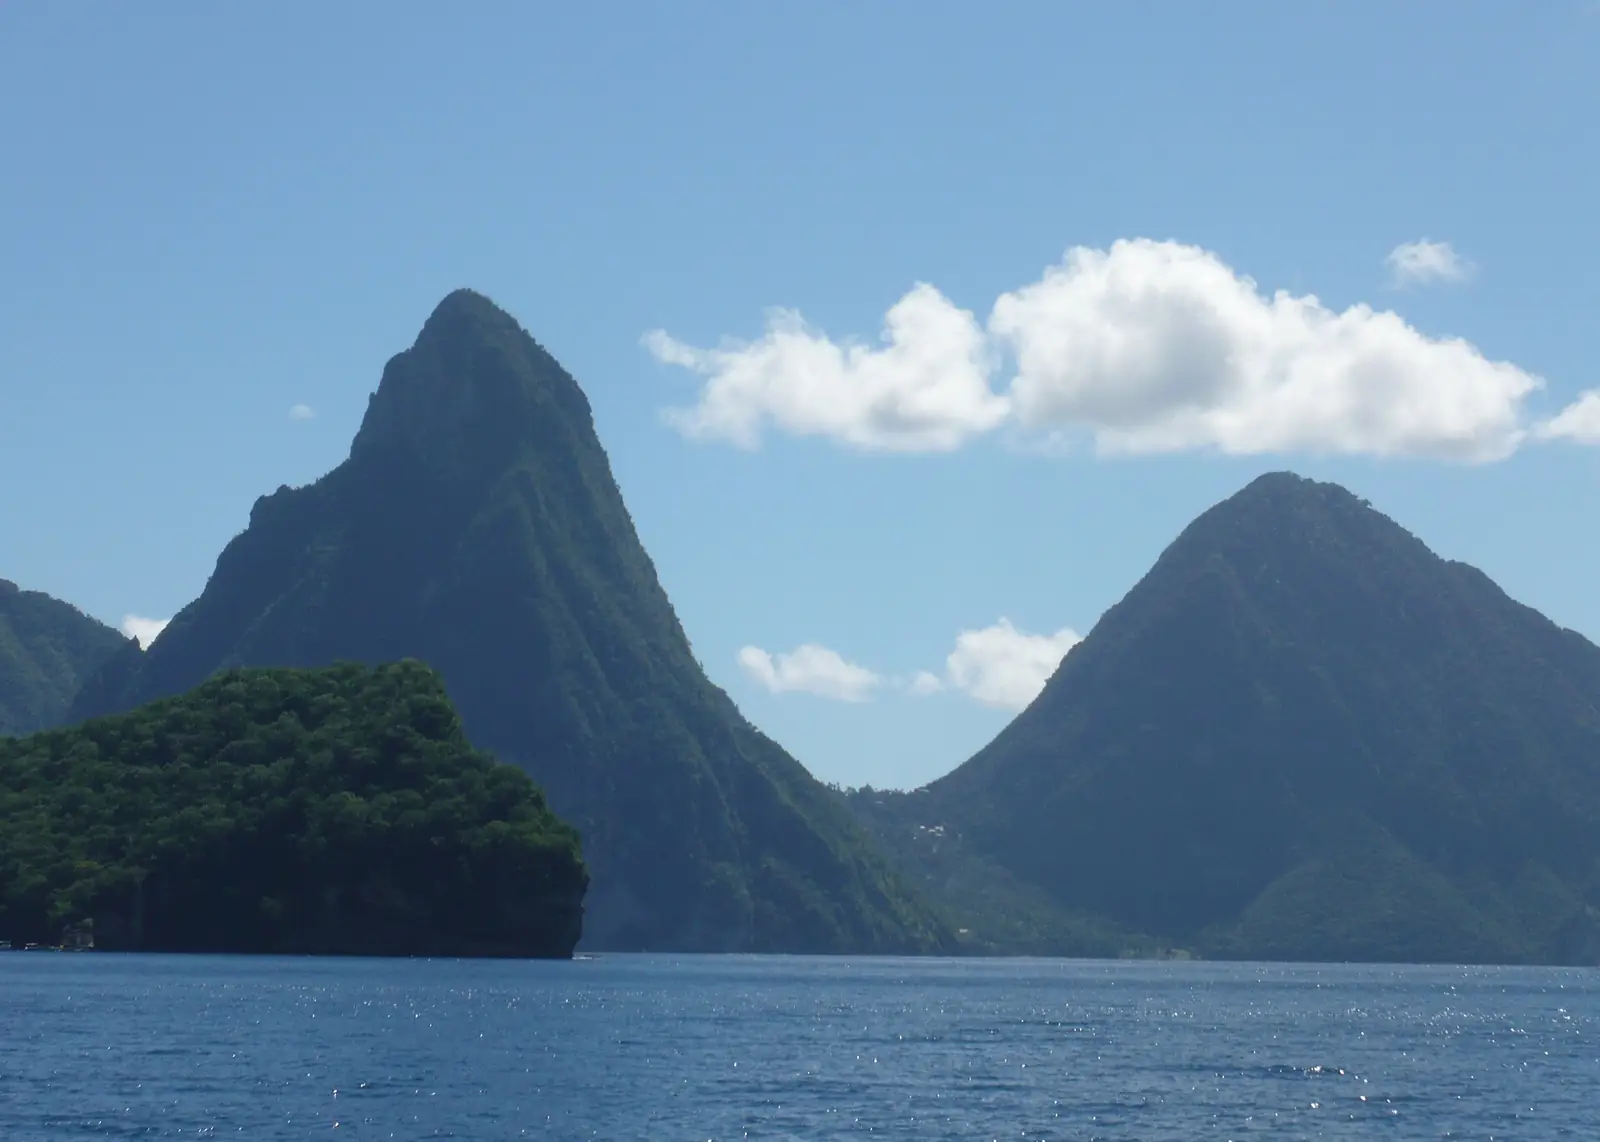
Moving to Saint Lucia
7 ways to move to Saint Lucia in our guide: 6 investor routes, 1 work visa.
No digital nomad visa. Smallest investment: Citizenship · NEF $240k, $240k+. Tax for newcomers: Saint Lucia: resident but not ordinarily resident individuals taxed on foreign-source income only when received, Remittance basis. Checked against official sources on .
Saint Lucia is a small island nation where the main long-stay route for newcomers is citizenship by investment. The programmes are run through licensed Authorised Agents, and the government approves a limited number of applications each year.
Investing · 6

Citizenship
Investment needed: from $240k
Work · 1

Work permit
First stay: 1 yr
Free movement and visa-free stays · 1
CARICOM free movement · Lets you live here
Open to 11 passports: Antigua and Barbuda, Barbados, Belize, Dominica, Grenada, Guyana, Jamaica, Saint Kitts and Nevis, Suriname, Trinidad and Tobago, VC.
Tax
Saint Lucia taxes residents on a progressive scale, and the records set out the bands and allowances. If you are resident but not ordinarily resident, foreign-source income is taxed only to the extent you receive it in Saint Lucia; if you are ordinarily resident, all sources in or out of Saint Lucia are taxed. Residency turns on days present or on having a permanent place of abode, so your tax position follows your facts, not your citizenship route.
Standard rules
Personal income tax bands and allowances
30% tax
Details
- On: Chargeable income after allowances
- Limit: XCD 25k/yr ≈ $9,260
Chargeable income is taxed at 15% to EC$15,000, 20% from EC$15,001 to EC$30,000 and 30% above EC$30,000, after a EC$25,000 personal allowance for income years 2023 to 2025.
Taxed on
Chargeable income after allowances (aggregate allowances and deductions capped at EC$30,000, personal and medical allowances outside the cap)
Exclusions
- From income year 2025 pension income (approved pension fund, employer, government or NIC pension) is fully exempt.
Limits
- XCD 25,000 a year (≈ $9,260) · Personal allowance for income years 2023 to 2025.
- XCD 15,000 a year (≈ $5,560) · Upper limit of the 15% band; 20% applies to EC$15,001 to EC$30,000 and 30% above EC$30,000.
Visas
Citizenship by investment confers no tax relief; the NEF and other options are not tax benefits.
Other taxes
2025 changes raised child allowances to EC$5,000 (EC$10,000 for tertiary), the dependent relative allowance to EC$5,000 and the mortgage interest cap to EC$40,000. The Inland Revenue brochure gives the EC$25,000 personal allowance for income years 2023 to 2025; the allowance for income year 2026 was not found on an official page on 12 October 2026.
Checked against official sources on , some details partly verifiedChange log
Special regime
Saint Lucia: resident but not ordinarily resident individuals taxed on foreign-source income only when received
Tax relief
Details
- On: Foreign-source income is taxed only to the extent received in Saint Lucia
Under section 8(2) of the Income Tax Act, an individual who is resident but not ordinarily resident in Saint Lucia has assessable income that includes income accrued from sources outside Saint Lucia only to the extent that such income is received in Saint Lucia.
Taxed on
Foreign-source income is taxed only to the extent received in Saint Lucia; Saint Lucian-source income is taxed at the progressive rates.
Who it applies to
- Individual resident by the 183-day test or continuity rule without a permanent place of abode in Saint Lucia (not ordinarily resident).
Exclusions
- Ordinarily resident individuals (permanent place of abode in Saint Lucia and presence for some period in the income year) are taxed on all sources in or out of Saint Lucia (s.8(1)(a)).
Days in the country
- At least 183 days in year of income · Resident in Saint Lucia if physically present for not less than 183 days in the year of income (para (a)(ii) of resident in Saint Lucia); a permanent place of abode with some presence makes an individual ordinarily resident (para (a)(i))
Tax residence
Resident: 183 days or more in the year of income, or permanent place of abode plus some presence; ordinarily resident is the permanent-place-of-abode limb.
Visas
The rule depends on tax residence and abode, not on a visa category; the statute copy shows the law as at 31 December 2023.
Other taxes
Company income from a source outside Saint Lucia in accordance with section 10A is excluded from a resident company's assessable income (s.8(3)).
Checked against official sources on , some details partly verifiedChange log
Standard rules
Saint Lucia individual income tax: rates and allowances
Details
- On: Chargeable income: residents on all sources in or out of Saint Lucia
- Limit: XCD 15k/yr ≈ $5,560
Residents are taxed at 15% on chargeable income to XCD 15,000, (≈ $5,560) 20% from XCD 15,001 (≈ $5,560) to 30,000 and 30% above XCD 30,000 (≈ $11,100) under the bands introduced by Income Tax Amendment No. 19 of 2023, with a XCD 25,000 (≈ $9,260) personal allowance and a XCD 30,000 (≈ $11,100) cap on aggregate allowances and deductions; ordinarily resident individuals are taxed on all sources in or out of Saint Lucia.
Taxed on
Chargeable income: residents on all sources in or out of Saint Lucia (ordinarily resident) or Saint Lucian-source plus foreign-source income received in Saint Lucia (resident not ordinarily resident); non-residents on Saint Lucian sources.
Who it applies to
- Resident individuals may claim the XCD 25,000 (≈ $9,260) personal allowance, which is outside the XCD 30,000 (≈ $11,100) cap for income years 2023 to 2025.
Exclusions
- Aggregate allowances and deductions are capped at XCD 30,000 (≈ $11,100) from 1 January 2023, except the personal allowance, medical expenses and solar photovoltaic costs for income years 2023 to 2025.
Limits
- XCD 15,000 a year (≈ $5,560) · Chargeable income up to this amount taxed at 15%; 20% from 15,001 to 30,000
- XCD 30,000 a year (≈ $11,100) · Chargeable income above this amount taxed at 30%; also the cap on aggregate allowances and deductions
- XCD 25,000 a year (≈ $9,260) · Personal allowance for resident individuals from income year 2023
Days in the country
- At least 183 days in year of income · Resident in Saint Lucia if physically present for not less than 183 days in the year of income (para (a)(ii) of resident in Saint Lucia); a permanent place of abode with some presence makes an individual ordinarily resident (para (a)(i))
Tax residence
183 days in the year of income makes an individual resident; ordinarily resident status turns on a permanent place of abode.
Visas
Tax residence is independent of immigration or citizenship-by-investment status; bands shown are those published for the 2023 amendment and the brochure covers income years from 2023.
Other taxes
Returns are filed for the calendar year; every resident individual with income over XCD 17,400 (≈ $6,440) must file, and all self-employed individuals must file.
Checked against official sources on , some details partly verifiedChange log
Checked against official sources on Change log
Saint Lucia in pictures
Arriving in Saint Lucia: first steps
- Arrange health and police certificates and a banker's reference, as these are required for the investment routes.
- Appoint a licensed Authorised Agent if you are applying through citizenship by investment.
- Keep your address and residency records in order, since residency and genuine-link requirements now apply.
- If you are taking up employment, wait until the work permit is approved before starting work.
- Register your property interest within the stated window if you invest in built real estate.
- Provide biometric data as part of the application process.
Questions people ask
How much do you need to invest for residency in Saint Lucia?
Saint Lucia has 6 investor routes. Citizenship · $500k home asks for an investment of at least $500,000. Citizenship · $300k hotel unit asks for an investment of at least $300,000. Citizenship · $250k projects asks for an investment of at least $250,000.
What work visas does Saint Lucia offer foreigners?
Saint Lucia has 1 work visa. Work permit gives a first stay of 1 year that can be renewed.
Does Saint Lucia have a special tax regime for new residents?
Yes: Saint Lucia: resident but not ordinarily resident individuals taxed on foreign-source income only when received. Under section 8(2) of the Income Tax Act, an individual who is resident but not ordinarily resident in Saint Lucia has assessable income that includes income accrued from sources outside Saint Lucia only to the extent that such income is received in Saint Lucia. It is separate from the visa and has its own conditions.
Compare with
≈ USD figures are approximate: daily reference rates from ExchangeRate-API, dated 12 Oct 2026, refreshed when the site is updated.
Ask the AI about Saint Lucia AI
An AI assistant answers from the published records on this page and cites them. It can't assess your personal eligibility. Don't include personal details.
Sources (6)
Official sources
- Investment options (amounts and fees) · Citizenship by Investment Programme, Saint Lucia · checked 2026-10-12
- FAQs: eligibility and qualifying dependents · Citizenship by Investment Programme, Saint Lucia · checked 2026-10-10
- Citizenship by Investment (Amendment) Regulations, S.I. No. 57 of 2026 · Government of Saint Lucia (Extraordinary Gazette, 23 March 2026) · checked 2026-10-10 · published 2026-03-23
- Immediate release: stance on applications from nationals of the Russian Federation and Belarus · Citizenship by Investment Programme, Saint Lucia · checked 2026-10-11
- Citizenship by Investment (Amendment) Act, No. 22 of 2025 · Government of Saint Lucia · checked 2026-10-10 · published 2025-11-03
- Saint Lucia launches immersive extended stay programme (Live it) · Government of Saint Lucia · checked 2026-10-12 · published 2021