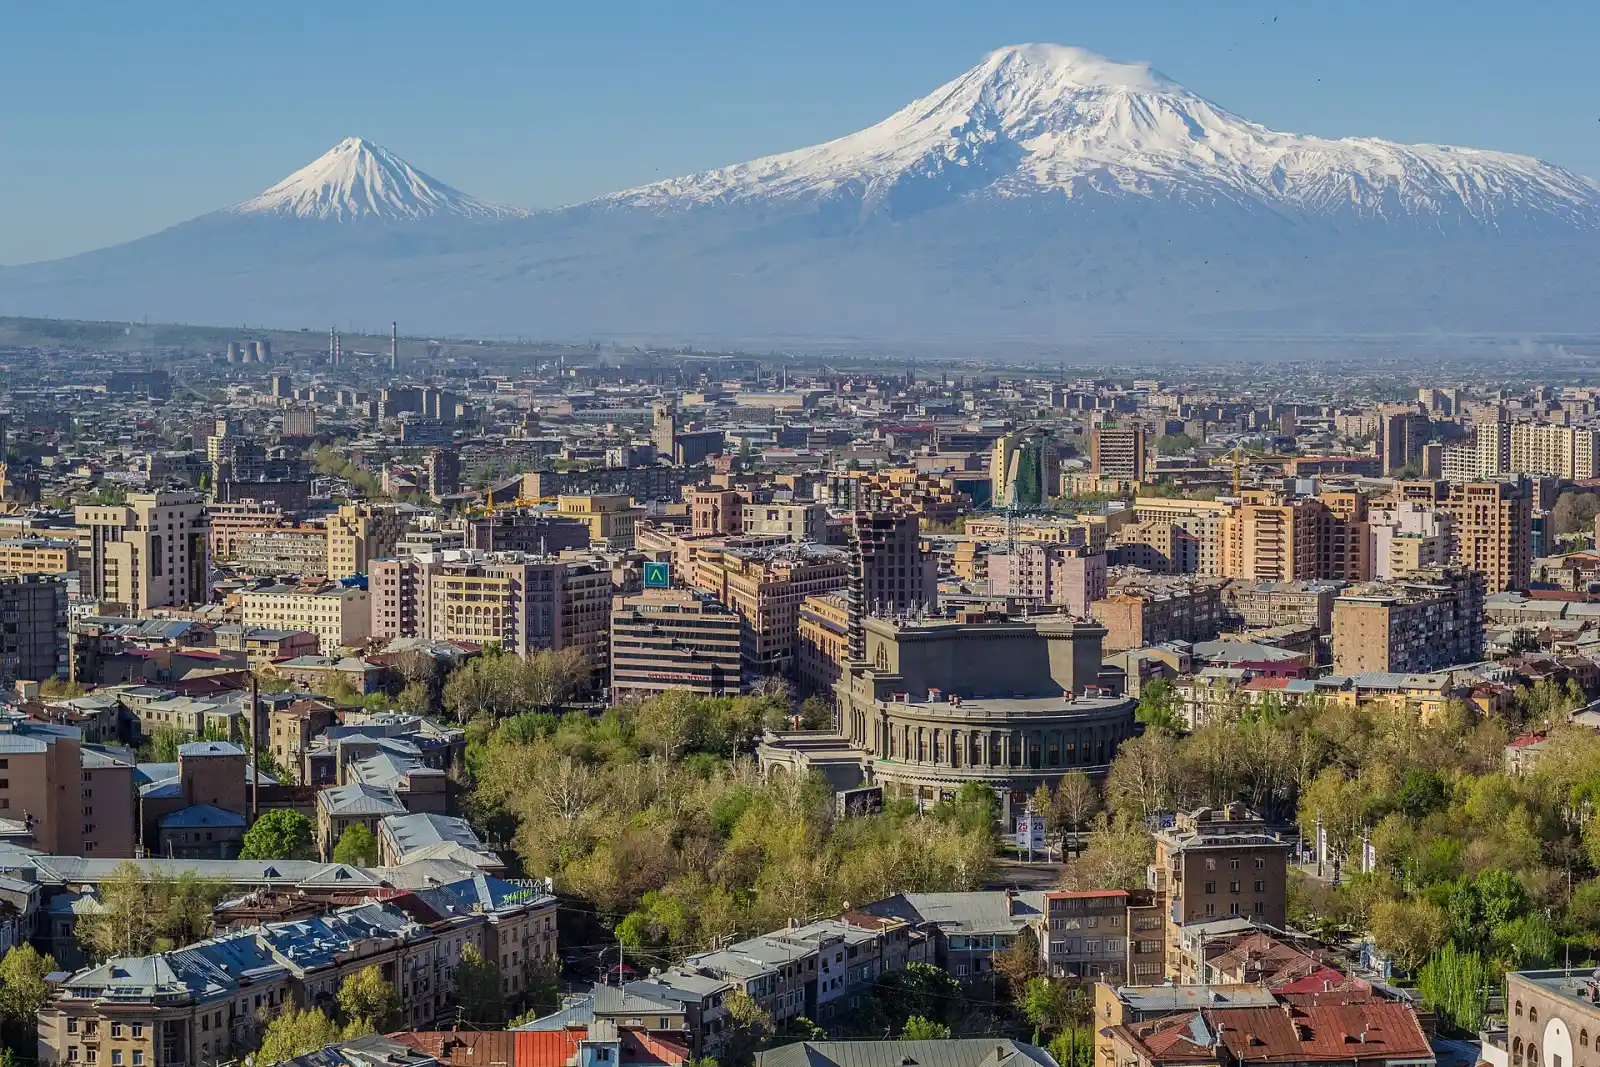
Moving to Armenia
8 ways to move to Armenia in our guide: 1 business / startup route, 1 work visa, 1 student visa, 3 routes by nationality or ancestry, 2 spouse visas.
No digital nomad visa. Checked against official sources on .
Armenia offers a few clear residence routes if you have a reason to be there: starting a business, taking a job, or studying. The paperwork is handled in person, and the records show that each route has its own ground that you need to prove with documents.
Business / Startup · 1

Entrepreneur residence
First stay: 1 yr
Work · 1

Work permit
First stay: 1 yr
Student · 1

Student residence
First stay: 1 yr
For your nationality or ancestry · 3

Open only to citizens of certain countries or to people with family roots here. Unlike free movement, each needs an application.
Armenian citizenship by origin
Special residence status
First stay: 10 yrs
Armenian origin residence
First stay: 1 yr
Spouse visas · 2

For people married to, or in a partnership with, a citizen or permanent resident.
Spouse of a citizen
First stay: 1 yr
Spouse of a resident
First stay: 1 yr
Free movement and visa-free stays · 2
Eurasian Union free movement · Lets you live here
Open to 4 passports: Belarus, Kazakhstan, Kyrgyzstan, Russia.
Visa-free stay (6 months) · Up to 6 months without a visa
Open to 45 passports: Andorra, Australia, Austria, Belgium, Bulgaria, Croatia, Cyprus, Czechia, Denmark, Estonia, Finland, France, Germany, Greece, Hungary, Iceland, Ireland, Italy, Japan, Latvia, Liechtenstein, Lithuania, Luxembourg, Malta, Monaco, Montenegro, Netherlands, New Zealand, Norway, Poland, Portugal, Qatar, Romania, San Marino, Singapore, Slovakia, Slovenia, South Korea, Spain, Sweden, Switzerland, United Arab Emirates, United Kingdom, United States, VA.
Tax
Tax residents are taxed on income from sources in and outside Armenia, while non-residents are taxed on Armenian-source income only. A residence card does not decide tax residence. Special regimes exist for high-technology activities and micro-entrepreneurship, and resident organisations pay profit tax.
Standard rules
Personal income tax: residence test and 20% rate
20% tax
Details
- On: Gross income less deductions
- Who: Resident: actual presence of 183 or more days
Residents are taxed on income from sources in and outside Armenia at 20% (rate in force since 1 January 2023); non-residents on Armenian-source income only.
Taxed on
Gross income less deductions; residents worldwide, non-residents Armenian-source (Art. 141, 143).
Who it applies to
- Resident: actual presence of 183 or more days (arrival and departure days count), or centre of vital interests in Armenia.
Exclusions
- Entrepreneurial income of individual entrepreneurs registered in Armenia is outside personal income tax and is taxed under their entrepreneur regime.
Days in the country
- At least 183 days in tax year · Actual presence in Armenia (Tax Code Art. 12 definition of resident natural persons); centre of vital interests is an alternative test.
Tax residence
A residence card does not decide tax residence.
Visas
None.
Other taxes
Pension income from voluntary pension schemes is taxed at 10%; salary of high-technology researchers at 10% under conditions (Art. 150).
Checked against official sources on Change log
Special regime
Turnover tax at 1% for high-technology activities
1% tax
Details
- On: Sales turnover from the high-technology activity list
- Limit: AMD 115M/yr ≈ $318k
Income from activities on the Government high-technology list is taxed at 1% turnover tax by commercial organisations and individual entrepreneurs that qualify as turnover taxpayers; the 1% row applies until 31 December 2031.
Taxed on
Sales turnover from the high-technology activity list (turnover tax replaces VAT and/or profit tax; for individual entrepreneurs it replaces VAT and profit tax is AMD 5,000 (≈ $14) a month).
Who it applies to
- Resident commercial organisation or individual entrepreneur whose sales turnover for all activities did not exceed AMD 115 million (≈ $318,000) in the preceding tax year; statement filed with the tax authority (by 20 February, or within 20 days of registration).
- Activity is on the Government list of high-technology sector activities.
Exclusions
- Banks, insurers, investment companies, notaries, audit companies, legal service providers, crypto-asset providers; legal and accounting activities, management consulting and temporary-staff supply; related persons whose combined turnover exceeds AMD 115 million (≈ $318,000).
Limits
- AMD 115,000,000 a year (≈ $318,000) · Maximum sales turnover in the preceding tax year to be a turnover taxpayer.
- AMD 5,000 a month (≈ $14) · Profit tax of an individual entrepreneur on turnover-tax activities, a final liability.
Tax residence
Resident commercial organisations and individual entrepreneurs only; no days-in-country test applies to the regime.
Visas
An individual entrepreneur or company must be registered in Armenia; entrepreneurship is a temporary residence ground.
Other taxes
Social payments and personal income tax on salaries are separate.
Checked against official sources on Change log
Special regime
Micro-entrepreneurship regime
0% tax
Details
- Limit: AMD 24M/yr ≈ $66k
Entities with turnover up to AMD 24 million (≈ $66,300) in the previous year are exempt from VAT, profit tax and turnover tax obligations and from most state taxes arising from the micro business.
Taxed on
Sales turnover from micro-entrepreneurship activity, up to AMD 24 million (≈ $66,300) in the previous tax year
Who it applies to
- Resident commercial organisation or individual entrepreneur with sales turnover of at most AMD 24 million (≈ $66,300) in the previous tax year; natural persons who are not individual entrepreneurs qualify for activities listed in Annex 3.
Exclusions
- Banks, insurers, investment companies, notaries, audit firms, commercial (purchase and sale) activity, and persons providing consulting, legal, accounting, engineering, advertising, design, marketing, translation, medical, IT-processing, research and development, construction design and similar services; related persons above the combined threshold; rental, interest and royalty recipients.
Limits
- AMD 24,000,000 a year (≈ $66,300) · Maximum sales turnover of the previous tax year.
Visas
Requires registration as an Armenian entity or individual entrepreneur.
Other taxes
Not exempt from import taxes, income tax withheld on payments to non-entrepreneur individuals, excise, environmental and road tax.
Checked against official sources on Change log
Standard rules
Profit tax for resident organisations
18% tax
Details
- On: Taxable profit of resident organisations and permanent establishments
Resident profit taxpayers pay profit tax at 18%; investment funds 0.01%.
Taxed on
Taxable profit of resident organisations and permanent establishments
Visas
None.
Checked against official sources on Change log
Special regime
Armenia turnover tax: 5% to 20% of sales turnover for taxpayers with turnover up to AMD 115 million
Tax relief
Details
- Limit: AMD 115M/yr ≈ $318k
Resident commercial organisations and individual entrepreneurs with sales turnover of up to AMD 115 million (≈ $318,000) in the previous year may elect turnover tax in place of VAT (and, for organisations, profit tax). The rate depends on the activity: 10% trade, 7% production, 10% rent, interest and royalties, 12% public catering, 20% other activity, 1% high-technology activity; an individual entrepreneur on turnover tax pays a fixed AMD 5,000 (≈ $14) a month in place of profit tax.
Taxed on
Sales turnover from supply of goods, works and services (including rent, interest, royalties and transfers of assets). Rates by activity: trade (purchase and sale) 10%; trade in listed secondary raw material 5%; newspaper sales by editorial offices 1.5%; production 7%; rent, interest and royalties 10%; public catering 12%; other activity 10% (20% for non-catering income of catering-election taxpayers); high-technology list activity 1% (row in force until 31 December 2031); alienation of other assets including immovable property 10%. For trade, production, catering and other-activity income, tax is reduced by a percentage of qualifying expenses, subject to minimum floors of 1% to 4.5% of the base.
Who it applies to
- Resident commercial organisations and individual entrepreneurs whose sales turnover in all activities did not exceed AMD 115 million (≈ $318,000) in the preceding tax year may be turnover taxpayers; they submit a statement by 20 February of the tax year (or within 20 days after registration).
- Individual entrepreneurs on turnover tax replace VAT with turnover tax; resident commercial organisations replace VAT and profit tax (the code treats 40% of the tax as profit tax and 60% as VAT).
- Individual entrepreneurs on turnover tax pay profit tax of AMD 5,000 (≈ $14) a month as their final profit tax liability.
- Reporting is quarterly; the return and payment fall due by the 20th day of the month after each quarter.
Exclusions
- Banks, credit organisations, insurers, investment companies, notaries, audit companies, legal service providers, and legal, accounting and head-office consulting activities cannot be turnover taxpayers.
- A taxpayer ceases to be a turnover taxpayer from the point sales turnover exceeds AMD 115 million (≈ $318,000) in the tax year; VAT then applies on the excess.
Limits
- AMD 115,000,000 a year (≈ $318,000) · Sales turnover ceiling for being a turnover taxpayer (previous tax year) and for staying in the regime during the year
- AMD 5,000 a month (≈ $14) · Fixed profit tax of an individual entrepreneur on turnover tax
Tax residence
Taxation of the individual's other income follows the 20% personal income tax for residents (see “Personal income tax: residence test and 20% rate”); the turnover regime applies to the entrepreneurial activity.
Visas
The regime is available to individual entrepreneurs and resident commercial organisations regardless of visa category.
Other taxes
VAT is replaced for turnover taxpayers; taxes not replaced by turnover tax continue to apply under the Tax Code (art. 263).
Checked against official sources on Change log
Checked against official sources on Change log
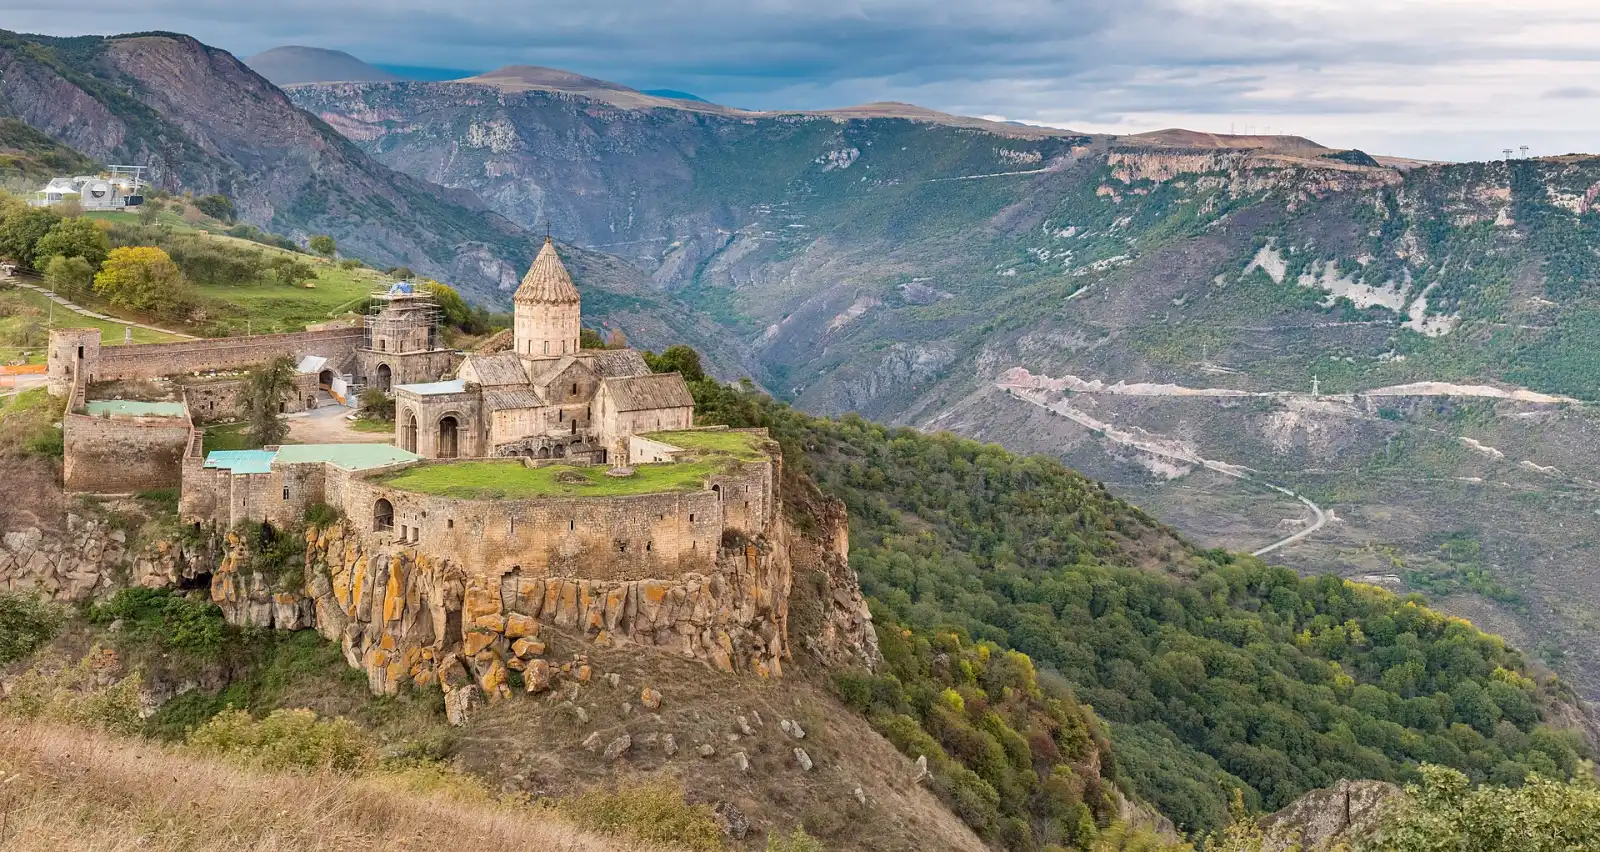
Armenia in pictures
Path to permanent residence · 2
- Citizenship after 3 years · Armenian citizenship through the simplified procedure for persons of Armenian origin (Law on Citizenship Articles 1 and 13)
- PR after 3 years · Permanent residence status
Arriving in Armenia: first steps
- Book an appointment and apply in person for your chosen residence route.
- Prepare your passport with a notarised Armenian translation, photos, and the documents proving your ground.
- Get a medical certificate and pay the state duty, unless your route is exempt.
- If you are an employee, your employer applies online through the work permit platform and obtains Ministry consent.
- Remember that a residence card does not decide tax residence, so check the tax rules separately.
Questions people ask
Can I move to Armenia by starting a business?
Armenia has 1 business or startup route. Entrepreneur residence gives a first stay of 1 year that can be renewed.
What work visas does Armenia offer foreigners?
Armenia has 1 work visa. Work permit gives a first stay of 1 year that can be renewed.
How do I get a student visa for Armenia?
Armenia has 1 student visa. Student residence gives a first stay of 1 year that can be renewed.
Can my nationality or ancestry give me residence in Armenia?
Yes. Armenia has 3 routes by nationality or ancestry. Special residence status gives a first stay of 10 years that can be renewed. Armenian origin residence gives a first stay of 1 year that can be renewed. There is also Armenian citizenship by origin.
Can I join my spouse or partner in Armenia?
Yes. Armenia has 2 spouse visas. Spouse of a citizen gives a first stay of 1 year that can be renewed. Spouse of a resident gives a first stay of 1 year that can be renewed.
Compare with
≈ USD figures are approximate: daily reference rates from ExchangeRate-API, dated 12 Oct 2026, refreshed when the site is updated.
Ask the AI about Armenia AI
An AI assistant answers from the published records on this page and cites them. It can't assess your personal eligibility. Don't include personal details.